Company Coverage
XLSMART Telecom Sejahtera (EXCL IJ): 3Q26: Merger Cost Normalisation to Support Earnings Recovery
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp1,715
Rp3,000
+74.9 %
Rp3.600
Analyst
Analyst
Highlights
- Core mobile operations remain resilient. EXCL was the only MNO among peers to record qoq growth in both ARPU and subscribers, while XL Home subscribers increased 7% qoq.
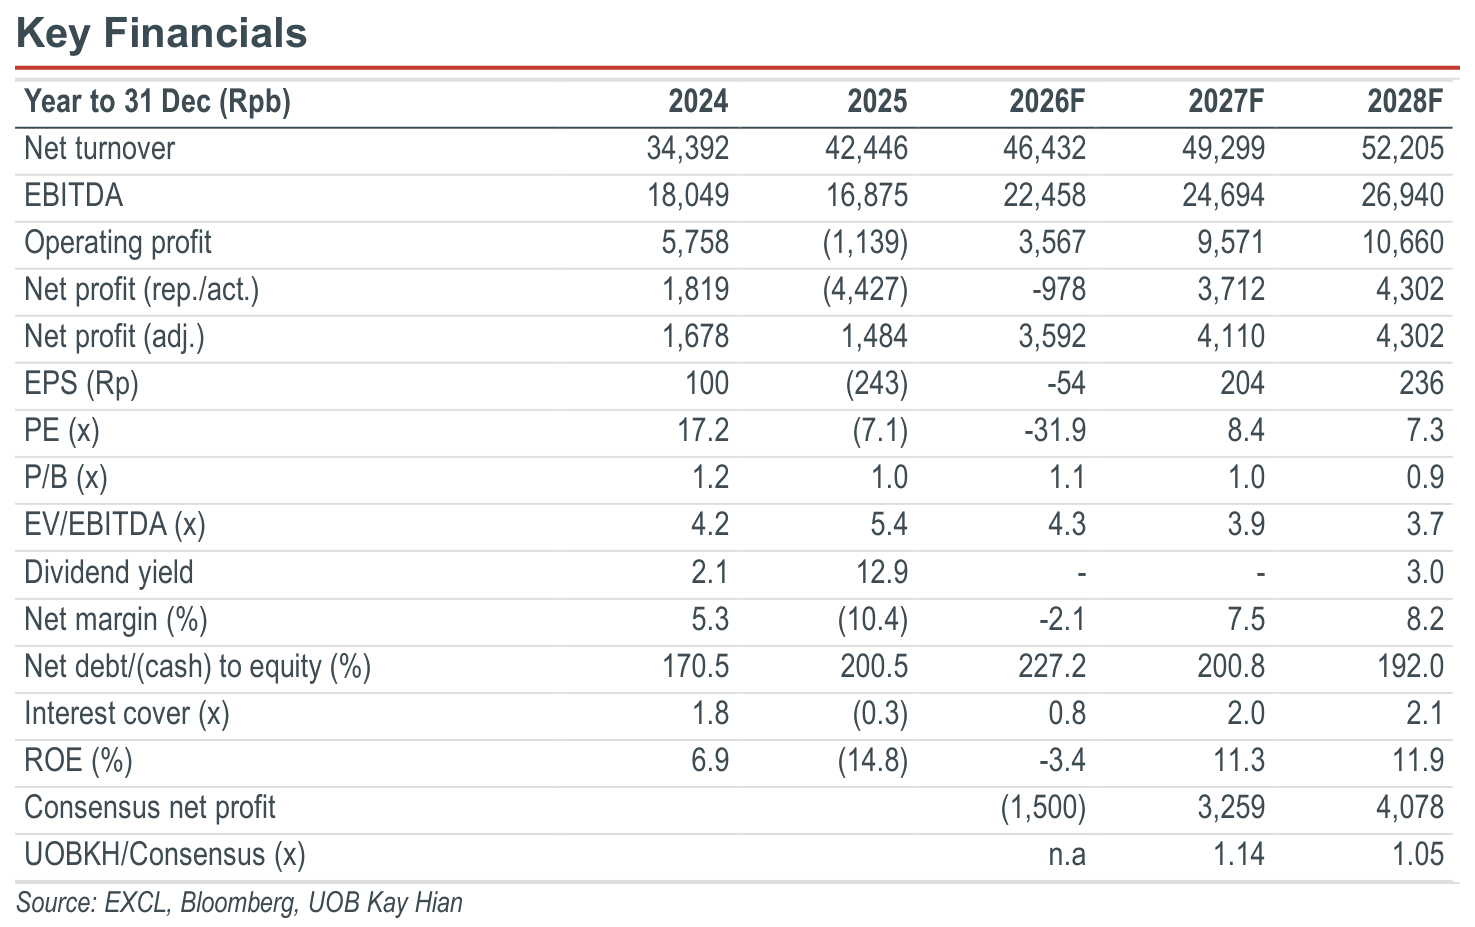
- Merger cost normalisation could drive an earnings re-rating. Accelerated depreciation has been completed, and integration costs are nearing an end. 9M26 synergies reached US$294m, supporting an earnings recovery from 4Q26 onwards.
- Maintain BUY with a lower target price of Rp3,000.
Analysis
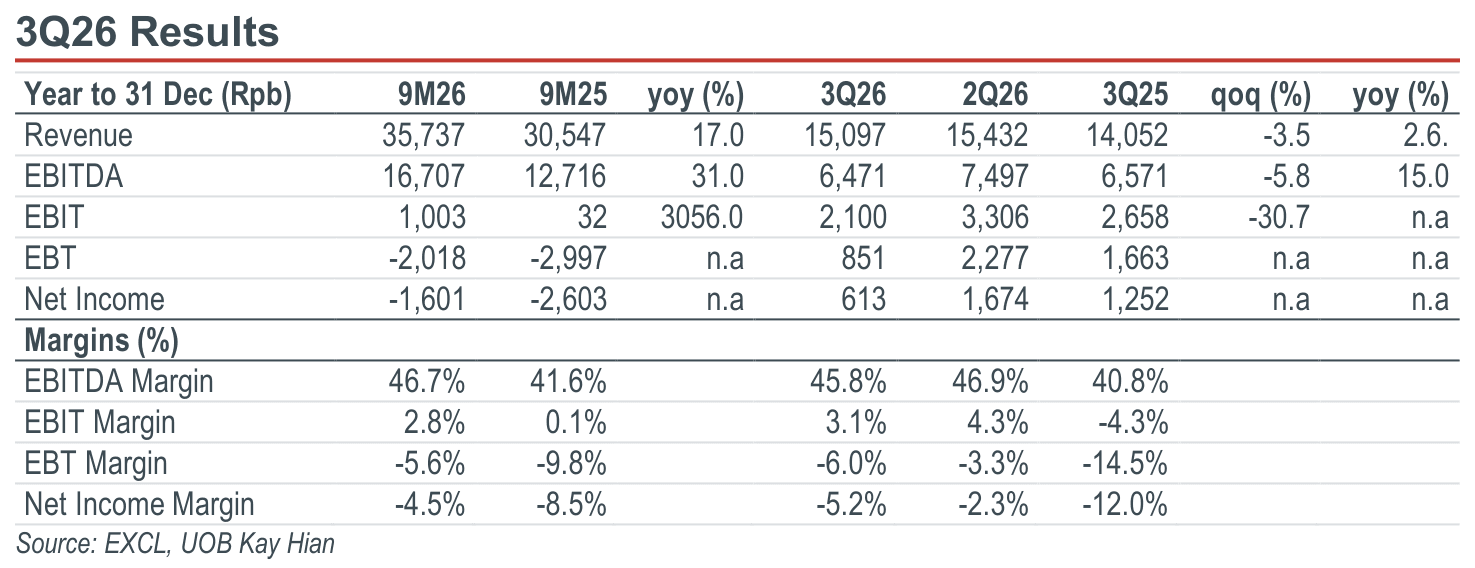
- Merger-related costs nearing completion, with core operations remaining resilient. XLsmart’s (EXCL) 3Q26 net loss widened to Rp607b from Rp277b in the previous quarter, while revenue declined 3.5% qoq, mainly due to lower project-related revenue. However, core network operations remained resilient, with mobile and fixed broadband (FBB) revenue increasing 0.5% qoq, supported by a 0.9% increase in mobile subscribers and higher average revenue per user (ARPU) of Rp47,500 (vs Rp46,900 in 2Q26). Notably, EXCL was the only mobile network operator (MNO) among its peers to record increases in both ARPU and subscribers. XL Home subscribers also grew 7% qoq.
Highlights
- Core mobile operations remain resilient. EXCL was the only MNO among peers to record qoq growth in both ARPU and subscribers, while XL Home subscribers increased 7% qoq.
- Merger cost normalisation could drive an earnings re-rating. Accelerated depreciation has been completed, and integration costs are nearing an end. 9M26 synergies reached US$294m, supporting an earnings recovery from 4Q26 onwards.
- Maintain BUY with a lower target price of Rp3,000.
Analysis
- Merger-related costs nearing completion, with core operations remaining resilient. XLsmart’s (EXCL) 3Q26 net loss widened to Rp607b from Rp277b in the previous quarter, while revenue declined 3.5% qoq, mainly due to lower project-related revenue. However, core network operations remained resilient, with mobile and fixed broadband (FBB) revenue increasing 0.5% qoq, supported by a 0.9% increase in mobile subscribers and higher average revenue per user (ARPU) of Rp47,500 (vs Rp46,900 in 2Q26). Notably, EXCL was the only mobile network operator (MNO) among its peers to record increases in both ARPU and subscribers. XL Home subscribers also grew 7% qoq.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp1,715
Rp3,000
+74.9 %
Rp3.600
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


