Company Coverage
XLSMART Telecom Sejahtera (EXCL IJ): Expect Weak 3Q26 With Earnings Recovery Ahead
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,520
Rp3,600
+136.7 %
Analyst
Analyst
Highlights
- Post-merger charges are nearing completion, but weaker mobile trends remain a headwind. Lower integration costs and accelerated depreciation should support earnings normalisation towards the end of 2026.
- Superior network quality strengthens EXCL's 5G positioning. Faster speeds and an extensive spectrum portfolio could attract higher-value subscribers.
- Maintain BUY with an unchanged target price of Rp3,600, pending 3Q26 results and the earnings call.
Analysis
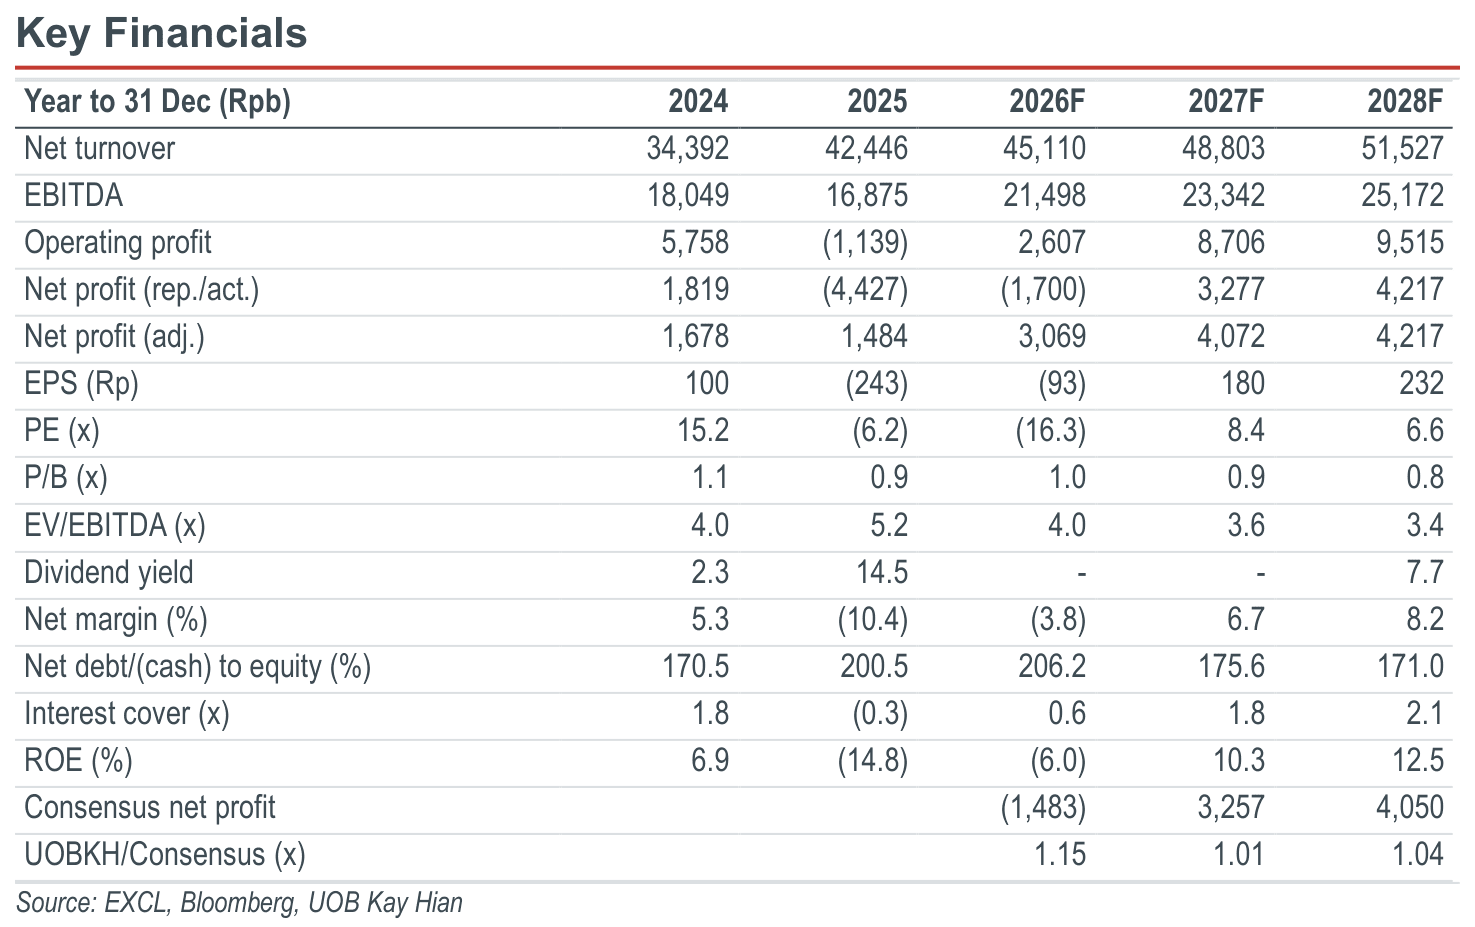
- 3Q26 earnings remain pressured, but post-merger charges are nearing completion. The broader mobile revenue environment remains challenging as both Telkom Indonesia (TLKM) and Indosat (ISAT) recorded qoq declines in cellular revenue in 3Q26, reflecting softer subscriber trends and pressure on new spectrum monetisation. XLSMART Telecom Sejahtera (EXCL) could face similar headwinds, although integration costs should decline to around Rp300b in 2026, down 87% from 2025. Accelerated depreciation is also expected to decline, with approximately Rp1.5t-2t remaining for the year and the bulk of the charges expected to be recognised by 3Q26. This should bring EXCL closer to the end of its post-merger restructuring phase, although reported earnings may remain pressured by the remaining charges.
- Superior network quality could distinguish EXCL and attract higher-value subscribers. Industry checks indicate EXCL was among the early movers in 5G rollout, adopting a nationwide blanket-coverage strategy ahead of peers. Its network has also received independent recognition, winning four Ookla Speedtest Awards in 1H26, including Best 5G Network and Fastest 5G in Indonesia. Opensignal's Jul 26 report showed EXCL's 5G download speed at 135.4 Mbps, ahead of Telkomsel (87.8 Mbps) and ISAT (48.1 Mbps). EXCL also holds an extensive spectrum portfolio, recently securing the largest 700MHz allocation of 30MHz and another 50MHz in the 2.6GHz band. Its early 5G expansion and network readiness could help attract new customers, particularly those seeking higher-speed connectivity, while differentiating EXCL from competitors.
Highlights
- Post-merger charges are nearing completion, but weaker mobile trends remain a headwind. Lower integration costs and accelerated depreciation should support earnings normalisation towards the end of 2026.
- Superior network quality strengthens EXCL's 5G positioning. Faster speeds and an extensive spectrum portfolio could attract higher-value subscribers.
- Maintain BUY with an unchanged target price of Rp3,600, pending 3Q26 results and the earnings call.
Analysis
- 3Q26 earnings remain pressured, but post-merger charges are nearing completion. The broader mobile revenue environment remains challenging as both Telkom Indonesia (TLKM) and Indosat (ISAT) recorded qoq declines in cellular revenue in 3Q26, reflecting softer subscriber trends and pressure on new spectrum monetisation. XLSMART Telecom Sejahtera (EXCL) could face similar headwinds, although integration costs should decline to around Rp300b in 2026, down 87% from 2025. Accelerated depreciation is also expected to decline, with approximately Rp1.5t-2t remaining for the year and the bulk of the charges expected to be recognised by 3Q26. This should bring EXCL closer to the end of its post-merger restructuring phase, although reported earnings may remain pressured by the remaining charges.
- Superior network quality could distinguish EXCL and attract higher-value subscribers. Industry checks indicate EXCL was among the early movers in 5G rollout, adopting a nationwide blanket-coverage strategy ahead of peers. Its network has also received independent recognition, winning four Ookla Speedtest Awards in 1H26, including Best 5G Network and Fastest 5G in Indonesia. Opensignal's Jul 26 report showed EXCL's 5G download speed at 135.4 Mbps, ahead of Telkomsel (87.8 Mbps) and ISAT (48.1 Mbps). EXCL also holds an extensive spectrum portfolio, recently securing the largest 700MHz allocation of 30MHz and another 50MHz in the 2.6GHz band. Its early 5G expansion and network readiness could help attract new customers, particularly those seeking higher-speed connectivity, while differentiating EXCL from competitors.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,520
Rp3,600
+136.7 %
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

4 Nov 2026
Telkom Indonesia (TLKM IJ) - 3Q26: Recovery Ahead, With TIF Monetisation As A Key Catalyst

29 Oct 2026
Indosat (ISAT IJ): 3Q26: AI Cloud And 5G Expansion With Near-term Earnings Pressure

21 Oct 2026
Darma Henwa (DEWA IJ): Ramping Up For 2027 Growth
Our latest research

10 Nov 2026
Mitra Keluarga Karyasehat (MIKA IJ) : Earnings Resilience; Volume Recovery Remains Key

9 Nov 2026
Kalbe Farma (KLBF IJ): Bottom Line Stays Positive Amid Margin Pressure

5 Nov 2026