Company Coverage
Adaro Andalan Indonesia (AADI IJ) - Two Tailwinds: Coal Prices And Special Dividend
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp10,625
Rp13,500
+27.0%
Rp14,300
Analyst
Analyst
Highlights
- Kestrel proceeds create potential for a substantial special dividend. AADI's US$661.3m attributable after-tax proceeds could translate into Rp1,529/share (15.0% yield) assuming a 100% payout, although actual distribution remains subject to capital allocation priorities.
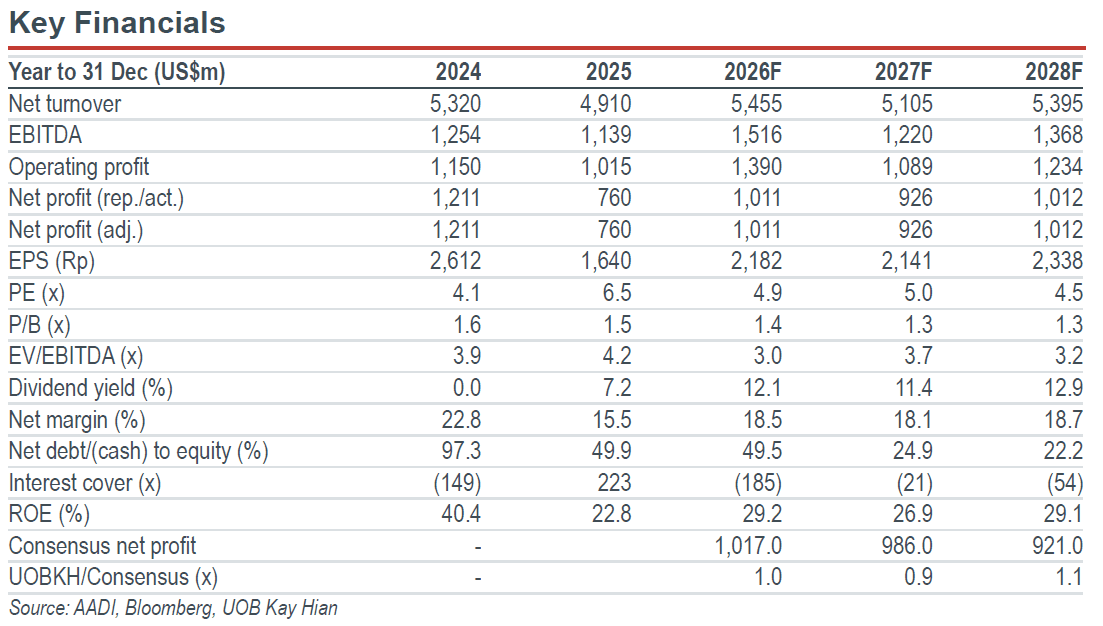
- 4Q26 earnings are likely to remain solid, supported by higher coal prices. We expect higher coal prices (October ICI4: US$78.35/tonne vs US$67.80/tonne in 3Q26) to offset lower volumes, supporting 2026 net profit of nearly US$1.0b (+32.3% yoy).
- Maintain BUY with a higher target price of Rp13,500, down from Rp14,300, based on 6.3x 2027F PE, reflecting Alamtri Resources Indonesia’s (ADRO) five-year average PE.
Analysis
- Kestrel proceeds create potential for a large special dividend. Adaro Andalan Indonesia (AADI) completed the sale of its 47.99% stake in Kestrel to Yancoal on 1 Oct 26 for US$814.12m before tax and US$734.83m after tax, subject to sales and purchase agreement adjustments. AADI cited the intended use of the proceeds for dividends, business development in Indonesia and partial loan repayment. AADI holds the stake through 90%-owned Adaro Capital, leaving US$661.3m attributable to AADI after tax. On our illustrative assumption of a 100% payout of this amount, the dividend would be Rp11.9t or Rp1,529/share, a potential 15.0% yield. Management has not announced a payout, and competing uses make 100% an upper-end scenario for the upfront proceeds. AADI also remains attractive from a core dividend perspective, with its 2025 payout ratio at 59.2%.
- 4Q26 earnings are likely to remain solid, supported by higher coal prices. Despite lower sales volume and a higher strip ratio, we believe stronger coal prices could support profitability. We estimate that 4Q26 ASP could increase by up to 15% qoq, assuming the Oct 26 ICI4 price of US$78.35/tonne is sustained, compared with US$67.80/tonne in 3Q26. This should help offset lower expected sales volume of 17.2mt (-3.7% qoq; -10.6% yoy). Consequently, we expect 2026 net profit to approach US$1.0b, representing a 32.3% yoy growth. Amid tighter domestic supply from El Niño-related disruptions, AADI is likely to maintain its 30% domestic market obligation (DMO) through 4Q26, with a similar allocation expected in 2027.
Highlights
- Kestrel proceeds create potential for a substantial special dividend. AADI's US$661.3m attributable after-tax proceeds could translate into Rp1,529/share (15.0% yield) assuming a 100% payout, although actual distribution remains subject to capital allocation priorities.
- 4Q26 earnings are likely to remain solid, supported by higher coal prices. We expect higher coal prices (October ICI4: US$78.35/tonne vs US$67.80/tonne in 3Q26) to offset lower volumes, supporting 2026 net profit of nearly US$1.0b (+32.3% yoy).
- Maintain BUY with a higher target price of Rp13,500, down from Rp14,300, based on 6.3x 2027F PE, reflecting Alamtri Resources Indonesia’s (ADRO) five-year average PE.
Analysis
- Kestrel proceeds create potential for a large special dividend. Adaro Andalan Indonesia (AADI) completed the sale of its 47.99% stake in Kestrel to Yancoal on 1 Oct 26 for US$814.12m before tax and US$734.83m after tax, subject to sales and purchase agreement adjustments. AADI cited the intended use of the proceeds for dividends, business development in Indonesia and partial loan repayment. AADI holds the stake through 90%-owned Adaro Capital, leaving US$661.3m attributable to AADI after tax. On our illustrative assumption of a 100% payout of this amount, the dividend would be Rp11.9t or Rp1,529/share, a potential 15.0% yield. Management has not announced a payout, and competing uses make 100% an upper-end scenario for the upfront proceeds. AADI also remains attractive from a core dividend perspective, with its 2025 payout ratio at 59.2%.
- 4Q26 earnings are likely to remain solid, supported by higher coal prices. Despite lower sales volume and a higher strip ratio, we believe stronger coal prices could support profitability. We estimate that 4Q26 ASP could increase by up to 15% qoq, assuming the Oct 26 ICI4 price of US$78.35/tonne is sustained, compared with US$67.80/tonne in 3Q26. This should help offset lower expected sales volume of 17.2mt (-3.7% qoq; -10.6% yoy). Consequently, we expect 2026 net profit to approach US$1.0b, representing a 32.3% yoy growth. Amid tighter domestic supply from El Niño-related disruptions, AADI is likely to maintain its 30% domestic market obligation (DMO) through 4Q26, with a similar allocation expected in 2027.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp10,625
Rp13,500
+27.0%
Rp14,300
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

4 Nov 2026
Telkom Indonesia (TLKM IJ) - 3Q26: Recovery Ahead, With TIF Monetisation As A Key Catalyst

16 Oct 2026
Astra Otoparts (AUTO IJ): Organic Growth And Potential M&A to Drive Expansion

12 Oct 2026
Sarana Menara Nusantara (TOWR IJ): 5G Densification And Potential DC Rollouts Offer Upside
Our latest research
4 Nov 2026
Telkom Indonesia (TLKM IJ) - 3Q26: Recovery Ahead, With TIF Monetisation As A Key Catalyst

2 Nov 2026
GoTo Gojek Tokopedia (GOTO IJ) - 3Q26: Third Straight Profitable Quarter, Ahead of Forecast

30 Oct 2026