Company Coverage
Telkom Indonesia (TLKM IJ) - 3Q26: Recovery Ahead, With TIF Monetisation As A Key Catalyst
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,880
Rp3,300
+75.5%
Analyst
Analyst
Highlights
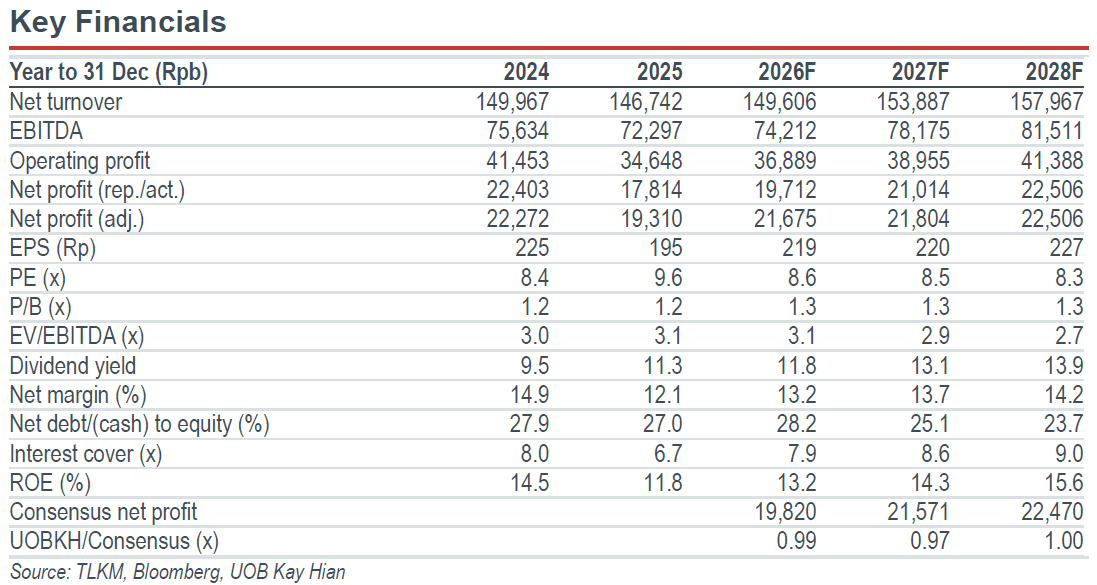
- 4Q26 recovery expected as pricing pressure eases. Seasonal ARPU recovery, new campaigns and network improvements should support stronger performance, while capex remains within guidance.
- TIF monetisation remains the key value-unlocking catalyst. Further BUMN asset consolidation could strengthen TIF’s scale ahead of a strategic stake sale, although management changes may introduce near-term execution risks and delay monetisation.
- Maintain BUY with an unchanged target price of Rp3,300.
Analysis
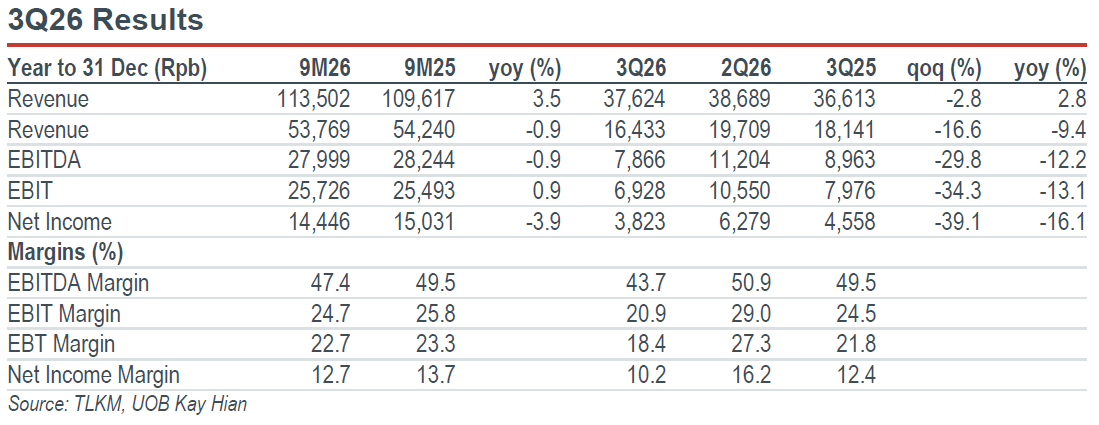
- Operating trends should improve in 4Q26, although macro headwinds and restructuring remain near-term risks. Telkom Indonesia’s (TLKM) 3Q26 revenue declined 2.8% qoq, weighed by a 3.6% drop in mobile revenue as ARPU fell to Rp44,900 from Rp46,000 in 2Q26 and mobile subscribers declined 1.6% qoq. Higher operating costs, including spectrum acquisition and personnel expenses, alongside around Rp1.3t in unrealised investment losses, further pressured profitability, bringing EBITDA margin to 43.7%. Management expects margin pressure to ease in 4Q26 as pricing pressure moderates, supported by seasonal ARPU recovery, new campaigns and network improvements. TLKM is maintaining its 2026 guidance and targeting a stronger 4Q26 performance at Telkomsel. Capex is expected to remain within 17-19% of revenue, with spending increasingly directed toward B2B infrastructure, including subsea cables and data centres. NeutraDC also targets 400MW of capacity by 2030, with an aspirational target of 1GW, providing additional long-term growth opportunities.
Highlights
- 4Q26 recovery expected as pricing pressure eases. Seasonal ARPU recovery, new campaigns and network improvements should support stronger performance, while capex remains within guidance.
- TIF monetisation remains the key value-unlocking catalyst. Further BUMN asset consolidation could strengthen TIF’s scale ahead of a strategic stake sale, although management changes may introduce near-term execution risks and delay monetisation.
- Maintain BUY with an unchanged target price of Rp3,300.
Analysis
- Operating trends should improve in 4Q26, although macro headwinds and restructuring remain near-term risks. Telkom Indonesia’s (TLKM) 3Q26 revenue declined 2.8% qoq, weighed by a 3.6% drop in mobile revenue as ARPU fell to Rp44,900 from Rp46,000 in 2Q26 and mobile subscribers declined 1.6% qoq. Higher operating costs, including spectrum acquisition and personnel expenses, alongside around Rp1.3t in unrealised investment losses, further pressured profitability, bringing EBITDA margin to 43.7%. Management expects margin pressure to ease in 4Q26 as pricing pressure moderates, supported by seasonal ARPU recovery, new campaigns and network improvements. TLKM is maintaining its 2026 guidance and targeting a stronger 4Q26 performance at Telkomsel. Capex is expected to remain within 17-19% of revenue, with spending increasingly directed toward B2B infrastructure, including subsea cables and data centres. NeutraDC also targets 400MW of capacity by 2030, with an aspirational target of 1GW, providing additional long-term growth opportunities.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,880
Rp3,300
+75.5%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

12 Oct 2026
Sarana Menara Nusantara (TOWR IJ): 5G Densification And Potential DC Rollouts Offer Upside

16 Oct 2026
Astra Otoparts (AUTO IJ): Organic Growth And Potential M&A to Drive Expansion

30 Sept 2026
Telkom Indonesia (TLKM IJ): Value Unlocked With Potential Execution Risks
Our latest research

2 Nov 2026
GoTo Gojek Tokopedia (GOTO IJ) - 3Q26: Third Straight Profitable Quarter, Ahead of Forecast

30 Oct 2026
Medikaloka Hermina (HEAL IJ): 3Q26: Sequential Improvement, But Earnings And Valuation Remain Under Pressure

29 Oct 2026