Company Coverage
Indosat (ISAT IJ): 3Q26: AI Cloud And 5G Expansion With Near-term Earnings Pressure
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp1,570
Rp2,450
+56.8%
Rp2,500
Analyst
Analyst
Highlights
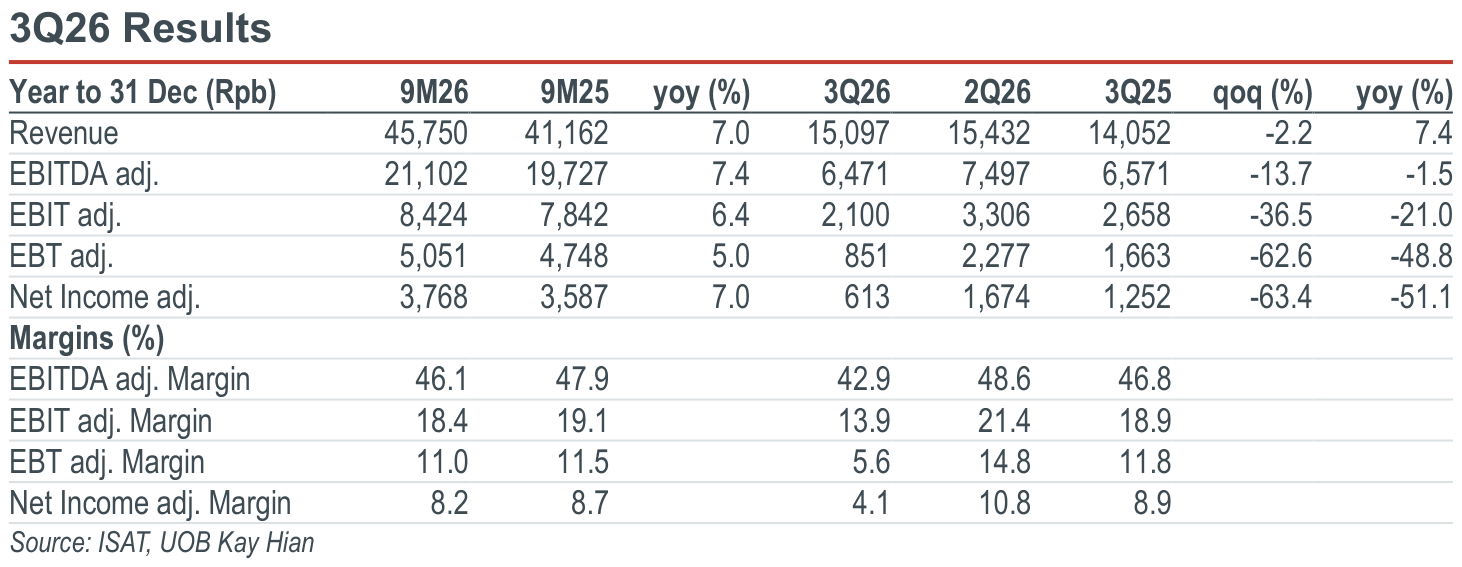
- Earnings pressured by rising costs. Lower cellular revenue and higher costs drove a 13.7% qoq decline in adjusted EBITDA and a 63.4% drop in adjusted net profit.
- AI Cloud and 5G offer long-term growth. AI Cloud contracted annual revenue is expected to exceed US$300m from 2027, although elevated capex remains a near-term headwind.
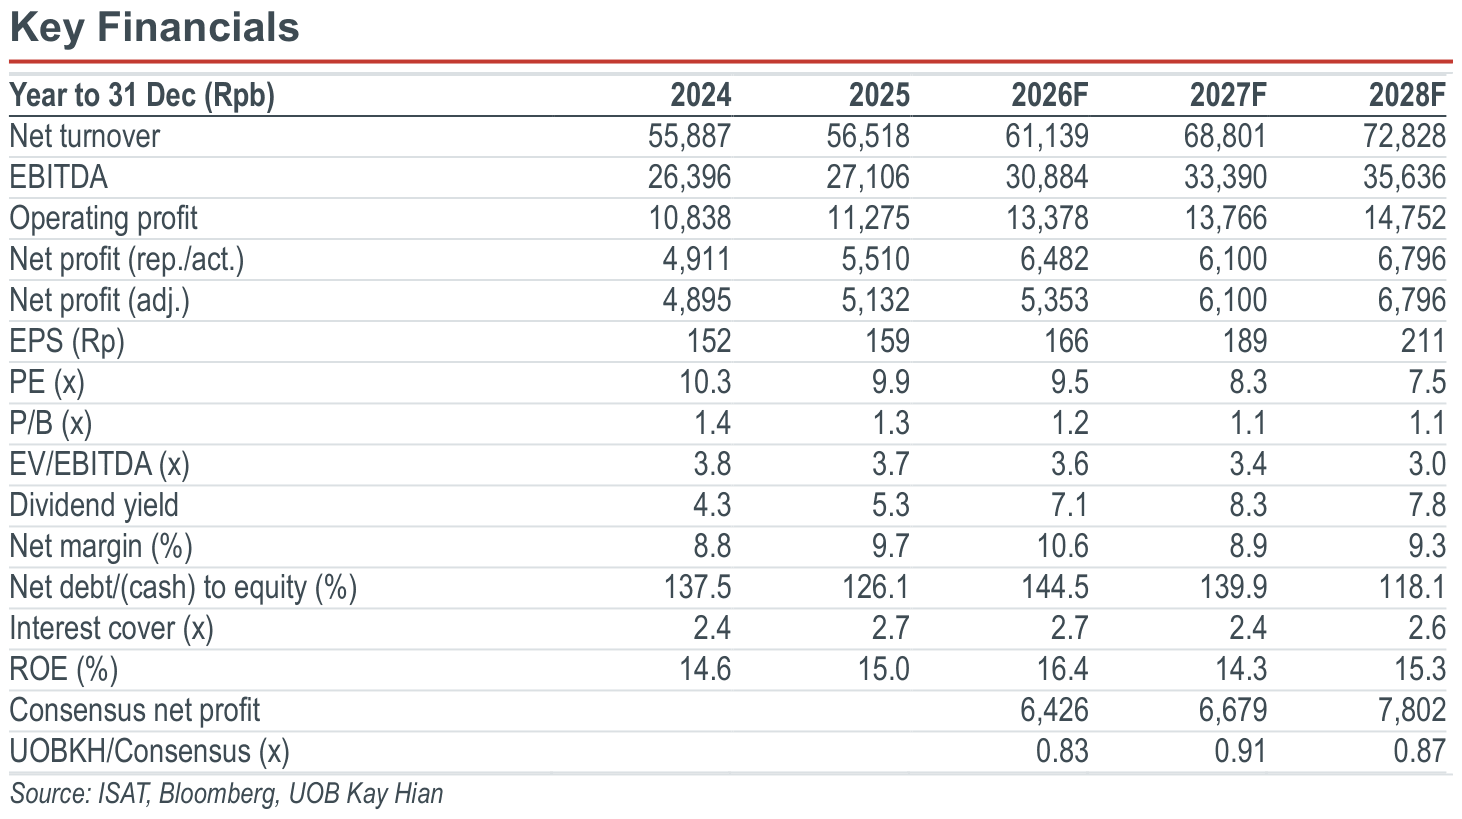
- Maintain BUY with a lower target price of Rp2,450.
Analysis
- Weaker cellular revenue and rising costs weigh on earnings. Indosat (ISAT) recorded its first cellular revenue decline of the year in 3Q26, down 3.9% qoq, while average revenue per user (ARPU) remained broadly flat at Rp46,000 versus Rp45,000 in 1Q26 despite ongoing monetisation initiatives. Subscribers declined to 91.5m in 3Q26 from 93.4m in 2Q26, partly reflecting customer base rationalisation following mandatory biometric SIM registration. Lower revenue, alongside higher cost of services (+6% qoq), personnel expenses (+17%) and depreciation (+4%), drove a 13.7% qoq decline in adjusted EBITDA and a 63.4% decline in normalised net profit to Rp613b. Cost pressures also reflected higher employee compensation following a provision reversal in 2Q26 and 5G spectrum costs incurred ahead of monetisation. Management maintained its 2026 revenue and EBITDA growth guidance of close to double-digits, although annualised 9M26 adjusted EBITDA growth remains below the guided level.
Highlights
- Earnings pressured by rising costs. Lower cellular revenue and higher costs drove a 13.7% qoq decline in adjusted EBITDA and a 63.4% drop in adjusted net profit.
- AI Cloud and 5G offer long-term growth. AI Cloud contracted annual revenue is expected to exceed US$300m from 2027, although elevated capex remains a near-term headwind.
- Maintain BUY with a lower target price of Rp2,450.
Analysis
- Weaker cellular revenue and rising costs weigh on earnings. Indosat (ISAT) recorded its first cellular revenue decline of the year in 3Q26, down 3.9% qoq, while average revenue per user (ARPU) remained broadly flat at Rp46,000 versus Rp45,000 in 1Q26 despite ongoing monetisation initiatives. Subscribers declined to 91.5m in 3Q26 from 93.4m in 2Q26, partly reflecting customer base rationalisation following mandatory biometric SIM registration. Lower revenue, alongside higher cost of services (+6% qoq), personnel expenses (+17%) and depreciation (+4%), drove a 13.7% qoq decline in adjusted EBITDA and a 63.4% decline in normalised net profit to Rp613b. Cost pressures also reflected higher employee compensation following a provision reversal in 2Q26 and 5G spectrum costs incurred ahead of monetisation. Management maintained its 2026 revenue and EBITDA growth guidance of close to double-digits, although annualised 9M26 adjusted EBITDA growth remains below the guided level.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp1,570
Rp2,450
+56.8%
Rp2,500
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


