Company Coverage
Elnusa (ELSA IJ): Expect Solid 2H26 Earnings And New Growth Opportunities Ahead
BUY (Maintained)
Current price:
Target price:
Upside:
Rp640
Rp1,450
+114.8%
Analyst
Analyst
Highlights
- ELSA’s earnings are expected to strengthen in 2H26, as seismic contracts ramp up and downstream demand remains solid.
- Potential catalysts include LCO expansion, new seismic contracts, fleet renewal, and a higher dividend for next year.
- Maintain BUY with a DCF-based target price of Rp1,450, supported by strong earnings growth.
Analysis
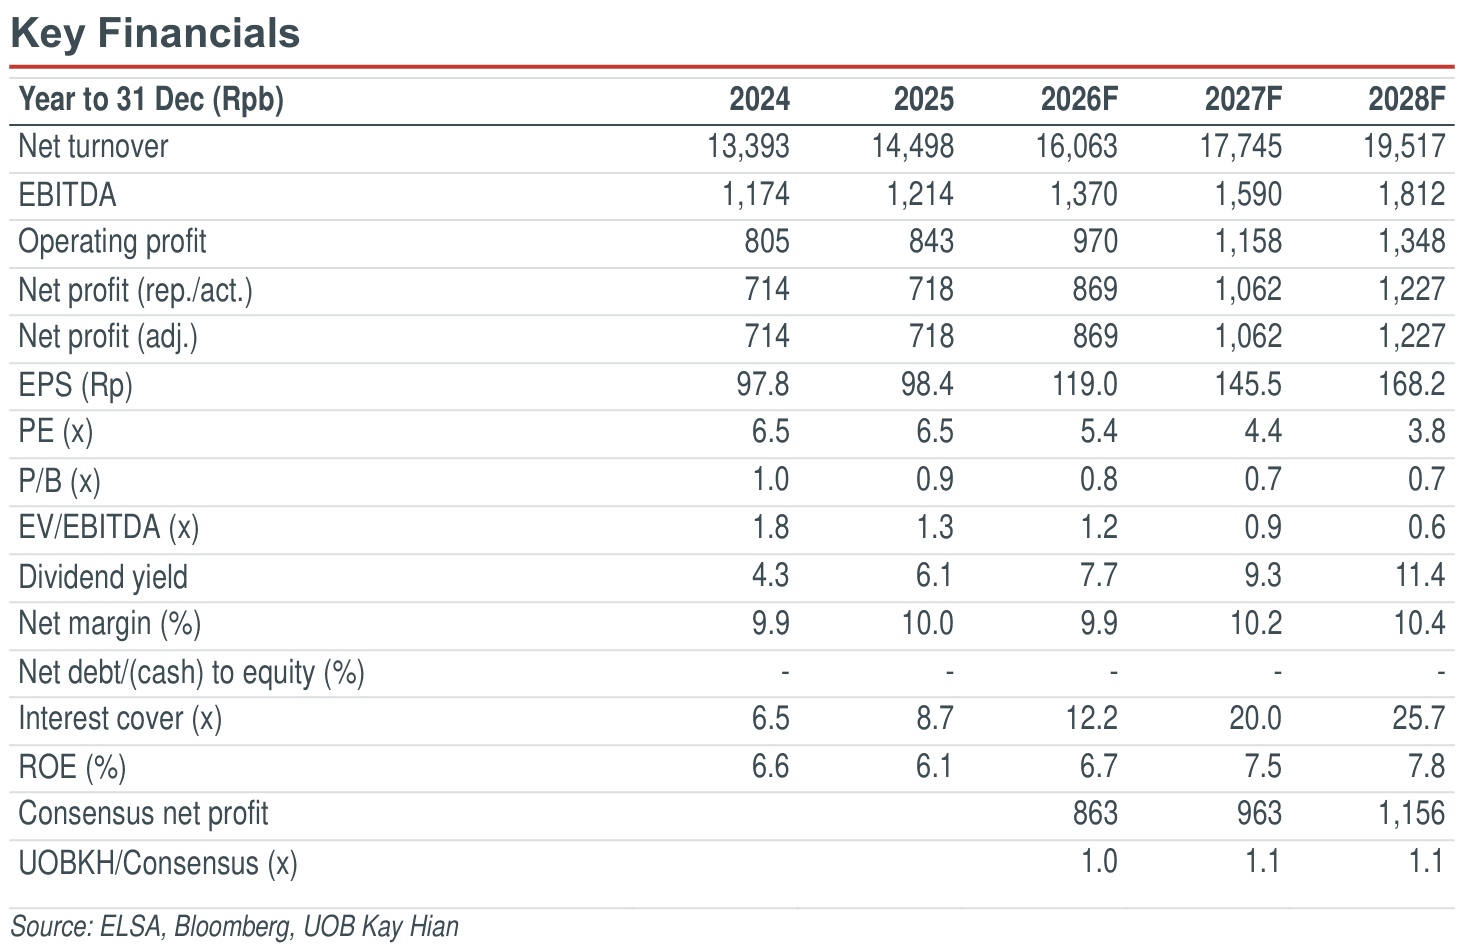
- Expect a stronger 2H26. We project that 2026 earnings growth will remain upbeat after a strong 1H26 net profit growth of 29.4% yoy. We expect 2H26 earnings to be partially driven by the commencement of its seismic contract, resulting in 2026 net profit growing 23.7% yoy. Seismic contracts secured in late-25 and early-26 began contributing in 3Q26, with limited contributions in 2Q26 as work only commenced around Jun 26. This timing mismatch weighed on upstream margins, particularly in seismic projects, which typically have a two- to three-month lag between mobilisation cost recognition and invoicing once recording activities commence. Note that seismic has a relatively high margin impact on Elnusa’s (ELSA) integrated upstream O&G services business, which has a three-year median quarterly gross margin of 10.8%, compared with 8.0% for the distribution business.
Some prospective projects could be converted into contracts in 2H26, while others are expected to commence in 2027. On the downstream segment, we expect 2H26 growth to remain upbeat after a strong 1H26 revenue growth of 26.6% thanks to higher ex-Java demand (particularly Sumatra and Kalimantan) as well as stronger industrial and marine fuel trading.
- Potential upstream business through LCO model. ELSA has submitted a study to take over underutilised marginal wells from Pertamina Hulu Energi (PHE) and operate them under a low-cost operator (LCO) scheme, subject to PHE’s approval as controlling shareholder. Management emphasised that the proposal remains preliminary. If approved, ELSA would acquire the assets outright rather than adopt a profit-sharing scheme, implying higher upstream costs and capex from 2027. The initiative could broaden ELSA’s business mix beyond oilfield services into upstream production, with potential margin upside but greater exposure to oil price volatility and operational risks.
Highlights
- ELSA’s earnings are expected to strengthen in 2H26, as seismic contracts ramp up and downstream demand remains solid.
- Potential catalysts include LCO expansion, new seismic contracts, fleet renewal, and a higher dividend for next year.
- Maintain BUY with a DCF-based target price of Rp1,450, supported by strong earnings growth.
Analysis
- Expect a stronger 2H26. We project that 2026 earnings growth will remain upbeat after a strong 1H26 net profit growth of 29.4% yoy. We expect 2H26 earnings to be partially driven by the commencement of its seismic contract, resulting in 2026 net profit growing 23.7% yoy. Seismic contracts secured in late-25 and early-26 began contributing in 3Q26, with limited contributions in 2Q26 as work only commenced around Jun 26. This timing mismatch weighed on upstream margins, particularly in seismic projects, which typically have a two- to three-month lag between mobilisation cost recognition and invoicing once recording activities commence. Note that seismic has a relatively high margin impact on Elnusa’s (ELSA) integrated upstream O&G services business, which has a three-year median quarterly gross margin of 10.8%, compared with 8.0% for the distribution business.
Some prospective projects could be converted into contracts in 2H26, while others are expected to commence in 2027. On the downstream segment, we expect 2H26 growth to remain upbeat after a strong 1H26 revenue growth of 26.6% thanks to higher ex-Java demand (particularly Sumatra and Kalimantan) as well as stronger industrial and marine fuel trading.
- Potential upstream business through LCO model. ELSA has submitted a study to take over underutilised marginal wells from Pertamina Hulu Energi (PHE) and operate them under a low-cost operator (LCO) scheme, subject to PHE’s approval as controlling shareholder. Management emphasised that the proposal remains preliminary. If approved, ELSA would acquire the assets outright rather than adopt a profit-sharing scheme, implying higher upstream costs and capex from 2027. The initiative could broaden ELSA’s business mix beyond oilfield services into upstream production, with potential margin upside but greater exposure to oil price volatility and operational risks.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp640
Rp1,450
+114.8%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


