Company Coverage
Cisarua Mountain Dairy (CMRY IJ): On Track For Guidance
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp4,250
Rp5,800
+36.5%
Rp6,400
Analyst
Analyst
Highlights
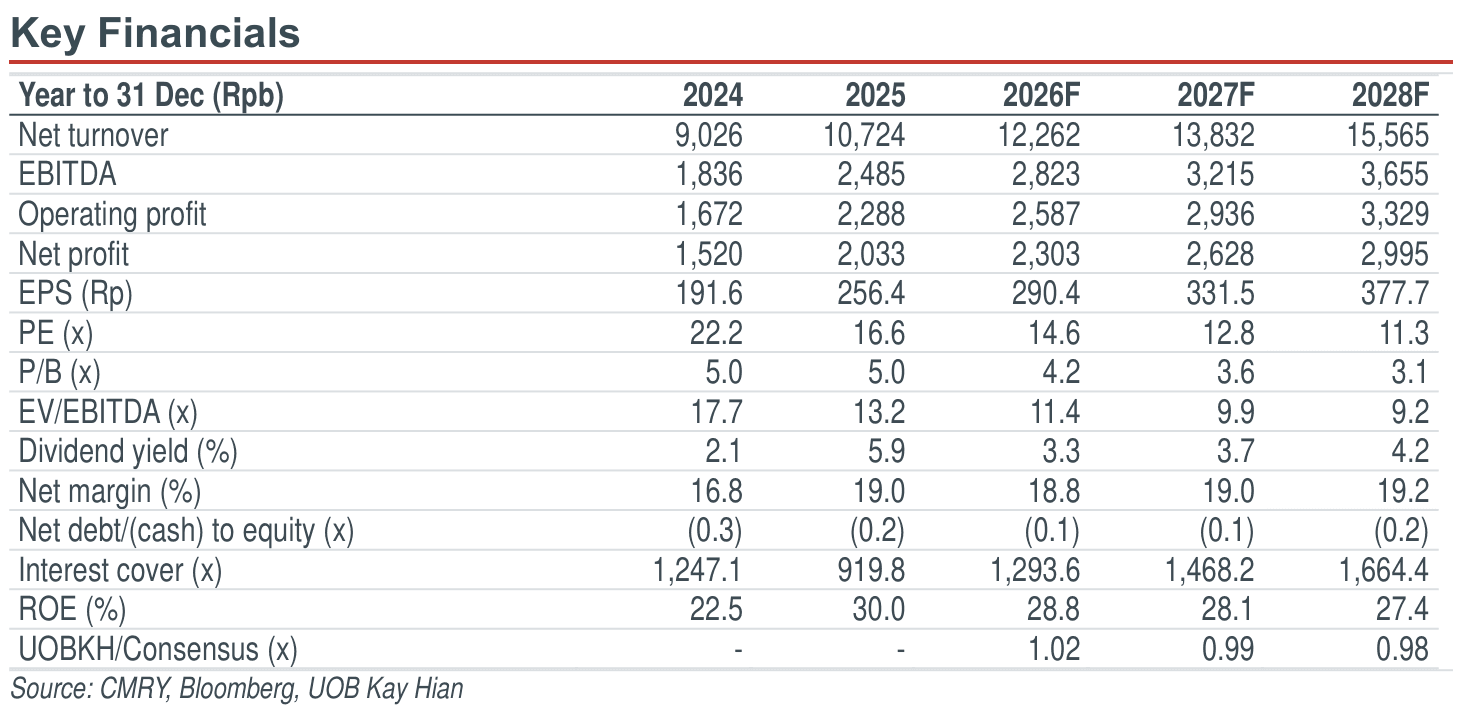
- Growth should stay resilient into 3Q26, keeping CMRY on track for its 15-20% revenue growth guidance for 2026. Gross margin should remain within the 42-44% guidance range (2025: 45.3%) despite the weak rupiah.
- The growth story remains intact on channel expansion and product innovation, backed by a solid balance sheet. Margins should recover in 2027 on a price increase, insurance recovery and direct milk powder imports.
- Maintain BUY with a lower target price of Rp5,800 (from Rp6,400) based on 20x 2026F PE.
Analysis
- Growth stays resilient into 3Q26. Cisarua Mountain Dairy (CMRY) posted another record quarter, with 2Q26 revenue up 23% yoy, driven entirely by volume. Dairy remained the key driver, up 57% yoy for a fourth consecutive quarter of double-digit growth, on outlet expansion, larger drop sizes and product innovation. Consumer foods grew by a more modest 6% yoy, which the company attributed to the free meal programme reducing breakfast consumption at home and to its capacity being fully utilised, hence growth should stay modest until the new plant starts operations in 1Q27. We expect this trend to continue into 3Q26, keeping CMRY on track for its 2026 revenue growth guidance of 15-20% (1H26: +25.5% yoy).
- GT and Miss Cimory remained the key drivers. The sales mix continued to shift toward these higher-growth channels, with General Trade (GT) rising to 38% of 1H26 sales (1H25: 35%) and Miss Cimory to 21% (20%), while MT declined to 36% (41%). This was supported by a 6.6% yoy increase in GT outlets to 210,849 and a 28% rise in Miss Cimory agents to 9,778, with management targeting 500,000 outlets and 20,000 agents by 2030. Meanwhile, exports doubled yoy, albeit still contributing only 1.5% of sales. CMRY also opened its first Cimory Yogurt store as a direct-to-consumer channel, which remains in its initial phase and serves mainly for branding purposes, with no aggressive rollout planned.
- Margin holding within guidance. 2Q26 gross margin declined to 43.5% (2Q25: 45.3%), as CMRY fully absorbed higher raw material costs and rupiah depreciation without raising ASP. Operating margin fell further to 18.3% (2Q25: 23.3%), also weighed by a Rp97b inventory fire provision (2.9% of sales). Margins should remain under pressure in 2H26 due to the weak rupiah, although management expects gross margin to stay within its 42-44% guidance range. Looking ahead, a selective ASP increase in December, the insurance recovery expected in 1Q27, and direct imports of whole milk powder from 2027, bypassing local distributors, should provide margin upside.
Highlights
- Growth should stay resilient into 3Q26, keeping CMRY on track for its 15-20% revenue growth guidance for 2026. Gross margin should remain within the 42-44% guidance range (2025: 45.3%) despite the weak rupiah.
- The growth story remains intact on channel expansion and product innovation, backed by a solid balance sheet. Margins should recover in 2027 on a price increase, insurance recovery and direct milk powder imports.
- Maintain BUY with a lower target price of Rp5,800 (from Rp6,400) based on 20x 2026F PE.
Analysis
- Growth stays resilient into 3Q26. Cisarua Mountain Dairy (CMRY) posted another record quarter, with 2Q26 revenue up 23% yoy, driven entirely by volume. Dairy remained the key driver, up 57% yoy for a fourth consecutive quarter of double-digit growth, on outlet expansion, larger drop sizes and product innovation. Consumer foods grew by a more modest 6% yoy, which the company attributed to the free meal programme reducing breakfast consumption at home and to its capacity being fully utilised, hence growth should stay modest until the new plant starts operations in 1Q27. We expect this trend to continue into 3Q26, keeping CMRY on track for its 2026 revenue growth guidance of 15-20% (1H26: +25.5% yoy).
- GT and Miss Cimory remained the key drivers. The sales mix continued to shift toward these higher-growth channels, with General Trade (GT) rising to 38% of 1H26 sales (1H25: 35%) and Miss Cimory to 21% (20%), while MT declined to 36% (41%). This was supported by a 6.6% yoy increase in GT outlets to 210,849 and a 28% rise in Miss Cimory agents to 9,778, with management targeting 500,000 outlets and 20,000 agents by 2030. Meanwhile, exports doubled yoy, albeit still contributing only 1.5% of sales. CMRY also opened its first Cimory Yogurt store as a direct-to-consumer channel, which remains in its initial phase and serves mainly for branding purposes, with no aggressive rollout planned.
- Margin holding within guidance. 2Q26 gross margin declined to 43.5% (2Q25: 45.3%), as CMRY fully absorbed higher raw material costs and rupiah depreciation without raising ASP. Operating margin fell further to 18.3% (2Q25: 23.3%), also weighed by a Rp97b inventory fire provision (2.9% of sales). Margins should remain under pressure in 2H26 due to the weak rupiah, although management expects gross margin to stay within its 42-44% guidance range. Looking ahead, a selective ASP increase in December, the insurance recovery expected in 1Q27, and direct imports of whole milk powder from 2027, bypassing local distributors, should provide margin upside.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp4,250
Rp5,800
+36.5%
Rp6,400
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

24 Sept 2026
Erajaya Swasembada (ERAA IJ): Continuous Successful Expansion

6 Oct 2026
Japfa Comfeed Indonesia (JPFA IJ): Site Visit Takeaways, Further Scaling Up Downstream

13 Oct 2026


