Company Coverage
Indofood CBP Sukses Makmur (ICBP IJ): Volume Strength Intact; Margins Still The Swing Factor
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp6,700
Rp9,500
+41.8%
Rp10,150
Analyst
Analyst
Highlights
- 9M26 revenue grew 14.5% yoy, well above the initial 5-7% guidance, but higher input costs and a weaker rupiah limited core profit growth to 4.5%.
- New capacity and overseas growth sustain volumes; the mid-October price hike should keep 4Q26 margin broadly stable qoq. The recent easing in wheat prices should also improve sentiment going forward.
- Maintain BUY with a lower target price of Rp9,500 (from Rp10,150), based on 9.5x 2027F PE. ICBP is also executing its first ever Rp750b buyback.
Analysis
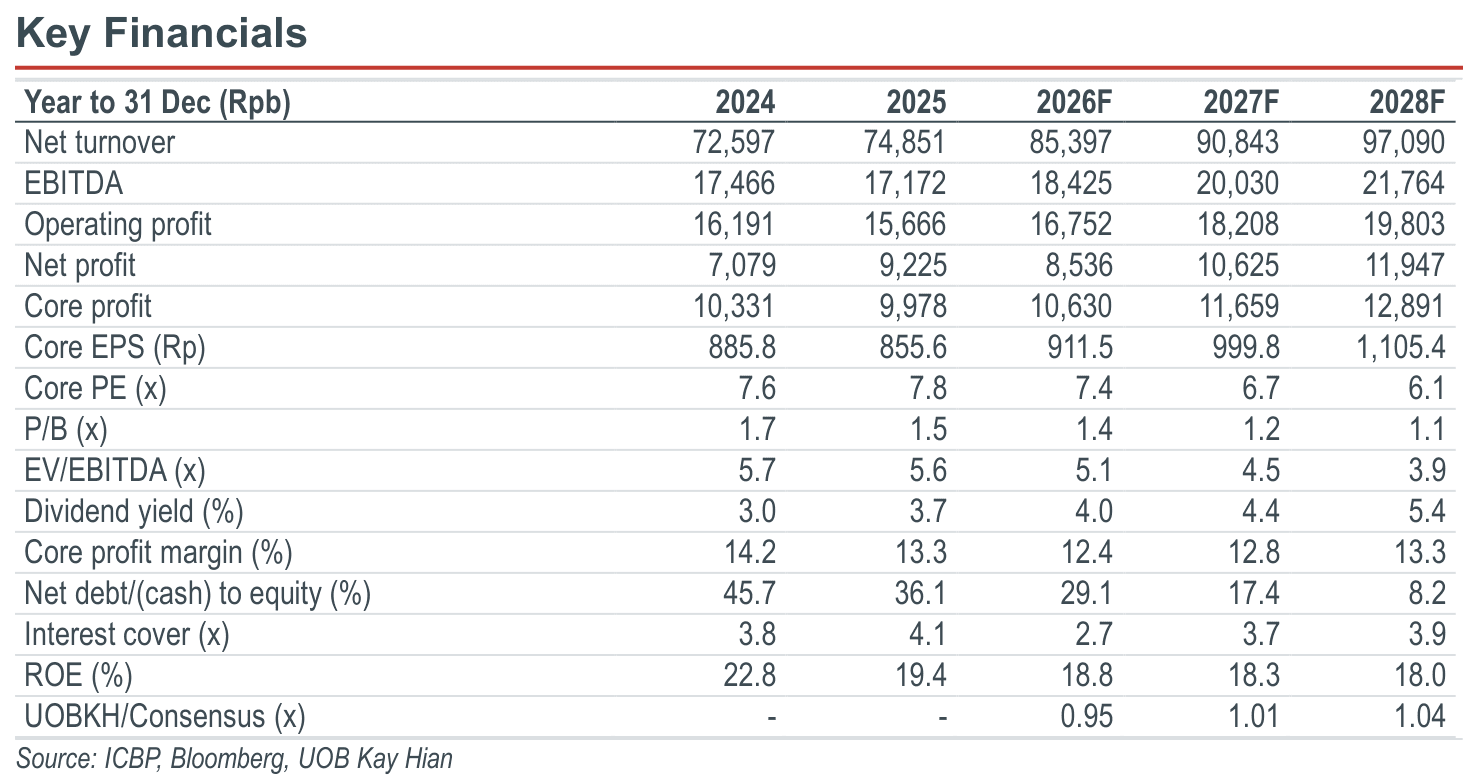
- Top-line beat, but cost pressure capped earnings. Indofood CBP’s (ICBP) 9M26 revenue rose 14.5% yoy to Rp64.4t, its fastest since 9M22, prompting management to raise guidance to 12-14% (from 5-7%). Growth was broad-based (overseas +23%, domestic +11%) and mostly volume-led. However, higher raw material and freight costs and a weaker rupiah cut the EBIT margin to 21.2% (9M25: 22.6%), though it remains within the 20-22% guidance range. Core profit rose only 4.5% yoy to Rp8t but was slightly ahead of our estimate. Reported net profit fell 13.3% yoy to Rp6.2t on a Rp3.3t unrealised forex loss on its US dollar bonds (9M25: Rp1.4t).
- Growth momentum to continue, backed by new capacity and supply chain resilience. We expect 2026 revenue growth to reach the top end of the 12-14% guidance, although 4Q26 is likely to moderate qoq on seasonality and possible pre-buying ahead of the noodle ASP increase. New capacity from the factory opened in Dec 25 (+1.5b-2.0b packs a year, lifting domestic capacity by ~7%), wider distribution and 35+ new SKUs in 9M26 kept demand resilient despite a soft macro backdrop. Its supply chain also proved to be an edge. With about 22% of COGS sourced from the Indofood group and local production overseas through Pinehill, ICBP’s overseas revenue grew 23% yoy in 9M26, while its competitors faced shipping and packaging disruptions from the Iran conflict.
- Price hike in mid-Oct 26 to cushion cost pressure. Amid persistently high raw material costs, with wheat and milk powder prices up about 9% qoq in 3Q26 (Bogasari also raised flour prices by a cumulative ~5% over May-Sep 26 and a further ~3% in Oct 26), we see the 3% domestic noodle ASP increase from mid-October as largely offsetting the lagged impact of these increases, keeping 4Q26 gross margin broadly stable qoq. That said, a more visible margin recovery still hinges on a stable rupiah, easing milk powder prices and limited El Niño impact on CPO.
Highlights
- 9M26 revenue grew 14.5% yoy, well above the initial 5-7% guidance, but higher input costs and a weaker rupiah limited core profit growth to 4.5%.
- New capacity and overseas growth sustain volumes; the mid-October price hike should keep 4Q26 margin broadly stable qoq. The recent easing in wheat prices should also improve sentiment going forward.
- Maintain BUY with a lower target price of Rp9,500 (from Rp10,150), based on 9.5x 2027F PE. ICBP is also executing its first ever Rp750b buyback.
Analysis
- Top-line beat, but cost pressure capped earnings. Indofood CBP’s (ICBP) 9M26 revenue rose 14.5% yoy to Rp64.4t, its fastest since 9M22, prompting management to raise guidance to 12-14% (from 5-7%). Growth was broad-based (overseas +23%, domestic +11%) and mostly volume-led. However, higher raw material and freight costs and a weaker rupiah cut the EBIT margin to 21.2% (9M25: 22.6%), though it remains within the 20-22% guidance range. Core profit rose only 4.5% yoy to Rp8t but was slightly ahead of our estimate. Reported net profit fell 13.3% yoy to Rp6.2t on a Rp3.3t unrealised forex loss on its US dollar bonds (9M25: Rp1.4t).
- Growth momentum to continue, backed by new capacity and supply chain resilience. We expect 2026 revenue growth to reach the top end of the 12-14% guidance, although 4Q26 is likely to moderate qoq on seasonality and possible pre-buying ahead of the noodle ASP increase. New capacity from the factory opened in Dec 25 (+1.5b-2.0b packs a year, lifting domestic capacity by ~7%), wider distribution and 35+ new SKUs in 9M26 kept demand resilient despite a soft macro backdrop. Its supply chain also proved to be an edge. With about 22% of COGS sourced from the Indofood group and local production overseas through Pinehill, ICBP’s overseas revenue grew 23% yoy in 9M26, while its competitors faced shipping and packaging disruptions from the Iran conflict.
- Price hike in mid-Oct 26 to cushion cost pressure. Amid persistently high raw material costs, with wheat and milk powder prices up about 9% qoq in 3Q26 (Bogasari also raised flour prices by a cumulative ~5% over May-Sep 26 and a further ~3% in Oct 26), we see the 3% domestic noodle ASP increase from mid-October as largely offsetting the lagged impact of these increases, keeping 4Q26 gross margin broadly stable qoq. That said, a more visible margin recovery still hinges on a stable rupiah, easing milk powder prices and limited El Niño impact on CPO.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp6,700
Rp9,500
+41.8%
Rp10,150
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
Adaro Andalan Indonesia (AADI IJ) - Two Tailwinds: Coal Prices And Special Dividend

28 Oct 2026
Unilever Indonesia (UNVR IJ): Volumes Hold Up; Margins Under Pressure

22 Oct 2026
Cisarua Mountain Dairy (CMRY IJ): On Track For Guidance
Our latest research

13 Nov 2026
Indo Tambangraya Megah (ITMG IJ): 3Q26: Higher ASP And Continued Buyback Incentive

12 Nov 2026
XLSMART Telecom Sejahtera (EXCL IJ): Expect Weak 3Q26 With Earnings Recovery Ahead

10 Nov 2026