Company Coverage
Alamtri Resources Indonesia (ADRO IJ): Solid Earnings Momentum From Aluminium Production Ramp-up
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp2,440
Rp3,240
+32.8%
Rp3,400
Analyst
Analyst
Highlights
- KAI's full-scale operations strengthen earnings diversification. KAI targets 2026 production of 370,000 tonnes and sales of 300,000-340,000 tonnes, supporting a higher aluminium earnings contribution in 4Q26.
- Weather disruptions constrain metallurgical coal sales. 4Q26 sales will depend on the recovery of Barito River water levels following logistical disruptions caused by prolonged extreme dry weather conditions.
- Maintain BUY with a lower target price of Rp3,240 (previous: Rp3,400).
Analysis
- Strong 9M26 earnings of US$517m. Alamtri Resources Indonesia’s (ADRO) 3Q26 net profit increased 14.3% qoq to US$207.2m (+63.6% yoy), as minority interest jumped to US$70.3m (2Q26: US$4.3m) as its new aluminium segment started contributing to earnings. ADRO’s 9M26 net profit increased by 71% yoy to US$517m, accounting 72% of our 2026 and 83% of consensus.
- Aluminium operations achieve full-scale production. Following the completion of its production ramp-up and transition to full-scale operations in 3Q26, Kalimantan Aluminium Industry (KAI) is targeting 2026 production of 370,000 tonnes and sales volume of 300,000-340,000 tonnes. With production reaching 249,000 tonnes and sales totalling 146,000 tonnes in 9M26, KAI is positioned to ramp up its contribution in 4Q26. Around 98% of aluminium sales are directed to export markets.
- Weather constraints limit sales volume. Metallurgical coal sales volume declined by 13% yoy to 3.85mt in 9M26, mainly due to logistical disruptions caused by prolonged extreme dry weather conditions during 3Q26, which have persisted into November. Consequently, shipments were deferred and 4Q26 sales will depend on the Barito River water level, which needs to rise to 19.6 metres from the current 16-18 metres. ADRO expects 2026 sales volume of 5.0-5.5mt, subject to improvements in the Barito River water level.
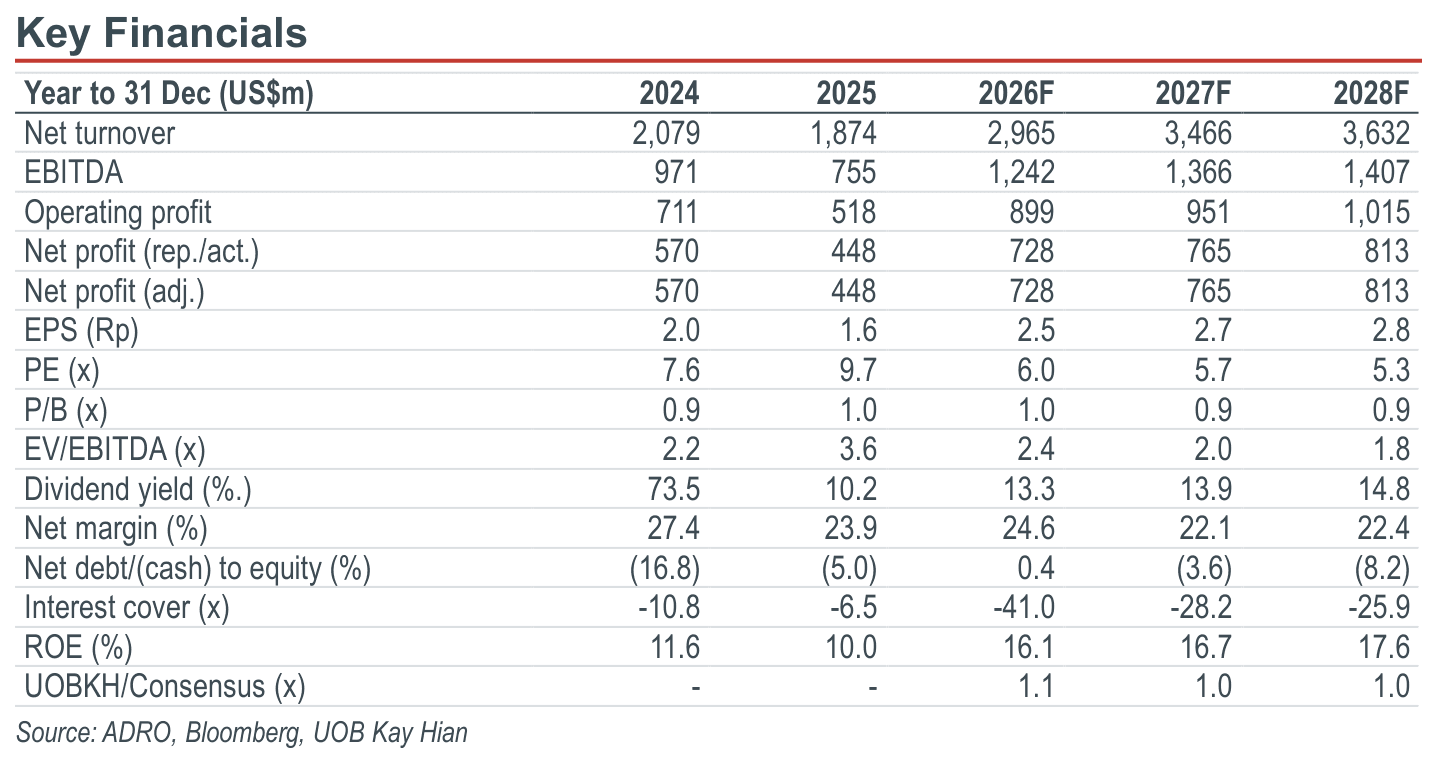
- We expect 2027 earnings to remain solid at US$765m. With KAI operating at full capacity, we expect aluminium production to reach 500,000 tonnes in 2027. We also expect the logistical disruptions along the Barito River caused by prolonged extreme weather to normalise in 2027, supporting a 9.4% yoy recovery in coal sales volume. Accordingly, we forecast 2027 net profit of US$765m (+5.5% yoy).
- Attractive dividend yield. If the green project delays are prolonged, we expect 2027's dividend yield to come in at 14.2%, assuming an 80% payout.
Highlights
- KAI's full-scale operations strengthen earnings diversification. KAI targets 2026 production of 370,000 tonnes and sales of 300,000-340,000 tonnes, supporting a higher aluminium earnings contribution in 4Q26.
- Weather disruptions constrain metallurgical coal sales. 4Q26 sales will depend on the recovery of Barito River water levels following logistical disruptions caused by prolonged extreme dry weather conditions.
- Maintain BUY with a lower target price of Rp3,240 (previous: Rp3,400).
Analysis
- Strong 9M26 earnings of US$517m. Alamtri Resources Indonesia’s (ADRO) 3Q26 net profit increased 14.3% qoq to US$207.2m (+63.6% yoy), as minority interest jumped to US$70.3m (2Q26: US$4.3m) as its new aluminium segment started contributing to earnings. ADRO’s 9M26 net profit increased by 71% yoy to US$517m, accounting 72% of our 2026 and 83% of consensus.
- Aluminium operations achieve full-scale production. Following the completion of its production ramp-up and transition to full-scale operations in 3Q26, Kalimantan Aluminium Industry (KAI) is targeting 2026 production of 370,000 tonnes and sales volume of 300,000-340,000 tonnes. With production reaching 249,000 tonnes and sales totalling 146,000 tonnes in 9M26, KAI is positioned to ramp up its contribution in 4Q26. Around 98% of aluminium sales are directed to export markets.
- Weather constraints limit sales volume. Metallurgical coal sales volume declined by 13% yoy to 3.85mt in 9M26, mainly due to logistical disruptions caused by prolonged extreme dry weather conditions during 3Q26, which have persisted into November. Consequently, shipments were deferred and 4Q26 sales will depend on the Barito River water level, which needs to rise to 19.6 metres from the current 16-18 metres. ADRO expects 2026 sales volume of 5.0-5.5mt, subject to improvements in the Barito River water level.
- We expect 2027 earnings to remain solid at US$765m. With KAI operating at full capacity, we expect aluminium production to reach 500,000 tonnes in 2027. We also expect the logistical disruptions along the Barito River caused by prolonged extreme weather to normalise in 2027, supporting a 9.4% yoy recovery in coal sales volume. Accordingly, we forecast 2027 net profit of US$765m (+5.5% yoy).
- Attractive dividend yield. If the green project delays are prolonged, we expect 2027's dividend yield to come in at 14.2%, assuming an 80% payout.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp2,440
Rp3,240
+32.8%
Rp3,400
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
Adaro Andalan Indonesia (AADI IJ) - Two Tailwinds: Coal Prices And Special Dividend

30 Sept 2026
Telkom Indonesia (TLKM IJ): Value Unlocked With Potential Execution Risks

26 Oct 2026
AKR Corporindo (AKRA IJ): 3Q26: T&D Margin Recovery Supports Earnings Upside
Our latest research

16 Nov 2026
Indofood CBP Sukses Makmur (ICBP IJ): Volume Strength Intact; Margins Still The Swing Factor

13 Nov 2026
Indo Tambangraya Megah (ITMG IJ): 3Q26: Higher ASP And Continued Buyback Incentive

12 Nov 2026