Company Coverage
Mitra Keluarga Karyasehat (MIKA IJ) : Earnings Resilience; Volume Recovery Remains Key
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp1,310
Rp1,900
+45.0%
Rp2,500
Analyst
Highlights
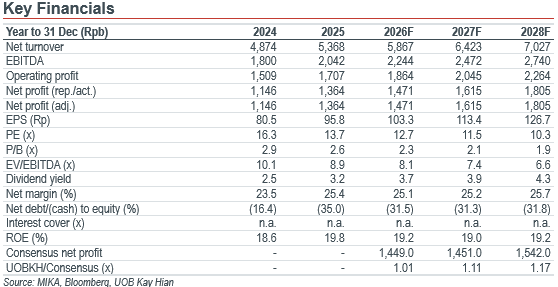
Resilient earnings despite weaker utilisation. 9M26 EBITDA grew 8.2% yoy, supported by higher revenue intensity despite declining patient volumes. 2026 revenue growth guidance was cut to to high single-digits.
Higher-acuity services support growth, but volume recovery remains important. High-complexity revenue rose 25.2% yoy, while private payers contributed 90% of revenue, Weak utilisation remains a concern heading into 2027.
Maintain BUY; lower target price to Rp1,900. We cut our target 2027F EV/EBITDA to 10.0x from 13.6x, reflecting higher country risk and weaker visibility on patient volume recovery, while maintaining MIKA's valuation premium over HEAL.
Analysis
Resilient earnings mask weaker underlying hospital utilisation. Mitra Keluarga Karyasehat’s (MIKA) earnings have remained relatively resilient despite softer patient demand, supported by higher revenue intensity and increasing contribution from complex treatments. In 9M26, inpatient admissions declined 3.6% yoy, outpatient visists fell 1.9%, and bed occupancy rate (BOR) dropped to 52.6% (9M25: 56.8%). Nevertheless, revenue and EBITDA increased 7.2% and 8.2% yoy respectively, supported by double-digit growth in revenue per patient. Management attributed much of the volume weakness to declining National Health Insurance (BPJS) patients while private patient volume continued to grow. However, MIKA lowered its 2026 revenue growth guidance from low teens to high single-digit, suggesting a slower growth trajectory than previously expected. We believe a sustained recovery will depend on patient volume growth alongside continued improvement in revenue intensity.
Higher-acuity services and private-payer exposure support earnings resilience. MIKA has continued shifting toward more complex treatments, including oncology, cardiovascular care, and neuroscience. High-complexity revenue increased 25.2% yoy in 9M26, lifting its contritbution to 28% of revenue (9M25: 24%). This suggests that higher revenue intensity is increasingly supported by improving treatment mix rather than tariff increases alone. However, higher treatment intensity also increases the use speciality drugs, implants and consumables, contributing to a lower gross margin. Private patients accounted for 90% of revenue (9M25: 88%). This provides greater flexibility in service offerings and pricing relative to BPJS-dependent operators. However, a larger private-payer contribution does not eliminate demand risks, particularly amid weaker household purchasing power and increasing scrutiny of healthcare cost by private insurers.
Highlights
Resilient earnings despite weaker utilisation. 9M26 EBITDA grew 8.2% yoy, supported by higher revenue intensity despite declining patient volumes. 2026 revenue growth guidance was cut to to high single-digits.
Higher-acuity services support growth, but volume recovery remains important. High-complexity revenue rose 25.2% yoy, while private payers contributed 90% of revenue, Weak utilisation remains a concern heading into 2027.
Maintain BUY; lower target price to Rp1,900. We cut our target 2027F EV/EBITDA to 10.0x from 13.6x, reflecting higher country risk and weaker visibility on patient volume recovery, while maintaining MIKA's valuation premium over HEAL.
Analysis
Resilient earnings mask weaker underlying hospital utilisation. Mitra Keluarga Karyasehat’s (MIKA) earnings have remained relatively resilient despite softer patient demand, supported by higher revenue intensity and increasing contribution from complex treatments. In 9M26, inpatient admissions declined 3.6% yoy, outpatient visists fell 1.9%, and bed occupancy rate (BOR) dropped to 52.6% (9M25: 56.8%). Nevertheless, revenue and EBITDA increased 7.2% and 8.2% yoy respectively, supported by double-digit growth in revenue per patient. Management attributed much of the volume weakness to declining National Health Insurance (BPJS) patients while private patient volume continued to grow. However, MIKA lowered its 2026 revenue growth guidance from low teens to high single-digit, suggesting a slower growth trajectory than previously expected. We believe a sustained recovery will depend on patient volume growth alongside continued improvement in revenue intensity.
Higher-acuity services and private-payer exposure support earnings resilience. MIKA has continued shifting toward more complex treatments, including oncology, cardiovascular care, and neuroscience. High-complexity revenue increased 25.2% yoy in 9M26, lifting its contritbution to 28% of revenue (9M25: 24%). This suggests that higher revenue intensity is increasingly supported by improving treatment mix rather than tariff increases alone. However, higher treatment intensity also increases the use speciality drugs, implants and consumables, contributing to a lower gross margin. Private patients accounted for 90% of revenue (9M25: 88%). This provides greater flexibility in service offerings and pricing relative to BPJS-dependent operators. However, a larger private-payer contribution does not eliminate demand risks, particularly amid weaker household purchasing power and increasing scrutiny of healthcare cost by private insurers.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp1,310
Rp1,900
+45.0%
Rp2,500
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


