Company Coverage
Kalbe Farma (KLBF IJ): Bottom Line Stays Positive Amid Margin Pressure
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp755
Rp1,000
+32.5%
Rp1,100
Analyst
Analyst
Highlights
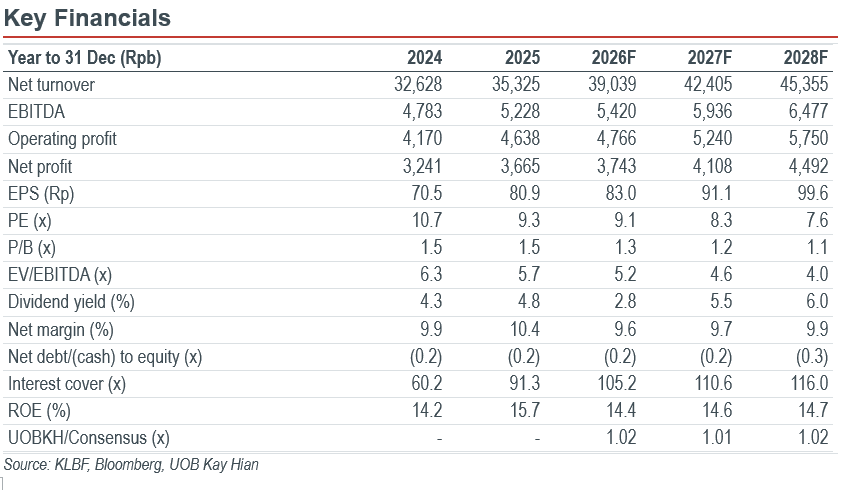
9M26 net profit grew 4% yoy (above expectations), as solid sales and opex control offset margin pressure. With API costs stabilising, 2026 profit growth should stay positive.
Product innovation across segments should sustain volume growth. The company also has a strong balance sheet and an ongoing Rp500b buyback.
Maintain BUY with a lower target price of Rp1,000 (from Rp1,100), based on 11.0x 2027F PE (-1SD below its three-year forward average).
Analysis
Bottom line to stay positive despite margin pressure. Kalbe Farma’s (KLBF) 9M26 net profit rose 4% yoy to Rp2.74t, slightly above expectations (79%/80% of our/consensus 2026 forecasts respectively), on 11.5% yoy revenue growth to Rp29t, largely volume-driven, as ASP hikes (3-5%) were limited to selected consumer health products. Gross margin fell to 37.6% (9M25: 40.6%) on higher oil-linked active pharmaceutical ingredients (API) costs (~15% of COGS), a weaker rupiah and a generics-heavy prescription mix (gross margin of 46% vs 51%). Lower promotion and G&A spending cut opex-to-sales to 25.7% (9M25: 27.9%), cushioning the margin squeeze. On a positive note, management noted that API costs have stabilised from their 2Q26 peak, supporting a gross margin recovery to 37.8% in 3Q26 (2Q26: 36.8%), with margins expected to remain stable in 4Q26. This should keep positive earnings growth in 2026 achievable, in line with guidance. A more meaningful recovery in 2027 hinges on rupiah stability and oil prices.
Leading defensive pharma, more resilient in a challenging market. KLBF’s scale, own distribution network and strong net cash position place it in a better position than most to absorb higher raw material costs and a weaker rupiah. Its pharma market share has risen to about 14% from ~11% in 2022. This was supported by continued gains in unbranded generics, which was the fastest-growing category in 3Q26, as BPJS and private hospitals shift away from branded products. In consumer health, KLBF’s brands also lead with 30-70% market share across key over-the-counter (OTC) categories.
Innovation and expansion continue across segments. In pharma, KLBF is moving into biologics, including Efesa for kidney disease and Zerpidio for oncology, with local insulin and GLP-1 production next. In 9M26, nutritionals revenue returned to growth (+4.1% yoy) as its shift toward lifestyle and ready-to-drink products like Hydrococo gained traction.
Highlights
9M26 net profit grew 4% yoy (above expectations), as solid sales and opex control offset margin pressure. With API costs stabilising, 2026 profit growth should stay positive.
Product innovation across segments should sustain volume growth. The company also has a strong balance sheet and an ongoing Rp500b buyback.
Maintain BUY with a lower target price of Rp1,000 (from Rp1,100), based on 11.0x 2027F PE (-1SD below its three-year forward average).
Analysis
Bottom line to stay positive despite margin pressure. Kalbe Farma’s (KLBF) 9M26 net profit rose 4% yoy to Rp2.74t, slightly above expectations (79%/80% of our/consensus 2026 forecasts respectively), on 11.5% yoy revenue growth to Rp29t, largely volume-driven, as ASP hikes (3-5%) were limited to selected consumer health products. Gross margin fell to 37.6% (9M25: 40.6%) on higher oil-linked active pharmaceutical ingredients (API) costs (~15% of COGS), a weaker rupiah and a generics-heavy prescription mix (gross margin of 46% vs 51%). Lower promotion and G&A spending cut opex-to-sales to 25.7% (9M25: 27.9%), cushioning the margin squeeze. On a positive note, management noted that API costs have stabilised from their 2Q26 peak, supporting a gross margin recovery to 37.8% in 3Q26 (2Q26: 36.8%), with margins expected to remain stable in 4Q26. This should keep positive earnings growth in 2026 achievable, in line with guidance. A more meaningful recovery in 2027 hinges on rupiah stability and oil prices.
Leading defensive pharma, more resilient in a challenging market. KLBF’s scale, own distribution network and strong net cash position place it in a better position than most to absorb higher raw material costs and a weaker rupiah. Its pharma market share has risen to about 14% from ~11% in 2022. This was supported by continued gains in unbranded generics, which was the fastest-growing category in 3Q26, as BPJS and private hospitals shift away from branded products. In consumer health, KLBF’s brands also lead with 30-70% market share across key over-the-counter (OTC) categories.
Innovation and expansion continue across segments. In pharma, KLBF is moving into biologics, including Efesa for kidney disease and Zerpidio for oncology, with local insulin and GLP-1 production next. In 9M26, nutritionals revenue returned to growth (+4.1% yoy) as its shift toward lifestyle and ready-to-drink products like Hydrococo gained traction.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp755
Rp1,000
+32.5%
Rp1,100
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the following link: https://research-api.uobkayhian.com/assets/disclaimer/df64a6ea-7980-447c-ae9e-fd19b93257dc, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


