Company Coverage
AKR Corporindo (AKRA IJ): 3Q26: T&D Margin Recovery Supports Earnings Upside
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,390
Rp1,600
+15.1%
Analyst
Highlights
- 9M26 earnings ahead of expectations. Net profit rose 34% yoy to Rp2.2t, reaching 83% of our 2026 forecast and 77% of consensus. T&D gross margin recovered to 6.9% in 3Q26 from 4.6% in 2Q26, supporting earnings despite lower sequential revenue.
- JIIPE land sales on target; utilities gaining momentum. Land sales reached 93ha in 9M26, meeting management's 90-100ha 2026 target range. Utilities revenue grew 46.6% qoq to Rp305b in 3Q26, bringing 9M26 revenue to 73% of the 2026 target.
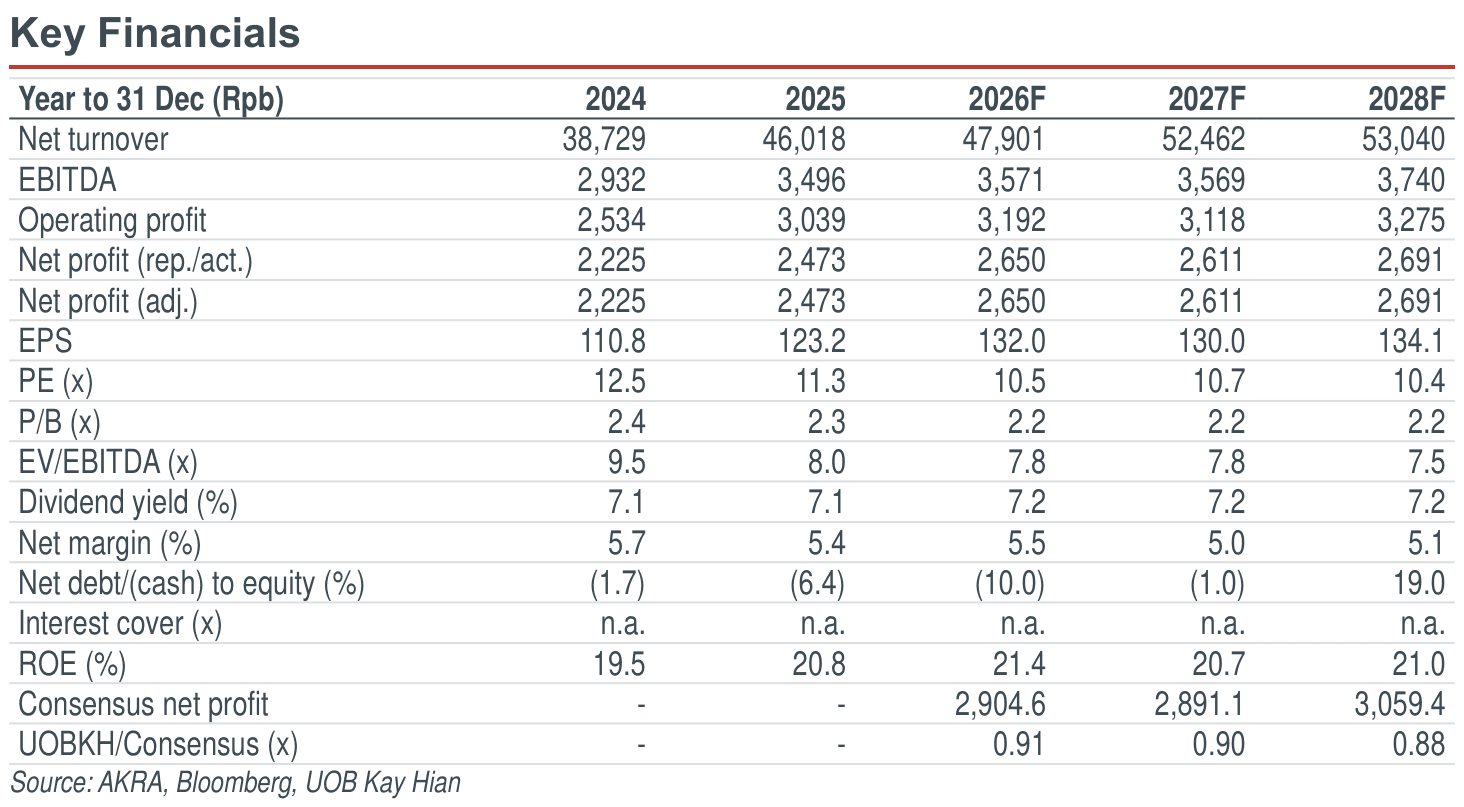
- Maintain BUY with unchanged target price of Rp1,600. Strong 9M26 results suggest earnings upside, although we retain conservative 2027 assumptions. Our BUY call is supported by JIIPE's growth potential, stable T&D business, Rp1.67t net cash and a 7.2% dividend yield.
Analysis
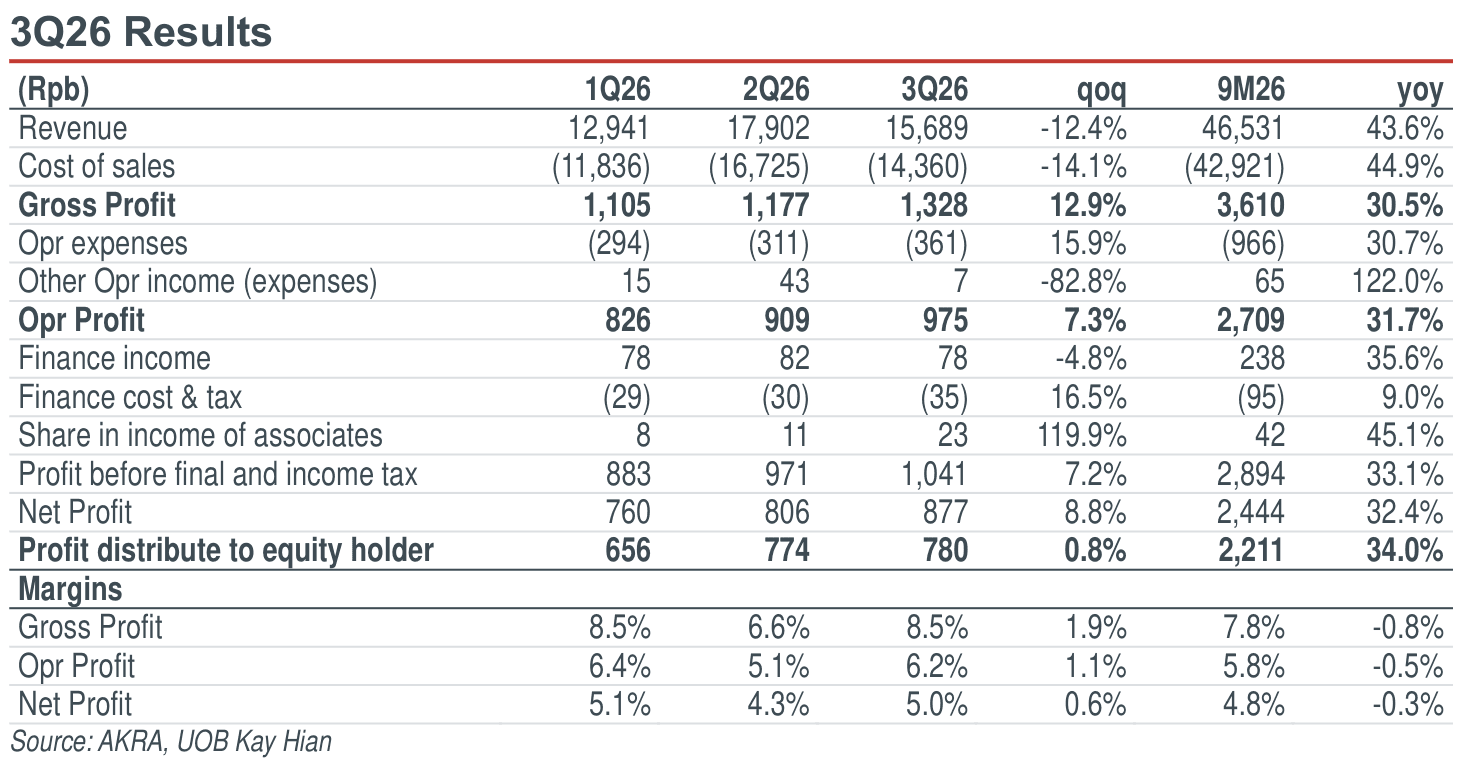
- 3Q26 net profit was flat qoq but 9M26 net profit was up 34% yoy. AKR Corporindo (AKRA) booked net profit of Rp780b, flat qoq but jumping 66% yoy, bringing 9M26 net profit growing 34% yoy to Rp2.2t. 9M26 net profit was above market expectations, accounting for 83% of our full-year estimates while slightly above market’s (77%). At the current rate, AKRA is closer to achieving the upper end of its Rp2.9t net profit guidance for 2026. The strong earnings are supported by: a) strong trading and distribution business momentum, b) 93ha of land sales (1H26: 58ha), and c) rising utilities income.
Highlights
- 9M26 earnings ahead of expectations. Net profit rose 34% yoy to Rp2.2t, reaching 83% of our 2026 forecast and 77% of consensus. T&D gross margin recovered to 6.9% in 3Q26 from 4.6% in 2Q26, supporting earnings despite lower sequential revenue.
- JIIPE land sales on target; utilities gaining momentum. Land sales reached 93ha in 9M26, meeting management's 90-100ha 2026 target range. Utilities revenue grew 46.6% qoq to Rp305b in 3Q26, bringing 9M26 revenue to 73% of the 2026 target.
- Maintain BUY with unchanged target price of Rp1,600. Strong 9M26 results suggest earnings upside, although we retain conservative 2027 assumptions. Our BUY call is supported by JIIPE's growth potential, stable T&D business, Rp1.67t net cash and a 7.2% dividend yield.
Analysis
- 3Q26 net profit was flat qoq but 9M26 net profit was up 34% yoy. AKR Corporindo (AKRA) booked net profit of Rp780b, flat qoq but jumping 66% yoy, bringing 9M26 net profit growing 34% yoy to Rp2.2t. 9M26 net profit was above market expectations, accounting for 83% of our full-year estimates while slightly above market’s (77%). At the current rate, AKRA is closer to achieving the upper end of its Rp2.9t net profit guidance for 2026. The strong earnings are supported by: a) strong trading and distribution business momentum, b) 93ha of land sales (1H26: 58ha), and c) rising utilities income.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,390
Rp1,600
+15.1%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


