Company Coverage
Darma Henwa (DEWA IJ): Ramping Up For 2027 Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp256
Rp780
+205%
Rp1,260
Analyst
Analyst
Highlights
- DEWA’s operations are gaining traction, with 3Q26 margins improving following the Bengalon takeover and full in-house operations.
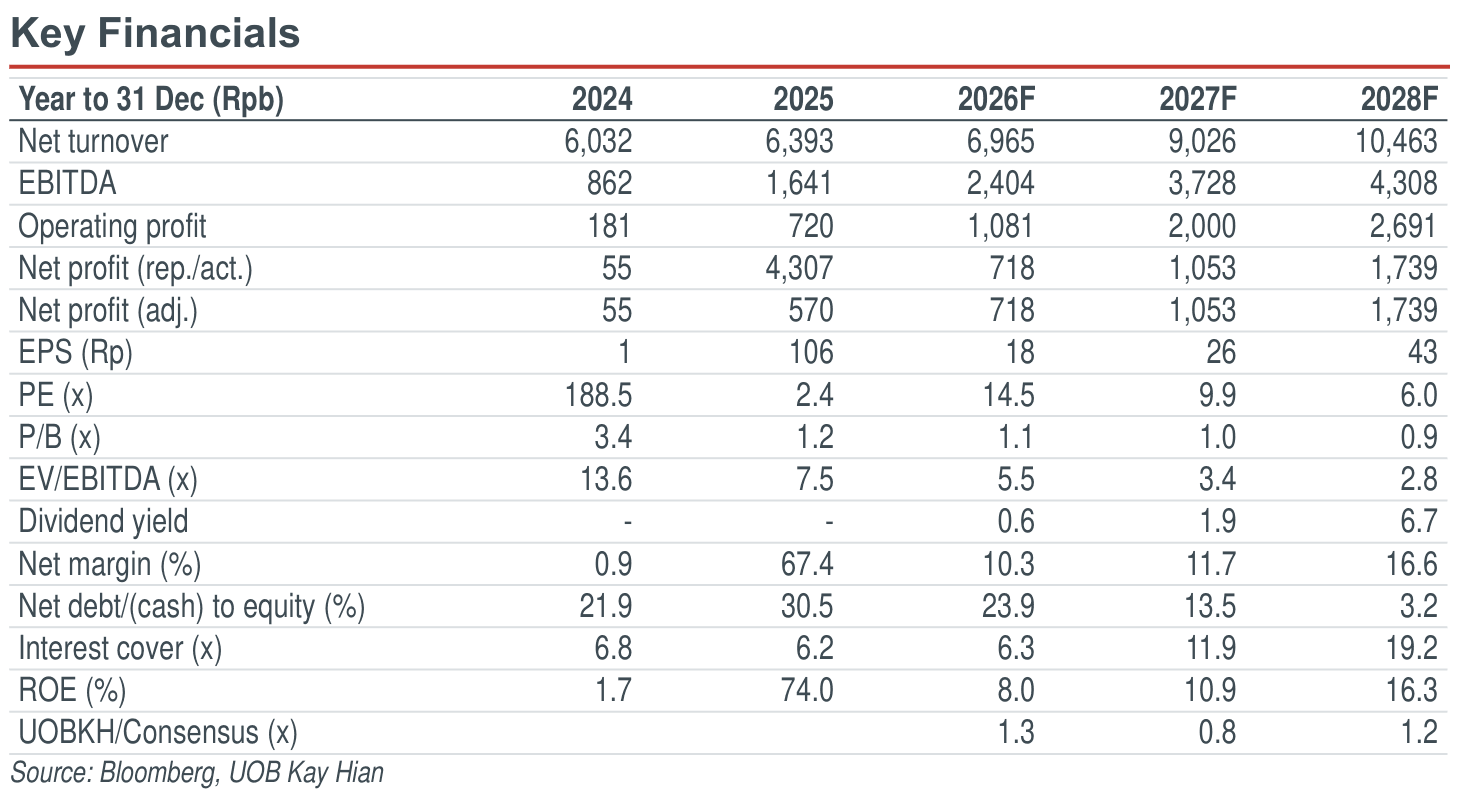
- Volume to reach 200m BCM. SSC is ramping up, while potential South Sumatra and Halmahera contract wins could lift 2027 OB volume toward 200m BCM and drive core profit growth of 101.4% yoy.
- We maintain BUY with a lower target price of Rp780, reflecting higher WACC and more conservative earnings assumptions. Unpriced copper exposure offers further upside, although financing costs and execution risks remain.
Analysis
- Full utilisation of in-house in 3Q26. 3Q26 marked Darma Henwa’s (DEWA) first full quarter of 100% in-house operations following the Bengalon takeover in May 26, lifting gross, operating and EBITDA margins to 22.3%, 16.0% and 33.0%, respectively, supported by lower rainfall and better fuel efficiency. 9M26 net profit rose 114.5% yoy to Rp513b, including a Rp229b fair value gain in 2Q26, while EBITDA grew 30.7% to Rp1.56t on 10% revenue growth. 3Q26 net profit was Rp159b (+49% qoq core profit growth). We expect 4Q26 performance to remain solid, supported by SSC and full in-house operations, despite potential seasonal rainfall.
- Scaling up operations and expanding beyond BUMI. Sebuku Sejaka Coal (SSC), DEWA’s first major external contract, is ramping up following its US$1.3b five-year contract signed in Jun 26, with first coal delivered in Oct 26. DEWA targets 0.8-0.9mt of coal and 8m-10m BCM of overburden removal (OB) in 2026. This could potentially rise to 3mt of coal (subject to mining quota award) and 30m-35m BCM of OB in 2027. At full capacity, SSC could generate about Rp4t in annual revenue, add 55m BCM of annual OB volume, and command rates around 30% above DEWA’s typical levels.
- Contract wins could lift 2027 volume. Meanwhile, DEWA is in the final bidding round for four South Sumatra packages worth about Rp17t combined, with awards expected in Nov-Dec 26. Winning one or two packages could add around 30m BCM of OB, bringing 2027 volume to about 200m BCM alongside SSC. Additional upside could come from expanded KPC scope and a potential 72m BCM nickel mining contract in Halmahera Timur starting in 1Q27, subject to RKAB approval. Over the longer term, DEWA continues to pursue additional opportunities at KPC, supported by its newer, more fuel-efficient fleet with additional 150m bcm of potential volume.
Highlights
- DEWA’s operations are gaining traction, with 3Q26 margins improving following the Bengalon takeover and full in-house operations.
- Volume to reach 200m BCM. SSC is ramping up, while potential South Sumatra and Halmahera contract wins could lift 2027 OB volume toward 200m BCM and drive core profit growth of 101.4% yoy.
- We maintain BUY with a lower target price of Rp780, reflecting higher WACC and more conservative earnings assumptions. Unpriced copper exposure offers further upside, although financing costs and execution risks remain.
Analysis
- Full utilisation of in-house in 3Q26. 3Q26 marked Darma Henwa’s (DEWA) first full quarter of 100% in-house operations following the Bengalon takeover in May 26, lifting gross, operating and EBITDA margins to 22.3%, 16.0% and 33.0%, respectively, supported by lower rainfall and better fuel efficiency. 9M26 net profit rose 114.5% yoy to Rp513b, including a Rp229b fair value gain in 2Q26, while EBITDA grew 30.7% to Rp1.56t on 10% revenue growth. 3Q26 net profit was Rp159b (+49% qoq core profit growth). We expect 4Q26 performance to remain solid, supported by SSC and full in-house operations, despite potential seasonal rainfall.
- Scaling up operations and expanding beyond BUMI. Sebuku Sejaka Coal (SSC), DEWA’s first major external contract, is ramping up following its US$1.3b five-year contract signed in Jun 26, with first coal delivered in Oct 26. DEWA targets 0.8-0.9mt of coal and 8m-10m BCM of overburden removal (OB) in 2026. This could potentially rise to 3mt of coal (subject to mining quota award) and 30m-35m BCM of OB in 2027. At full capacity, SSC could generate about Rp4t in annual revenue, add 55m BCM of annual OB volume, and command rates around 30% above DEWA’s typical levels.
- Contract wins could lift 2027 volume. Meanwhile, DEWA is in the final bidding round for four South Sumatra packages worth about Rp17t combined, with awards expected in Nov-Dec 26. Winning one or two packages could add around 30m BCM of OB, bringing 2027 volume to about 200m BCM alongside SSC. Additional upside could come from expanded KPC scope and a potential 72m BCM nickel mining contract in Halmahera Timur starting in 1Q27, subject to RKAB approval. Over the longer term, DEWA continues to pursue additional opportunities at KPC, supported by its newer, more fuel-efficient fleet with additional 150m bcm of potential volume.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp256
Rp780
+205%
Rp1,260
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


