Company Coverage
Unilever Indonesia (UNVR IJ): Volumes Hold Up; Margins Under Pressure
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
Rp1,395
Rp1,800
+29.0%
Rp2,500
Analyst
Analyst
Highlights
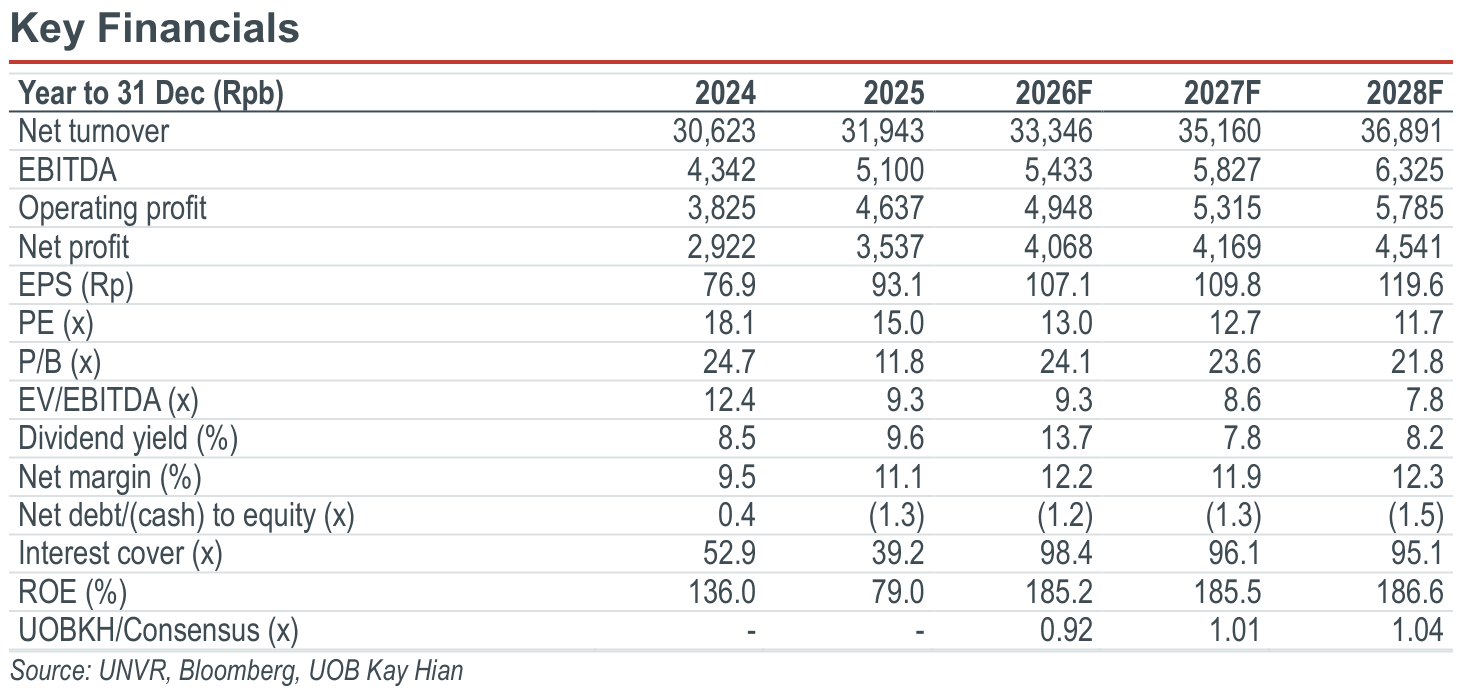
- 3Q26 net profit from continuing operations rose 11.1% yoy, helped by higher interest income and asset disposal gain. However, operating profit slipped 4.4% yoy despite a solid 7.4% revenue growth, as gross margin was squeezed.
- Expect a dividend yield of around 9% over the next 12 months, including an interim DPS of about Rp76 in Dec 26 from 9M26 profit and the Sariwangi gain.
- Upgrade to BUY with a lower target price of Rp1,800 (from Rp2,500), based on 16.4x 2027F PE (-0.5SD). The stock has fallen around 46% ytd.
Analysis
- 9M26 results: Volume-led top-line, margins squeezed. Unilever Indonesia’s (UNVR) 3Q26 revenue from continuing operations rose 7.4% yoy to Rp8.9t (9M26: +7.2% to Rp25.8t). Growth was almost entirely volume, with price adding only 0.9%. Home & personal care (HPC; 74% of sales) was fully volume-driven (3Q26 volume +8.6%). Foods & refreshment growth was driven entirely by pricing (+3.9%), with volume flat (+0.2%). Gross margin fell to 42.3% in 3Q26 from 45.0% in 2Q26 (2025: 46.9%) on higher oil and CPO costs and a weaker rupiah, with limited cost pass-through through pricing. Lower Advertising & Promotion (A&P) cut SG&A to 26.6% of sales (3Q25: 32.3%), but operating profit still slipped 4.4% yoy to Rp1.4t. Nevertheless, net profit rose 11.1% yoy to Rp1.2t (9M26: +10.6% to Rp3.3t), lifted by interest income (9M26: Rp100b vs 9M25’s Rp6b) and a Rp104b asset disposal gain (81% of ours and 75% of cons), while 9M26 core profit was flat at Rp3.2t (+0.8% yoy).
- Strategy focuses on volume, with cost control protecting margins. UNVR is driving growth through premiumisation, online channels and its power brands (Pepsodent, Sunsilk, Rinso, Bango, Royco, etc). Rinso and Sunsilk gained 70bp and 30bp of market share respectively over the last 12 months to Aug 26. Premium products are growing 1.9x faster than mainstream products. Management did not call a bottom in gross margin given volatile oil prices, and expects pricing to stay selective amid weak purchasing power. Instead, it is leaning on controllable costs, moving A&P to priority categories (beauty +15%, with foods and home care trimmed) and making surfactants in-house, which has cut production cost per tonne by about 25% since 2024.
Highlights
- 3Q26 net profit from continuing operations rose 11.1% yoy, helped by higher interest income and asset disposal gain. However, operating profit slipped 4.4% yoy despite a solid 7.4% revenue growth, as gross margin was squeezed.
- Expect a dividend yield of around 9% over the next 12 months, including an interim DPS of about Rp76 in Dec 26 from 9M26 profit and the Sariwangi gain.
- Upgrade to BUY with a lower target price of Rp1,800 (from Rp2,500), based on 16.4x 2027F PE (-0.5SD). The stock has fallen around 46% ytd.
Analysis
- 9M26 results: Volume-led top-line, margins squeezed. Unilever Indonesia’s (UNVR) 3Q26 revenue from continuing operations rose 7.4% yoy to Rp8.9t (9M26: +7.2% to Rp25.8t). Growth was almost entirely volume, with price adding only 0.9%. Home & personal care (HPC; 74% of sales) was fully volume-driven (3Q26 volume +8.6%). Foods & refreshment growth was driven entirely by pricing (+3.9%), with volume flat (+0.2%). Gross margin fell to 42.3% in 3Q26 from 45.0% in 2Q26 (2025: 46.9%) on higher oil and CPO costs and a weaker rupiah, with limited cost pass-through through pricing. Lower Advertising & Promotion (A&P) cut SG&A to 26.6% of sales (3Q25: 32.3%), but operating profit still slipped 4.4% yoy to Rp1.4t. Nevertheless, net profit rose 11.1% yoy to Rp1.2t (9M26: +10.6% to Rp3.3t), lifted by interest income (9M26: Rp100b vs 9M25’s Rp6b) and a Rp104b asset disposal gain (81% of ours and 75% of cons), while 9M26 core profit was flat at Rp3.2t (+0.8% yoy).
- Strategy focuses on volume, with cost control protecting margins. UNVR is driving growth through premiumisation, online channels and its power brands (Pepsodent, Sunsilk, Rinso, Bango, Royco, etc). Rinso and Sunsilk gained 70bp and 30bp of market share respectively over the last 12 months to Aug 26. Premium products are growing 1.9x faster than mainstream products. Management did not call a bottom in gross margin given volatile oil prices, and expects pricing to stay selective amid weak purchasing power. Instead, it is leaning on controllable costs, moving A&P to priority categories (beauty +15%, with foods and home care trimmed) and making surfactants in-house, which has cut production cost per tonne by about 25% since 2024.
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
Rp1,395
Rp1,800
+29.0%
Rp2,500
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


