Company Coverage
Medikaloka Hermina (HEAL IJ): 3Q26: Sequential Improvement, But Earnings And Valuation Remain Under Pressure
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp515
Rp785
+52.4%
Rp1,120
Analyst
Highlights
- 3Q26 earnings broadly in line; sequential recovery continues, but PATMI remains weak yoy.
- Non-BPJS growth supports revenue, while soft patient demand and BPJS dependence constrain earnings visibility.
- Maintain BUY with a lower target price of Rp785, implying 6.5x 2027 EV/EBITDA as higher sovereign yields and MSCI uncertainty lead to a lower valuation multiple.
Analysis
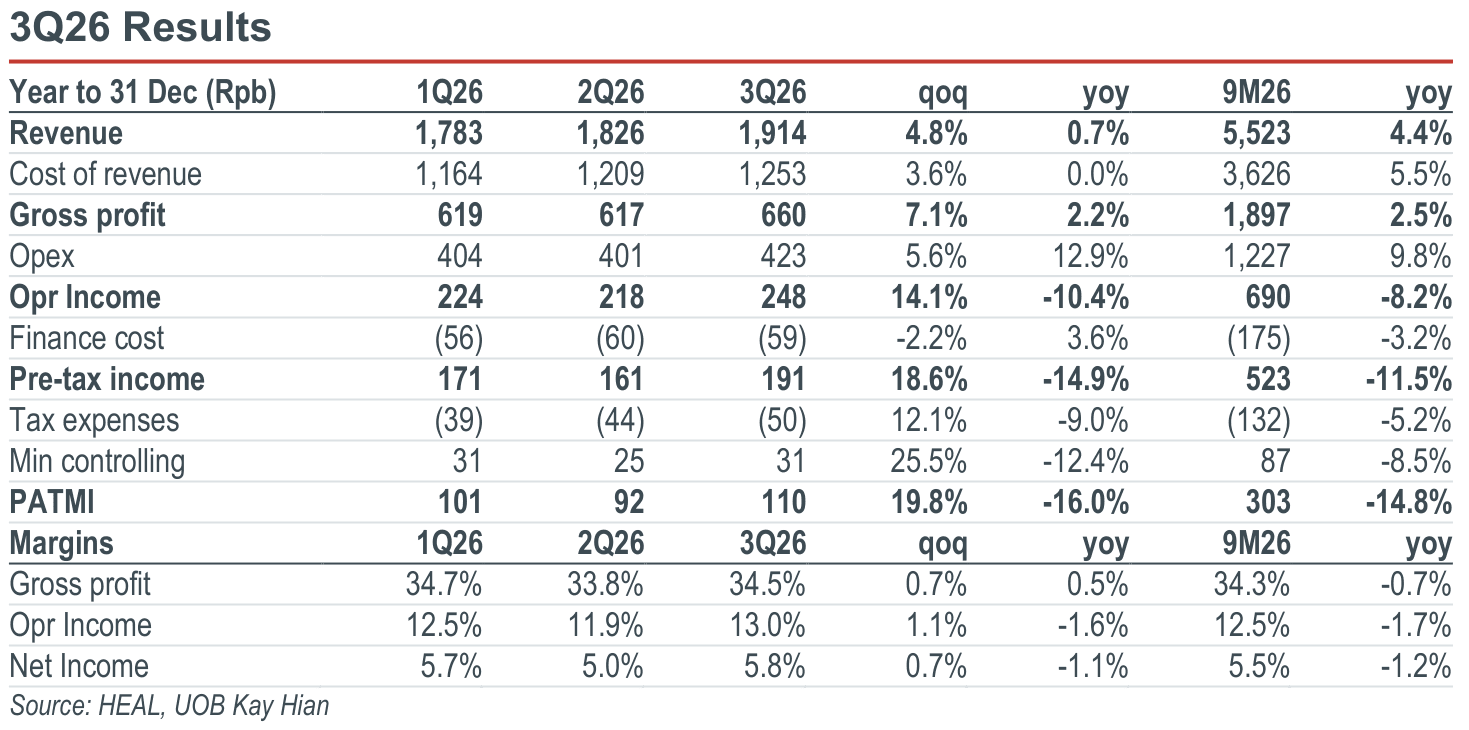
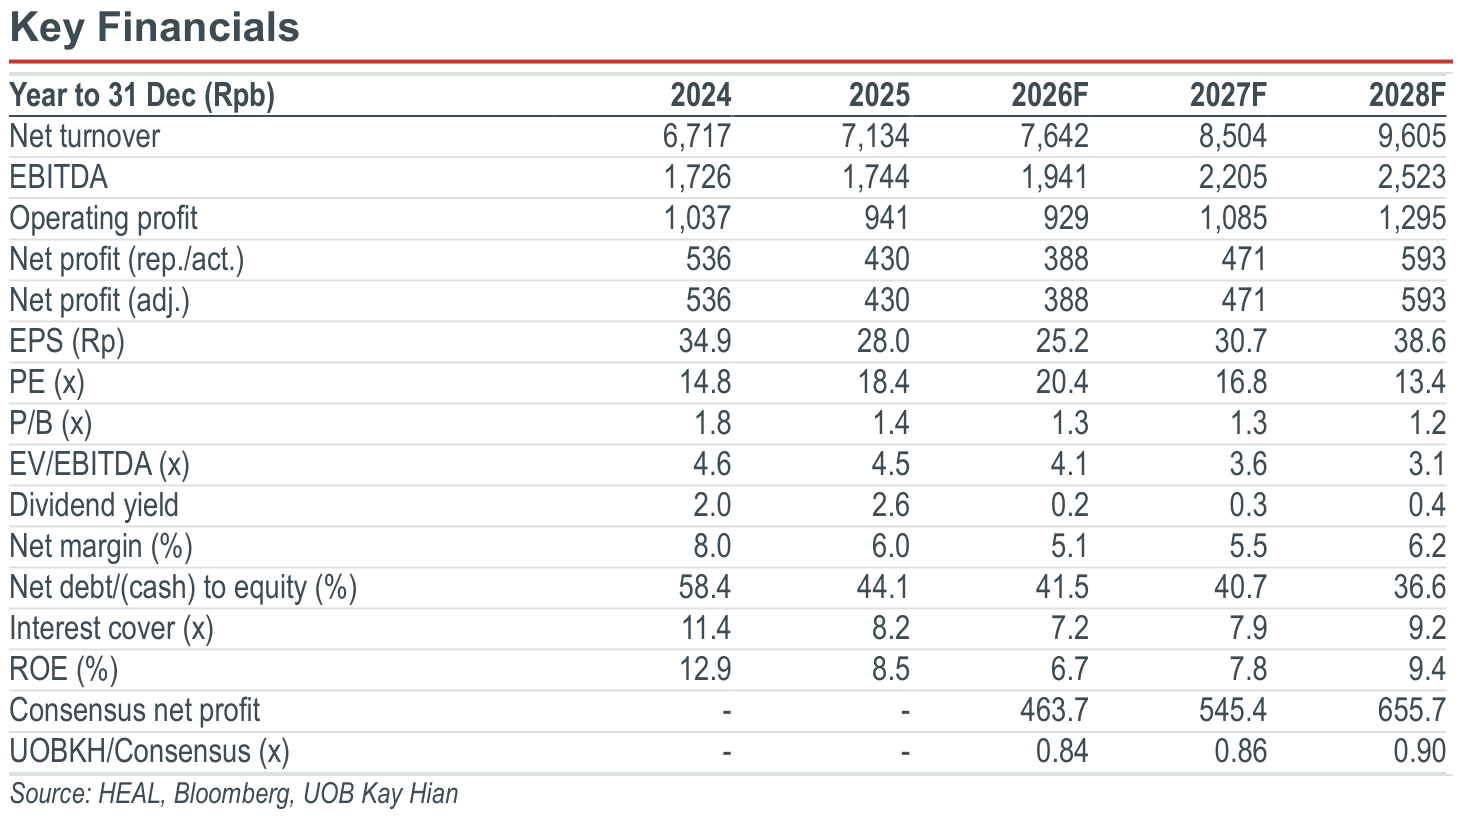
- 3Q26 earnings improved sequentially but remained weak yoy. Medikaloka Hermina (HEAL) posted a 3Q26 revenue of Rp1.91t (+0.8% yoy, +4.8% qoq) and EBITDA of Rp530b (+1.9% yoy, +10.6% qoq), with EBITDA margin improving to 27.7% from 26.2% in 2Q26. The improvement was supported by higher medicine margins (32.4% vs. 31.1% in 2Q26) and lower employee costs relative to revenue. However, 3Q26 PATMI declined 16.6% yoy to Rp110b (+19.6% qoq), weighed down by higher depreciation following previous capacity expansion. Depreciation increased to 13.4% of revenue from 12.0% in 3Q25. 9M26 net profit is in line with our expectation, but below consensus’, accounting for 78%/64% of our/market 2026 estimates.
Highlights
- 3Q26 earnings broadly in line; sequential recovery continues, but PATMI remains weak yoy.
- Non-BPJS growth supports revenue, while soft patient demand and BPJS dependence constrain earnings visibility.
- Maintain BUY with a lower target price of Rp785, implying 6.5x 2027 EV/EBITDA as higher sovereign yields and MSCI uncertainty lead to a lower valuation multiple.
Analysis
- 3Q26 earnings improved sequentially but remained weak yoy. Medikaloka Hermina (HEAL) posted a 3Q26 revenue of Rp1.91t (+0.8% yoy, +4.8% qoq) and EBITDA of Rp530b (+1.9% yoy, +10.6% qoq), with EBITDA margin improving to 27.7% from 26.2% in 2Q26. The improvement was supported by higher medicine margins (32.4% vs. 31.1% in 2Q26) and lower employee costs relative to revenue. However, 3Q26 PATMI declined 16.6% yoy to Rp110b (+19.6% qoq), weighed down by higher depreciation following previous capacity expansion. Depreciation increased to 13.4% of revenue from 12.0% in 3Q25. 9M26 net profit is in line with our expectation, but below consensus’, accounting for 78%/64% of our/market 2026 estimates.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp515
Rp785
+52.4%
Rp1,120
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


