Company Coverage
Indo Tambangraya Megah (ITMG IJ): 3Q26: Higher ASP And Continued Buyback Incentive
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp24,150
Rp25,800
+6.8%
Rp24,000
Analyst
Analyst
Highlights
- Higher ASP drives 3Q26 earnings. ITMG booked 3Q26 net profit of US$56.9m (+43.7% yoy; +10.9% qoq) and 9M26 net profit rose 24.8% yoy to US$162.9m, reaching 68% of our 2026F estimate (77% excluding the US$19.2m impairment).
- Dividend and buyback support shareholder returns. ITMG's interim dividend offers a 4.8% yield and the company launched a Rp2.31t buyback programme for Nov 26-Feb 27.
- Maintain HOLD with a a higher target price of Rp25,800 from Rp24,000.
Analysis
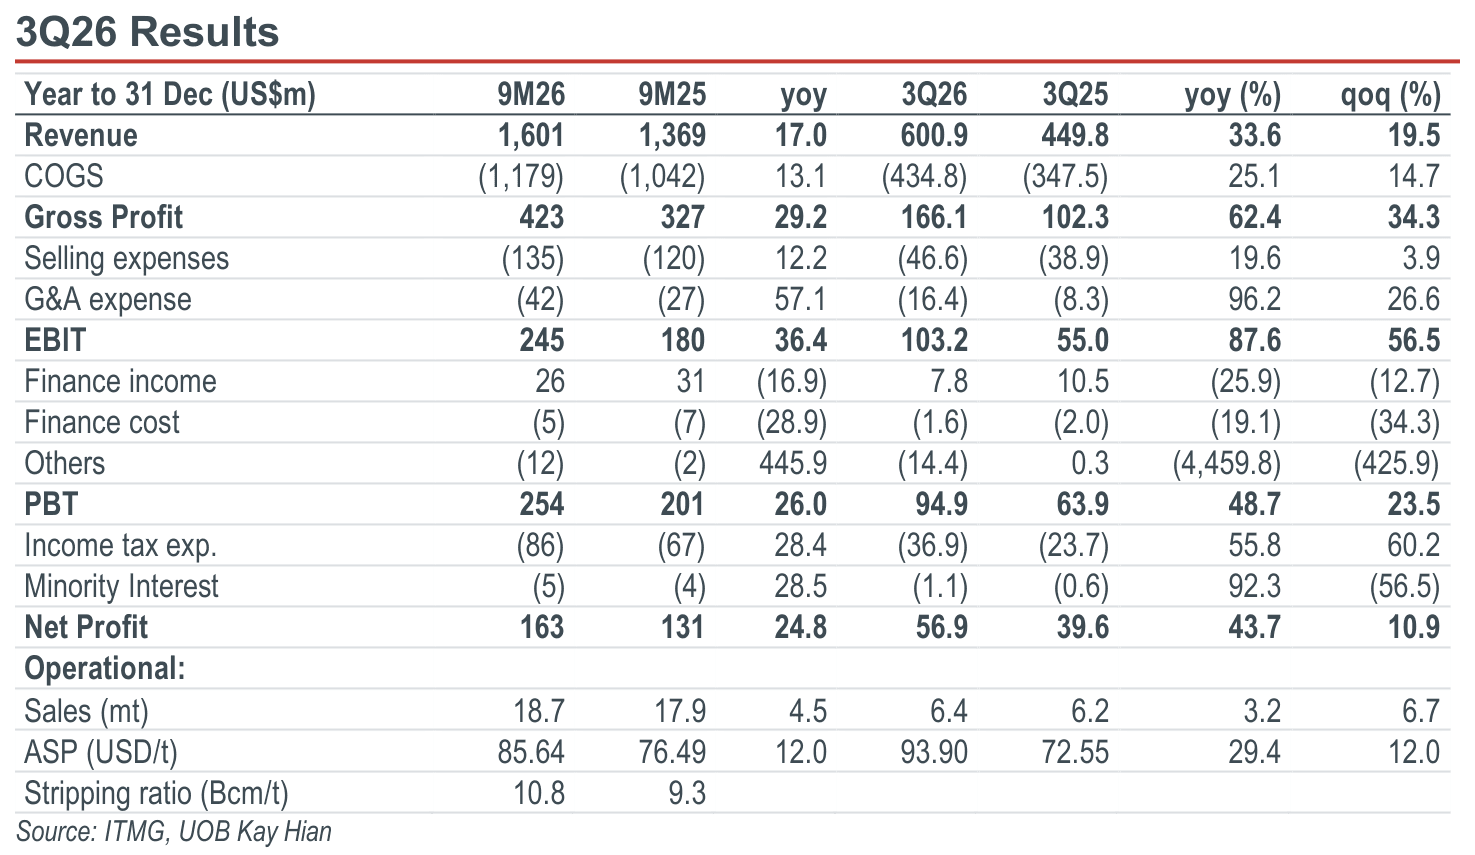
- Higher ASP drives stronger 3Q26 results. Indo Tambangraya Megah (ITMG) recorded 3Q26 net profit of US$56.9m (+43.7% yoy; +10.9% qoq), supported by higher coal prices and sales volume. Revenue increased 19.5% qoq to US$600.9m, driven by a 12.0% increase in ASP to US$93.9/t and 6.7% higher sales volume to 6.4mt. However, net profit growth was partly offset by a US$19.2m impairment of property, plant and equipment and a higher effective tax rate of 38.9%. Consequently, 9M26 net profit rose 24.8% yoy to US$162.9m, on 17.0% revenue growth to US$1.6b and 36.4% operating profit growth to US$245.4m. Against our 2026F estimate of US$237m, 9M26 earnings achieved 68%, below our forecast, although adjusted earnings excluding the one-off impairment would have reached US$182m, or 77% of 2026F estimates.
Highlights
- Higher ASP drives 3Q26 earnings. ITMG booked 3Q26 net profit of US$56.9m (+43.7% yoy; +10.9% qoq) and 9M26 net profit rose 24.8% yoy to US$162.9m, reaching 68% of our 2026F estimate (77% excluding the US$19.2m impairment).
- Dividend and buyback support shareholder returns. ITMG's interim dividend offers a 4.8% yield and the company launched a Rp2.31t buyback programme for Nov 26-Feb 27.
- Maintain HOLD with a a higher target price of Rp25,800 from Rp24,000.
Analysis
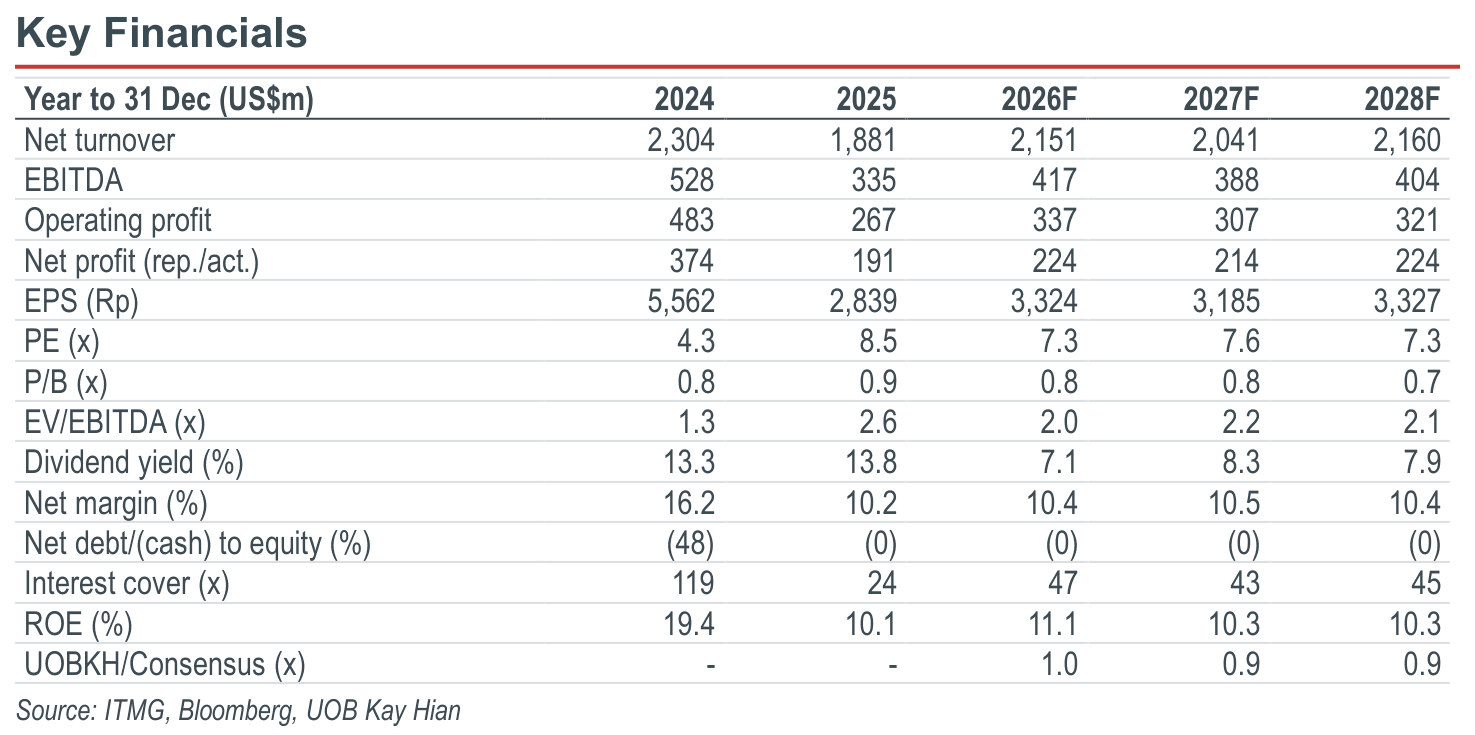
- Higher ASP drives stronger 3Q26 results. Indo Tambangraya Megah (ITMG) recorded 3Q26 net profit of US$56.9m (+43.7% yoy; +10.9% qoq), supported by higher coal prices and sales volume. Revenue increased 19.5% qoq to US$600.9m, driven by a 12.0% increase in ASP to US$93.9/t and 6.7% higher sales volume to 6.4mt. However, net profit growth was partly offset by a US$19.2m impairment of property, plant and equipment and a higher effective tax rate of 38.9%. Consequently, 9M26 net profit rose 24.8% yoy to US$162.9m, on 17.0% revenue growth to US$1.6b and 36.4% operating profit growth to US$245.4m. Against our 2026F estimate of US$237m, 9M26 earnings achieved 68%, below our forecast, although adjusted earnings excluding the one-off impairment would have reached US$182m, or 77% of 2026F estimates.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp24,150
Rp25,800
+6.8%
Rp24,000
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


