Company Coverage
United Tractors (UNTR IJ): Improved 2H26 Outlook On Higher Coal Quotas
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp23,500
Rp30,000
+27.7%
Rp27,500
Analyst
Analyst
Highlights
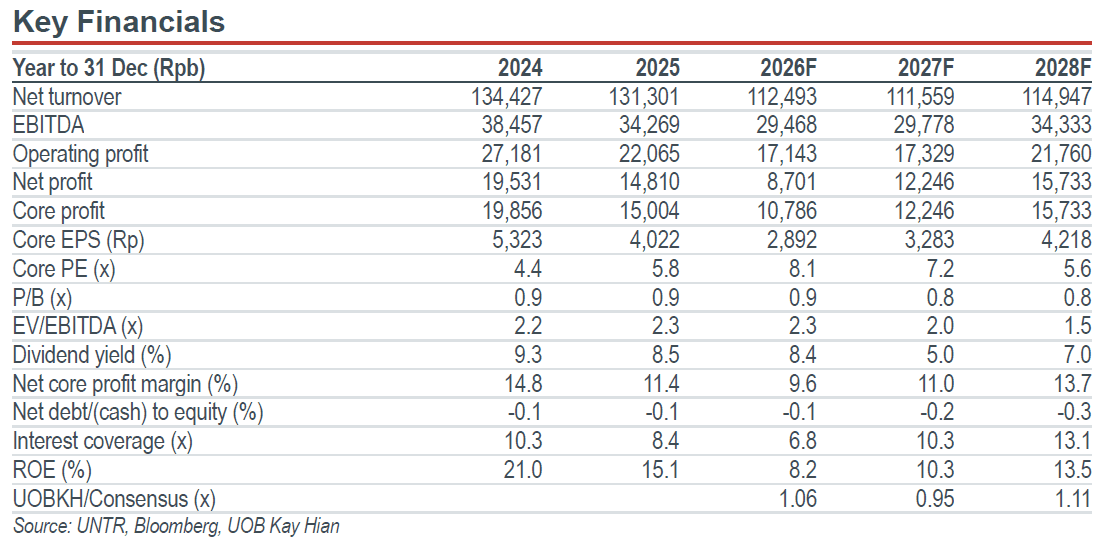
- MSCI exclusion risk likely priced in, while buybacks provide support. UNTR has outperformed the JCI by 20.3% ytd, supported by ongoing share buybacks. Despite the possibility of being excluded from the MSCI during the Nov 26 review, this risk appears largely priced in.
- RKAB uplift and gold volume growth provide long-term catalysts. Higher RKAB quotas provide near-term mining contracting growth, while Martabe's gradual production ramp-up towards its normalised 200,000 oz by 2029 provides a longer-term earnings catalyst.
- Maintain BUY with an SOTP-based target price of Rp30,000.
Analysis
- 2026 guidance raised on higher RKAB allocations and dry-season productivity. The national coal work plan and budget (RKAB) was revised upward in Aug 26 from 600mt to 700mt (+16.7%), although this remains below 2025’s production of 820mt. PAMA's clients have adjusted their production targets in line with the additional quotas. Consequently, 2026 overburden (OB) removal guidance was raised from 950m BCM to 1,025m BCM (+7.9%), while coal production guidance was increased from 135mt to 146mt (+8.0%), bringing the stripping ratio from 7.03x to 7.02x. 4Q26 OB removal is expected to decline slightly qoq as the rainy season begins, but still remain above 2Q26 levels. Tuah Turangga Agung’s (TTA) RKAB was also revised upward from 7.5mt to 12.4mt, with the additional quota granted in Aug 26. However, TTA's coal sales target remains unchanged at 10mt, as deliveries remain dependent on river water levels, with low levels during the dry season having constrained barging activities. Guidance for Komatsu, gold and nickel remains unchanged.
- Expect a recovery in gold volume in 2027. 2026 gold production guidance remains unchanged at 82,000 oz, comprising 65,000 oz from the Martabe gold mine and the remainder from Sumbawa Juta Raya. Following operational disruptions during Jan-May 26, Martabe's production is expected to gradually ramp up towards its normalised level, reaching 80,000-100,000 oz in 2027, 150,000 oz in 2028 and 200,000 oz in 2029. Cash costs, excluding royalties, currently stand at US$2,600/oz at prevailing production levels, but UNTR expects these to roughly halve to US$1,300/oz once production reaches 200,000 oz. The ramp-up in 2027 is contingent on the new tailings facility, with the permit already received in Oct 26, while the filtration plant and dry tailings facility are targeted for completion in 3Q-4Q27. Meanwhile, the Doup gold project carries a total capex of US$400m. Approximately US$20m had been spent as of Sep 26, with US$60m expected to be spent in 2026, primarily on land acquisition and basic infrastructure. Capex is expected to be incurred in 2027-28 for the carbon-in-leach (CIL) processing plant, with operations targeted to commence in 2029.
Highlights
- MSCI exclusion risk likely priced in, while buybacks provide support. UNTR has outperformed the JCI by 20.3% ytd, supported by ongoing share buybacks. Despite the possibility of being excluded from the MSCI during the Nov 26 review, this risk appears largely priced in.
- RKAB uplift and gold volume growth provide long-term catalysts. Higher RKAB quotas provide near-term mining contracting growth, while Martabe's gradual production ramp-up towards its normalised 200,000 oz by 2029 provides a longer-term earnings catalyst.
- Maintain BUY with an SOTP-based target price of Rp30,000.
Analysis
- 2026 guidance raised on higher RKAB allocations and dry-season productivity. The national coal work plan and budget (RKAB) was revised upward in Aug 26 from 600mt to 700mt (+16.7%), although this remains below 2025’s production of 820mt. PAMA's clients have adjusted their production targets in line with the additional quotas. Consequently, 2026 overburden (OB) removal guidance was raised from 950m BCM to 1,025m BCM (+7.9%), while coal production guidance was increased from 135mt to 146mt (+8.0%), bringing the stripping ratio from 7.03x to 7.02x. 4Q26 OB removal is expected to decline slightly qoq as the rainy season begins, but still remain above 2Q26 levels. Tuah Turangga Agung’s (TTA) RKAB was also revised upward from 7.5mt to 12.4mt, with the additional quota granted in Aug 26. However, TTA's coal sales target remains unchanged at 10mt, as deliveries remain dependent on river water levels, with low levels during the dry season having constrained barging activities. Guidance for Komatsu, gold and nickel remains unchanged.
- Expect a recovery in gold volume in 2027. 2026 gold production guidance remains unchanged at 82,000 oz, comprising 65,000 oz from the Martabe gold mine and the remainder from Sumbawa Juta Raya. Following operational disruptions during Jan-May 26, Martabe's production is expected to gradually ramp up towards its normalised level, reaching 80,000-100,000 oz in 2027, 150,000 oz in 2028 and 200,000 oz in 2029. Cash costs, excluding royalties, currently stand at US$2,600/oz at prevailing production levels, but UNTR expects these to roughly halve to US$1,300/oz once production reaches 200,000 oz. The ramp-up in 2027 is contingent on the new tailings facility, with the permit already received in Oct 26, while the filtration plant and dry tailings facility are targeted for completion in 3Q-4Q27. Meanwhile, the Doup gold project carries a total capex of US$400m. Approximately US$20m had been spent as of Sep 26, with US$60m expected to be spent in 2026, primarily on land acquisition and basic infrastructure. Capex is expected to be incurred in 2027-28 for the carbon-in-leach (CIL) processing plant, with operations targeted to commence in 2029.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp23,500
Rp30,000
+27.7%
Rp27,500
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
Adaro Andalan Indonesia (AADI IJ) - Two Tailwinds: Coal Prices And Special Dividend

4 Nov 2026
Telkom Indonesia (TLKM IJ) - 3Q26: Recovery Ahead, With TIF Monetisation As A Key Catalyst

12 Oct 2026
Sarana Menara Nusantara (TOWR IJ): 5G Densification And Potential DC Rollouts Offer Upside
Our latest research
5 Nov 2026
Adaro Andalan Indonesia (AADI IJ) - Two Tailwinds: Coal Prices And Special Dividend
4 Nov 2026
Telkom Indonesia (TLKM IJ) - 3Q26: Recovery Ahead, With TIF Monetisation As A Key Catalyst

2 Nov 2026