Company Coverage
Energi Mega Persada (ENRG IJ): Funding The Growth Runway
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,085
Rp1,870
+72.3%
Analyst
Analyst
Highlights
- HPK diversifies ENRG into oil. The US$200m investment provides exposure to oil-weighted Permian production, while HPK’s refinancing could strengthen its balance sheet and create potential equity upside for ENRG.
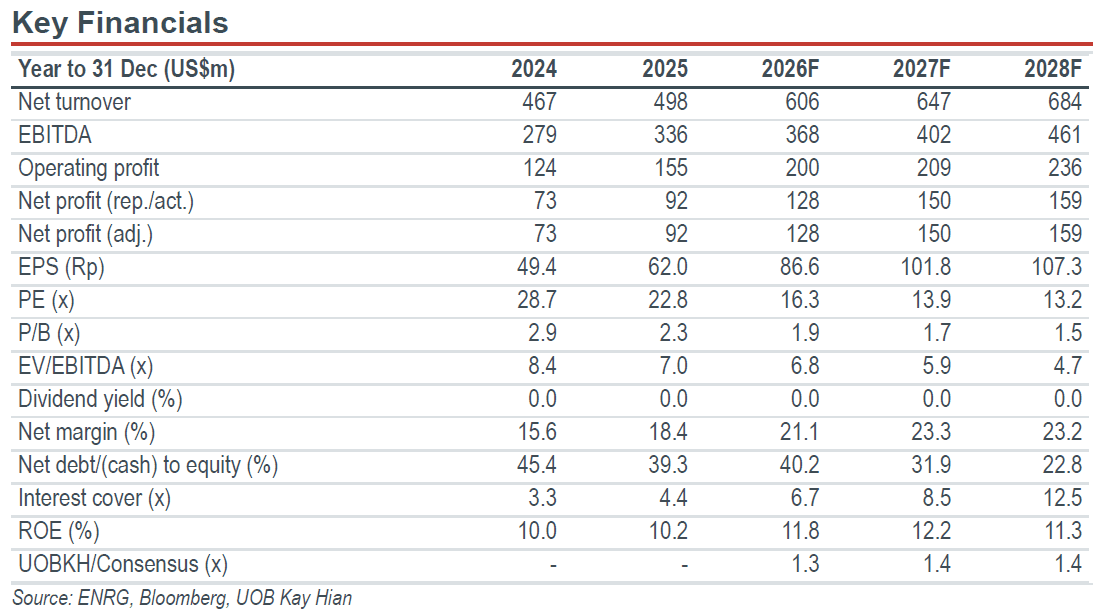
- Maintain BUY with target price of Rp1,870. While the US$200m HPK investment is potentially dilutive to our current valuation, we anticipate potential upside from HPK and future developments, which we have yet to quantify. Meanwhile, the Rp4.12t rights issue will support ENRG’s strategic initiatives to grow group production. The near-term catalyst is Gebang, which is expected to start production in 1H27 at up to 40 mmcfd.
Analysis
- ENRG is raising capital through PMHMETD IV (rights issue) by issuing up to 13.5b of new Series B shares. Energi Mega Persada (ENRG) is raising Rp4.12t or US$230m through PMHMETD IV (rights issue), issuing 13.28b of new shares at Rp310 on a 2:1 ratio, increasing its total issued shares to 39.85b. The rights trade can be done during 8-21 October. Bakrie affiliates are standby buyers, for up to 9.92b shares. The proceeds of the rights issue will fund drilling, gas infrastructure, facility upgrades, enhanced oil recovery (EOR), and working capital across ENRG's subsidiaries.|
- Acquiring shale block company in the US. ENRG and Danantara have committed to a US$450m preferred equity investment in Nasdaq-listed HighPeak Energy (HPK), with ENRG contributing US$200m for a 12% stake and Danantara US$250m for a 15% stake. The instrument is a perpetual Series A convertible preferred with a 6% coupon, paying cumulative cash dividends quarterly, and convertible at a price of US$9.50/share. The US$450m proceeds, US$800m reserve-based lending (RBL) facility from Citibank and Fifth Third, and available cash will fully repay HPK's existing US$1.17b term loan. The US$9.50/share conversion price implies a pre-money equity value of US$1.2b for HPK (126.45m shares outstanding), and is a 20% premium to its current market cap of US$1.0b. Including the US$450m new capital, the post-money, as-converted equity value is US$1.65b. HPK's 2026 annualised core profit is US$71.5m which excludes interest income, other income, and derivative gains/losses. This implies a PE of 16.8x based on the transaction price, compared with 14.0x at the current market capitalisation. Following the refinancing, we estimate that US$40m of after-tax financing savings would lift pro forma core profit to US$111m, reducing the implied PE to 9.0x.
Highlights
- HPK diversifies ENRG into oil. The US$200m investment provides exposure to oil-weighted Permian production, while HPK’s refinancing could strengthen its balance sheet and create potential equity upside for ENRG.
- Maintain BUY with target price of Rp1,870. While the US$200m HPK investment is potentially dilutive to our current valuation, we anticipate potential upside from HPK and future developments, which we have yet to quantify. Meanwhile, the Rp4.12t rights issue will support ENRG’s strategic initiatives to grow group production. The near-term catalyst is Gebang, which is expected to start production in 1H27 at up to 40 mmcfd.
Analysis
- ENRG is raising capital through PMHMETD IV (rights issue) by issuing up to 13.5b of new Series B shares. Energi Mega Persada (ENRG) is raising Rp4.12t or US$230m through PMHMETD IV (rights issue), issuing 13.28b of new shares at Rp310 on a 2:1 ratio, increasing its total issued shares to 39.85b. The rights trade can be done during 8-21 October. Bakrie affiliates are standby buyers, for up to 9.92b shares. The proceeds of the rights issue will fund drilling, gas infrastructure, facility upgrades, enhanced oil recovery (EOR), and working capital across ENRG's subsidiaries.|
- Acquiring shale block company in the US. ENRG and Danantara have committed to a US$450m preferred equity investment in Nasdaq-listed HighPeak Energy (HPK), with ENRG contributing US$200m for a 12% stake and Danantara US$250m for a 15% stake. The instrument is a perpetual Series A convertible preferred with a 6% coupon, paying cumulative cash dividends quarterly, and convertible at a price of US$9.50/share. The US$450m proceeds, US$800m reserve-based lending (RBL) facility from Citibank and Fifth Third, and available cash will fully repay HPK's existing US$1.17b term loan. The US$9.50/share conversion price implies a pre-money equity value of US$1.2b for HPK (126.45m shares outstanding), and is a 20% premium to its current market cap of US$1.0b. Including the US$450m new capital, the post-money, as-converted equity value is US$1.65b. HPK's 2026 annualised core profit is US$71.5m which excludes interest income, other income, and derivative gains/losses. This implies a PE of 16.8x based on the transaction price, compared with 14.0x at the current market capitalisation. Following the refinancing, we estimate that US$40m of after-tax financing savings would lift pro forma core profit to US$111m, reducing the implied PE to 9.0x.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp1,085
Rp1,870
+72.3%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


