Company Coverage
Japfa Comfeed Indonesia (JPFA IJ): Site Visit Takeaways, Further Scaling Up Downstream
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp2,000
Rp2,900
+45.0%
Rp3,330
Analyst
Analyst
Highlights
- Our visit to JPFA's Cikupa complex showed a well-run site at full utilisation, supporting its strategy to move further downstream.
- With downstream utilisation at around 70%, JPFA is adding plants in Boyolali and Wonoayu and a mega slaughterhouse in Nganjuk (~4x Cikupa) by end-26, with land secured in Sragen for its next project.
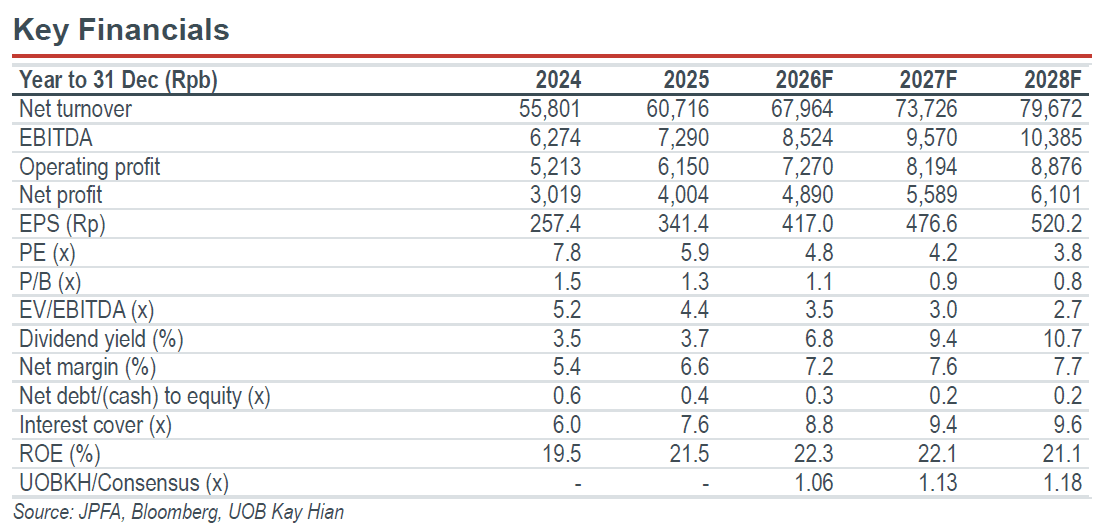
- We expect 3Q26 profit to improve qoq as poultry prices recover. Maintain BUY with a lower target price of Rp2,900, based on 7x 2026F PE.
Analysis
- We had a site visit to JPFA's consumer products integrated complex (So Good Food Manufacturing) in Cikupa, the largest of its three downstream sites at 8ha (Boyolali and Wonoayu are ~4ha each). The site houses a chicken slaughterhouse (~3,000 birds/hour) and a frozen food plant with seven production lines producing 2,000-3,000 tonnes a month. It is fully integrated, with live birds sourced from Japfa Comfeed Indonesia’s (JPFA) own farm and slaughterhouse with around 90% of the output going into downstream processing (the rest is sold to B2B customers). Operations are highly automated, halal compliant and biomass-powered. The facility is already at full utilisation, with management expecting the current capacity to be insufficient within a year, supporting continued downstream expansion.
- Downstream holding up well. Despite a subdued FMCG market, the company remained positive, as its poultry processing and consumer products business still grew strongly at 29% yoy in 1H26 (17% to total revenue). JPFA sees significant room to grow its processed chicken business and plans to increase downstream processing from around 15% of chicken output currently to 40% by 2030, which we view positively as it should reduce margin and earnings volatility. Its processed meat brand, So Good, ranks in the top three alongside Kanzler (Cisarua Mountain Dairy) and Fiesta (Charoen Pokphand (CPIN)), while So Good is no.1 in frozen food in the Modern Trade channel. The company suggested it is continuing to gain share, while new product launches are accelerating, with around 10 new products this year and plans to double this to around 20 in 2027.
- Stepping up expansion. Capex is ramping up, with Rp3t planned for 2026 (Rp2.2t spent in 1H26), nearly matching 2025's Rp2.4t. With downstream utilisation at around 70%, JPFA is expanding processing capacity through new plants in Boyolali and Wonoayu, alongside a mega slaughterhouse in Nganjuk. The facility will process about 12,000 birds/hour, approximately 4x Cikupa's capacity, and is expected to start operations by end-26.
Highlights
- Our visit to JPFA's Cikupa complex showed a well-run site at full utilisation, supporting its strategy to move further downstream.
- With downstream utilisation at around 70%, JPFA is adding plants in Boyolali and Wonoayu and a mega slaughterhouse in Nganjuk (~4x Cikupa) by end-26, with land secured in Sragen for its next project.
- We expect 3Q26 profit to improve qoq as poultry prices recover. Maintain BUY with a lower target price of Rp2,900, based on 7x 2026F PE.
Analysis
- We had a site visit to JPFA's consumer products integrated complex (So Good Food Manufacturing) in Cikupa, the largest of its three downstream sites at 8ha (Boyolali and Wonoayu are ~4ha each). The site houses a chicken slaughterhouse (~3,000 birds/hour) and a frozen food plant with seven production lines producing 2,000-3,000 tonnes a month. It is fully integrated, with live birds sourced from Japfa Comfeed Indonesia’s (JPFA) own farm and slaughterhouse with around 90% of the output going into downstream processing (the rest is sold to B2B customers). Operations are highly automated, halal compliant and biomass-powered. The facility is already at full utilisation, with management expecting the current capacity to be insufficient within a year, supporting continued downstream expansion.
- Downstream holding up well. Despite a subdued FMCG market, the company remained positive, as its poultry processing and consumer products business still grew strongly at 29% yoy in 1H26 (17% to total revenue). JPFA sees significant room to grow its processed chicken business and plans to increase downstream processing from around 15% of chicken output currently to 40% by 2030, which we view positively as it should reduce margin and earnings volatility. Its processed meat brand, So Good, ranks in the top three alongside Kanzler (Cisarua Mountain Dairy) and Fiesta (Charoen Pokphand (CPIN)), while So Good is no.1 in frozen food in the Modern Trade channel. The company suggested it is continuing to gain share, while new product launches are accelerating, with around 10 new products this year and plans to double this to around 20 in 2027.
- Stepping up expansion. Capex is ramping up, with Rp3t planned for 2026 (Rp2.2t spent in 1H26), nearly matching 2025's Rp2.4t. With downstream utilisation at around 70%, JPFA is expanding processing capacity through new plants in Boyolali and Wonoayu, alongside a mega slaughterhouse in Nganjuk. The facility will process about 12,000 birds/hour, approximately 4x Cikupa's capacity, and is expected to start operations by end-26.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp2,000
Rp2,900
+45.0%
Rp3,330
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


