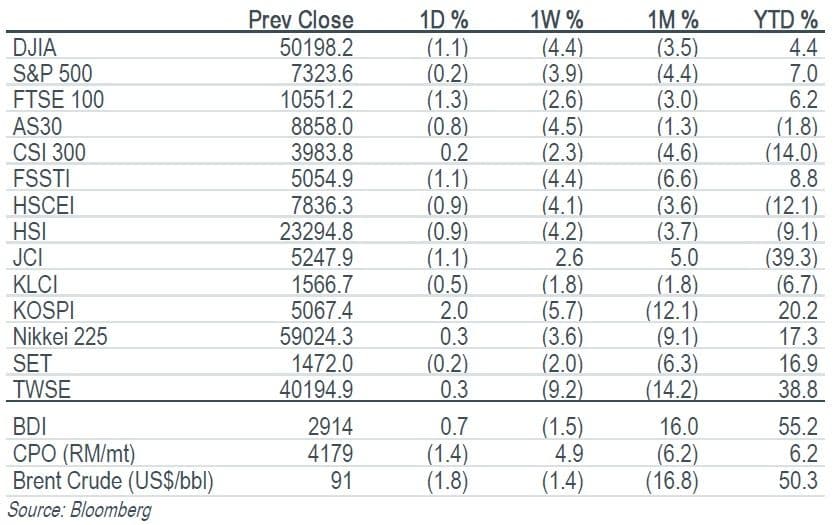
Key Indices
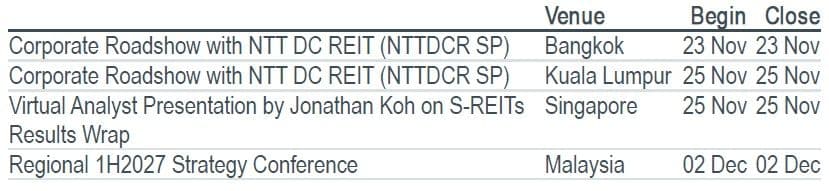
Top Stories
Economics | BI Surprises With Rate Hike to Defend the Rupiah
- Bank Indonesia surprised markets by raising its benchmark rate to 6.00% to defend the rupiah, which hit an all-time low of Rp18,264 (−8.47% ytd), and to pre-empt inflation amid declining forex reserves. Markets reacted negatively, with bond yields rising to 7.71% and the JCI falling 1%. The rupiah is expected to remain under pressure into 1Q27 due to a potential MSCI downgrade, a large current account deficit, and a strong US dollar.
Company Results | XLSMART Telecom Sejahtera (EXCL IJ/BUY/Rp1,715/Target: Rp3,000)
- We maintain BUY with a lower target price of Rp3,000, rolled over to 2027 and based on 4.9x 2027F EV/EBITDA, reflecting a more conservative valuation amid elevated capex requirements and a higher interest rate environment. EXCL’s core operations remain resilient, with ARPU and subscribers growing qoq, while the accelerated depreciation has been completed and merger synergies have exceeded expectations. These factors should support an earnings recovery and potential re-rating, although elevated 5G capex remains a key concern.
Technical Analysis
Bank Central Asia | BBCA IJ
- Trading Buy Range: We have a technical Buy at Rp5,750, and take profit at Rp6,025.
Erajaya Swasembada | ERAA IJ
- Trading Buy Range: We have a technical Buy at Rp520, and take profit at Rp575.
Top Stories
Economics | BI Surprises With Rate Hike to Defend the Rupiah
- Bank Indonesia surprised markets by raising its benchmark rate to 6.00% to defend the rupiah, which hit an all-time low of Rp18,264 (−8.47% ytd), and to pre-empt inflation amid declining forex reserves. Markets reacted negatively, with bond yields rising to 7.71% and the JCI falling 1%. The rupiah is expected to remain under pressure into 1Q27 due to a potential MSCI downgrade, a large current account deficit, and a strong US dollar.
Company Results | XLSMART Telecom Sejahtera (EXCL IJ/BUY/Rp1,715/Target: Rp3,000)
- We maintain BUY with a lower target price of Rp3,000, rolled over to 2027 and based on 4.9x 2027F EV/EBITDA, reflecting a more conservative valuation amid elevated capex requirements and a higher interest rate environment. EXCL’s core operations remain resilient, with ARPU and subscribers growing qoq, while the accelerated depreciation has been completed and merger synergies have exceeded expectations. These factors should support an earnings recovery and potential re-rating, although elevated 5G capex remains a key concern.
Technical Analysis
Bank Central Asia | BBCA IJ
- Trading Buy Range: We have a technical Buy at Rp5,750, and take profit at Rp6,025.
Erajaya Swasembada | ERAA IJ
- Trading Buy Range: We have a technical Buy at Rp520, and take profit at Rp575.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


