Company Coverage
Aneka Tambang (ANTM IJ): Margins Recovering, Growth Pipeline Intact
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp3,050
Rp4,100
+34.4%
Rp3,500
Analyst
Analyst
Highlights
- Gold margin recovery remains the key earnings driver. Lower inventory exposure, broader domestic sourcing, and stronger gold prices should support margin improvement in 2H26 despite softer sales volumes.
- Nickel and bauxite growth outlook remains intact. Higher nickel ore quotas support 2026 production, while the ramp-up of the Halmahera FeNi plant and Mempawah project should drive stronger nickel ore, ferronickel, and bauxite volumes in 2027.
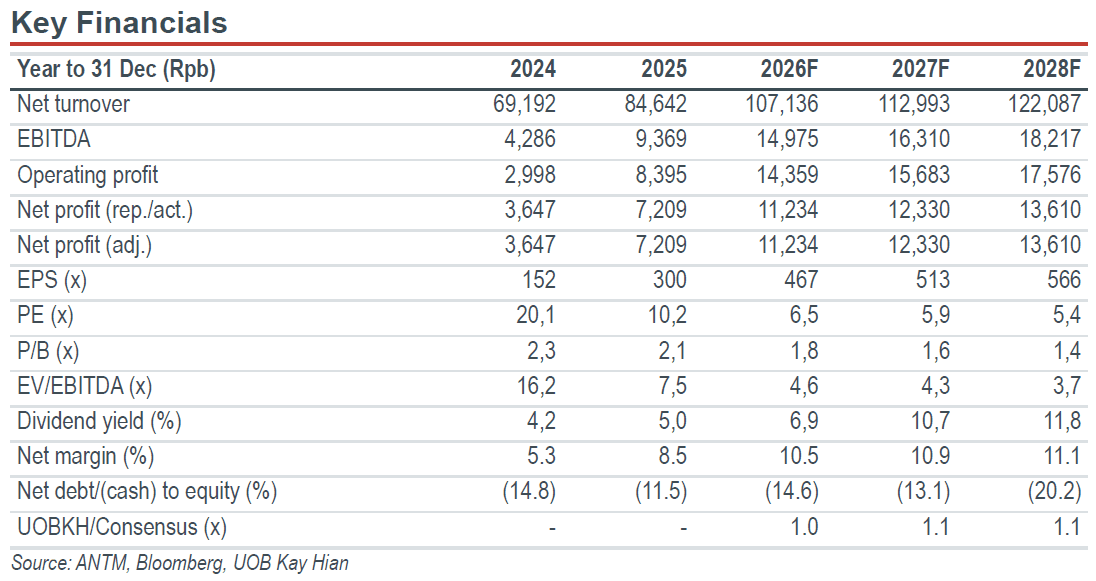
- Maintain BUY with a higher target price of Rp4,100 (from Rp3,500 previously). We remain positive on ANTM's long-term growth pipeline, supported by solid downstream earnings contributions from PMR, HPAL, RKEF, and SGAR.
Analysis
- Gold margin to recover as inventory normalises. Following the 2Q26 gold price correction, margins were pressured by roughly 6 tonnes of inventory (~two months of supply). Management has since reduced inventory targets to 15 days each for finished goods and raw materials. Broader sourcing from Freeport, Amman Minerals Internasional (AMMN), Merdeka Copper Gold (MDKA),Bumi Resources Minerals (BRMS), J Resources Asia Pasifik (PSAB), and Agincourt, together with higher domestic gold availability, should support feedstock security and margin recovery. We forecast 2026 gold sales of 31.2 tonnes (-9% yoy), with lower volumes offset by a 40% yoy increase in gold prices.
- Higher nickel ore quota supports 2026 volume outlook. The 2026 nickel ore quota has been revised up by almost 900,000t from 18.1mt, bringing the approved total to 19mt. Nickel ore production is running at 1.5-1.6mt per month, with July-August averaging 1.5mt per month, while 3Q26’s volume is higher than that of 2Q26.
- Higher nickel ore and bauxite production in 2027. Nickel ore production is expected at 18-20mt in 2027, subject to RKAB approval. Ferronickel production is expected to increase significantly, supported by the commissioning of the Halmahera FeNi plant in 4Q26. Bauxite production is expected to increase by more than 50%, following the commissioning of the Mempawah project in 1Q27, which will replace Tayan. Tayan's volumes can be redirected to other smelters. No additional quota has been confirmed for Weda Bay, in which ANTM holds a 10% stake.
Highlights
- Gold margin recovery remains the key earnings driver. Lower inventory exposure, broader domestic sourcing, and stronger gold prices should support margin improvement in 2H26 despite softer sales volumes.
- Nickel and bauxite growth outlook remains intact. Higher nickel ore quotas support 2026 production, while the ramp-up of the Halmahera FeNi plant and Mempawah project should drive stronger nickel ore, ferronickel, and bauxite volumes in 2027.
- Maintain BUY with a higher target price of Rp4,100 (from Rp3,500 previously). We remain positive on ANTM's long-term growth pipeline, supported by solid downstream earnings contributions from PMR, HPAL, RKEF, and SGAR.
Analysis
- Gold margin to recover as inventory normalises. Following the 2Q26 gold price correction, margins were pressured by roughly 6 tonnes of inventory (~two months of supply). Management has since reduced inventory targets to 15 days each for finished goods and raw materials. Broader sourcing from Freeport, Amman Minerals Internasional (AMMN), Merdeka Copper Gold (MDKA),Bumi Resources Minerals (BRMS), J Resources Asia Pasifik (PSAB), and Agincourt, together with higher domestic gold availability, should support feedstock security and margin recovery. We forecast 2026 gold sales of 31.2 tonnes (-9% yoy), with lower volumes offset by a 40% yoy increase in gold prices.
- Higher nickel ore quota supports 2026 volume outlook. The 2026 nickel ore quota has been revised up by almost 900,000t from 18.1mt, bringing the approved total to 19mt. Nickel ore production is running at 1.5-1.6mt per month, with July-August averaging 1.5mt per month, while 3Q26’s volume is higher than that of 2Q26.
- Higher nickel ore and bauxite production in 2027. Nickel ore production is expected at 18-20mt in 2027, subject to RKAB approval. Ferronickel production is expected to increase significantly, supported by the commissioning of the Halmahera FeNi plant in 4Q26. Bauxite production is expected to increase by more than 50%, following the commissioning of the Mempawah project in 1Q27, which will replace Tayan. Tayan's volumes can be redirected to other smelters. No additional quota has been confirmed for Weda Bay, in which ANTM holds a 10% stake.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp3,050
Rp4,100
+34.4%
Rp3,500
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


