Company Coverage
Sarana Menara Nusantara (TOWR IJ): 5G Densification And Potential DC Rollouts Offer Upside
BUY (Maintained)
Current price:
Target price:
Upside:
Rp458
Rp530
+15.7%
Analyst
Analyst
Highlights
- Potential upside from 5G densification. Selective 5G rollout could drive incremental tower demand, although operators have yet to provide specific rollout guidance.
- Fibre expansion and AI-related opportunities. TOWR’s fibre network is positioned to capture future data-centre rollouts, while connectivity to edge DCs provide an existing foothold.
- Maintain BUY with an unchanged target price of Rp530.
Analysis
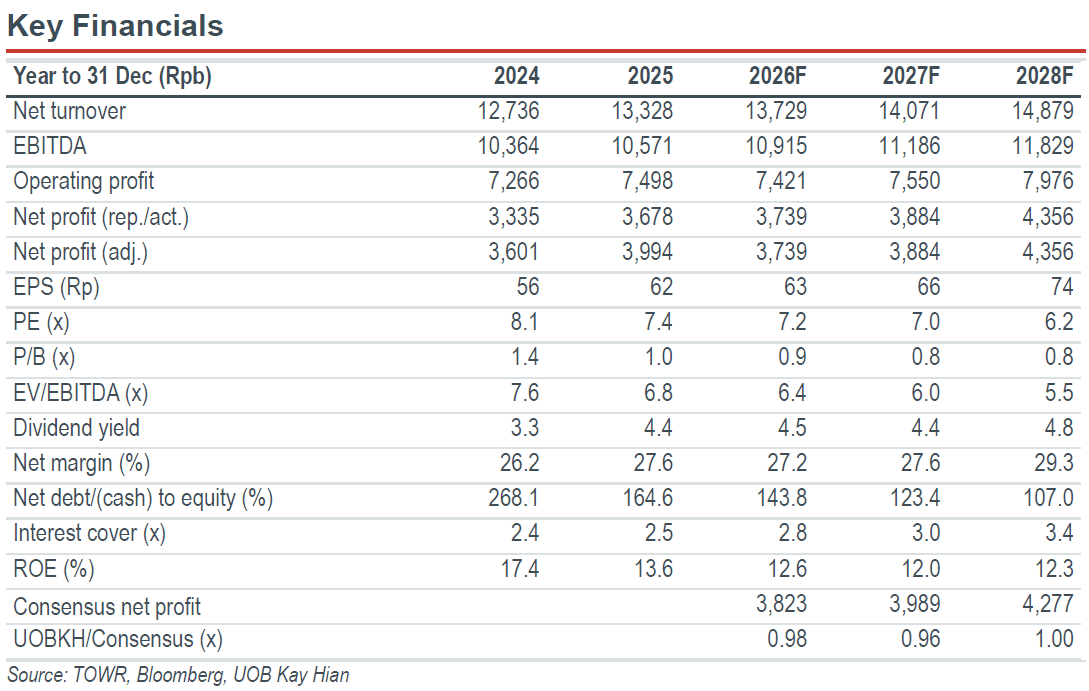
- Potential upside from 5G network densification. Higher mobile network operator capex guidance points to an upcoming 5G rollout, although deployment is likely to be selective rather than nationwide as with the 3G to 4G transition, with some operators targeting around 60% population coverage. As 5G requires denser sites than 4G, broader deployment could support incremental tower demand, although operators have yet to provide specific tower rollout guidance. Meanwhile, most site integration work has been completed following the XL Axiata-Smartfren merger, potentially easing pressure on colocation growth. Our sensitivity analysis indicates that a 1% increase in tower and tower tenants would lift net income by 1.5% and 1.4% respectively.
- Non-tower growth and AI-related opportunities. Sarana Menara Nusantara (TOWR) is expanding beyond tower leasing through its fibre and connectivity businesses, including its acquisition of Remala Abadi in 2025 and the consolidation of Bach Multi Global, with its ownership reaching 51% in Jul 26. TOWR’s extensive fibre network is well positioned to capture future data centre rollouts as demand for AI computing and data storage grows, while its existing fibre connectivity to edge data centres provide an established foothold. In 1H26, connectivity activations rose 48.3% yoy to 28,153, while fibre-to-the-home (FTTH) home-paid subscribers grew 77.8% yoy to 376,461. Our sensitivity analysis indicates that a 1% increase in fibre-to-the-tower (FTTT) utilisation would lift net income by 0.3%.
Highlights
- Potential upside from 5G densification. Selective 5G rollout could drive incremental tower demand, although operators have yet to provide specific rollout guidance.
- Fibre expansion and AI-related opportunities. TOWR’s fibre network is positioned to capture future data-centre rollouts, while connectivity to edge DCs provide an existing foothold.
- Maintain BUY with an unchanged target price of Rp530.
Analysis
- Potential upside from 5G network densification. Higher mobile network operator capex guidance points to an upcoming 5G rollout, although deployment is likely to be selective rather than nationwide as with the 3G to 4G transition, with some operators targeting around 60% population coverage. As 5G requires denser sites than 4G, broader deployment could support incremental tower demand, although operators have yet to provide specific tower rollout guidance. Meanwhile, most site integration work has been completed following the XL Axiata-Smartfren merger, potentially easing pressure on colocation growth. Our sensitivity analysis indicates that a 1% increase in tower and tower tenants would lift net income by 1.5% and 1.4% respectively.
- Non-tower growth and AI-related opportunities. Sarana Menara Nusantara (TOWR) is expanding beyond tower leasing through its fibre and connectivity businesses, including its acquisition of Remala Abadi in 2025 and the consolidation of Bach Multi Global, with its ownership reaching 51% in Jul 26. TOWR’s extensive fibre network is well positioned to capture future data centre rollouts as demand for AI computing and data storage grows, while its existing fibre connectivity to edge data centres provide an established foothold. In 1H26, connectivity activations rose 48.3% yoy to 28,153, while fibre-to-the-home (FTTH) home-paid subscribers grew 77.8% yoy to 376,461. Our sensitivity analysis indicates that a 1% increase in fibre-to-the-tower (FTTT) utilisation would lift net income by 0.3%.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp458
Rp530
+15.7%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


