Company Coverage
Astra International (ASII IJ): Investor Day Provides More Clarity On 2030 Targets
BUY (Maintained)
Current price:
Target price:
Upside:
Rp5,375
Rp7,100
+32.1%
Analyst
Analyst
Highlights
- 2030 targets supported by disciplined capital allocation. ASII targets ROE of above 15%, EPS of Rp1,150-1,200 and low-teens TSR by 2030.
- Core businesses remain key growth drivers. ASII targets to have a 48-50% share of the 4W market, while the financial services segment aims to deliver a 5% loan book CAGR while maintaining disciplined asset quality. MSHE earnings are expected to recover following Martabe's resumption and higher coal quotas.
- Maintain BUY with an SOTP-based target price of Rp7,100.
Analysis
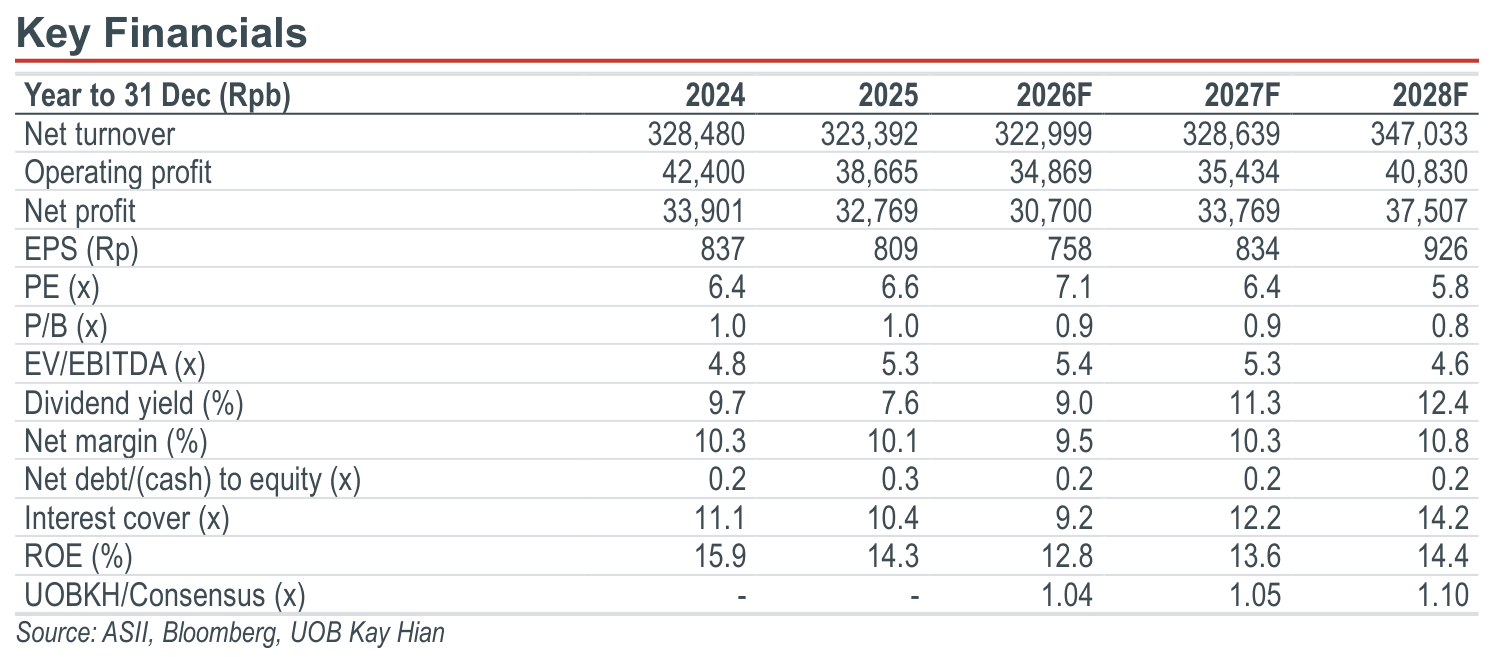
- Strengthening strategic focus with ambitious 2030 targets. Astra International (ASII) held its Investor Day on 16 Nov 26. It announced 2030 targets of ROE above 15% and EPS of Rp1,150-1,200, both excluding non-recurring items. The EPS target is 40-47% above 2025 EPS of Rp814, an implied CAGR of 7-8%. ASII also targets a low-teens annual total shareholder return (TSR) to 2030, built from a 6% dividend yield plus 7-8% EPS growth, which gives 13-14% TSR. The strategic review is focused on capital discipline, where ASII intends to reallocate Rp10t of wider portfolio net assets by 2030, based on Dec 25 carrying values. Its illustrative 2026-30 cash plan puts 30% into capex (80% maintenance and 20% projects), 40% into dividends under a 45-50% payout policy, and 30% into buybacks and investments.
- Automotive: Maintaining market leadership and expanding the customer ecosystem. ASII expects its four-wheeler (4W) market share to dip due to battery electric vehicles (BEV) in 2027 before it recovers in 2028. Its market share could fall to 45% in 2027 before new products arrive, and ASII aims to return its market share to 48-50% by 2030 while targeting a 10-15% share of the BEV or plug-in hybrid electric vehicle (PHEV) market. Planned launches by 2030 include a mass-market BEV, a mass-market 7-seater internal combustion engine (ICE) and a 7-seater hybrid electric vehicle (HEV), with the focus staying on ex-Java markets. Toyota plans to raise its investment in Indonesia, including with CATL, and ASII will also offer an affordable two-wheeler (2W) BEV. For 2030, ASII is assuming the 4W market will grow from 804,000 units in 2025 to 1.0-1.1m units, and the 2W market to rise from 6.4m to 7.1-7.3m units. It targets to achieve a 2W market share of 78% and components revenue of up to Rp30t.
- Financial services: Improving customer lifetime value and maintaining asset quality. ASII plans to raise customer lifetime value by: a) lending more to customers already in the Astra ecosystem after their first vehicle loan, and b) growing outside the ecosystem. It has also simplified the segment’s organisation. The 2030 targets are: a) loan book growth of 5% CAGR, b) non-performing financing (NPF) below 1% for 4W and heavy equipment, and c) below 2% for 2W.
Highlights
- 2030 targets supported by disciplined capital allocation. ASII targets ROE of above 15%, EPS of Rp1,150-1,200 and low-teens TSR by 2030.
- Core businesses remain key growth drivers. ASII targets to have a 48-50% share of the 4W market, while the financial services segment aims to deliver a 5% loan book CAGR while maintaining disciplined asset quality. MSHE earnings are expected to recover following Martabe's resumption and higher coal quotas.
- Maintain BUY with an SOTP-based target price of Rp7,100.
Analysis
- Strengthening strategic focus with ambitious 2030 targets. Astra International (ASII) held its Investor Day on 16 Nov 26. It announced 2030 targets of ROE above 15% and EPS of Rp1,150-1,200, both excluding non-recurring items. The EPS target is 40-47% above 2025 EPS of Rp814, an implied CAGR of 7-8%. ASII also targets a low-teens annual total shareholder return (TSR) to 2030, built from a 6% dividend yield plus 7-8% EPS growth, which gives 13-14% TSR. The strategic review is focused on capital discipline, where ASII intends to reallocate Rp10t of wider portfolio net assets by 2030, based on Dec 25 carrying values. Its illustrative 2026-30 cash plan puts 30% into capex (80% maintenance and 20% projects), 40% into dividends under a 45-50% payout policy, and 30% into buybacks and investments.
- Automotive: Maintaining market leadership and expanding the customer ecosystem. ASII expects its four-wheeler (4W) market share to dip due to battery electric vehicles (BEV) in 2027 before it recovers in 2028. Its market share could fall to 45% in 2027 before new products arrive, and ASII aims to return its market share to 48-50% by 2030 while targeting a 10-15% share of the BEV or plug-in hybrid electric vehicle (PHEV) market. Planned launches by 2030 include a mass-market BEV, a mass-market 7-seater internal combustion engine (ICE) and a 7-seater hybrid electric vehicle (HEV), with the focus staying on ex-Java markets. Toyota plans to raise its investment in Indonesia, including with CATL, and ASII will also offer an affordable two-wheeler (2W) BEV. For 2030, ASII is assuming the 4W market will grow from 804,000 units in 2025 to 1.0-1.1m units, and the 2W market to rise from 6.4m to 7.1-7.3m units. It targets to achieve a 2W market share of 78% and components revenue of up to Rp30t.
- Financial services: Improving customer lifetime value and maintaining asset quality. ASII plans to raise customer lifetime value by: a) lending more to customers already in the Astra ecosystem after their first vehicle loan, and b) growing outside the ecosystem. It has also simplified the segment’s organisation. The 2030 targets are: a) loan book growth of 5% CAGR, b) non-performing financing (NPF) below 1% for 4W and heavy equipment, and c) below 2% for 2W.
BUY (Maintained)
Current price:
Target price:
Upside:
Rp5,375
Rp7,100
+32.1%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


