Wealth Daily
Earnings Misses, AI Concerns Offset Demand
Today’s Must-Know News
Overnight Markets
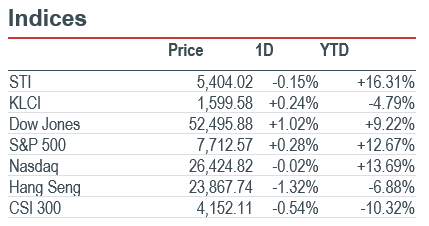
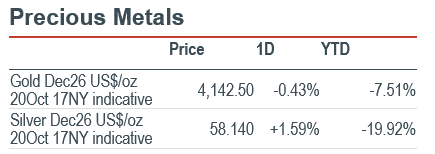
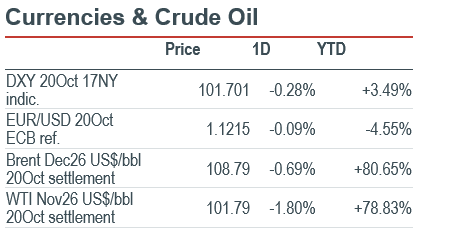
Market Movers: The S&P 500 gained 0.28%. Nvidia (NVDA US) slipped 0.29%, despite reported Chinese graphics-card orders worth over US$35bn at sticker prices; fulfilment is not guaranteed. ABB (ABBN SW) fell 5.01% in Switzerland despite third-quarter orders rising 40% YoY and operational EBITA increasing 24%, underscoring AI-spending concerns. CATL (300750.SZ) fell 2.97% in China before its evening results: quarterly profit grew 14.5% YoY to RMB21.2bn, below a 41.2% growth estimate. Strong demand therefore coexists with earnings-expectation and supply constraints. (Reuters / ABB / Reuters / Reuters / Market data / Market data / Market data / Market data) Nvidia (NVDA US) and CATL (300750.SZ) are our Core Recommendations.
Macro: US September housing starts fell 5.2% MoM and 7.4% YoY to 1.221m annualised, although both declines were statistically uncertain. Permits fell 3.0% YoY to 1.400m, adding evidence of construction weakness. China published one-year and five-year-plus loan prime rates of 3.00% and 3.50% as benchmarks for financing costs. (US Census / PBOC)
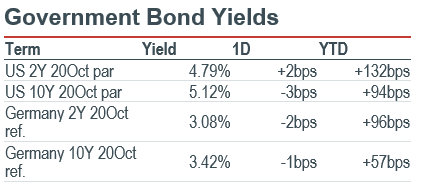
FICC: December Brent settled 0.69% lower at US$108.79/bbl. Expiring November WTI fell 1.80% to US$101.79, while December WTI closed at US$97.82. Expiry positioning and Russian-diesel sanctions relief tempered supply fears. The US 10-year par yield eased 3bps to 5.12% ; December silver rose 1.59% at the matched 17:00 New York indicative snapshot. (DTN / US Treasury / Market data)
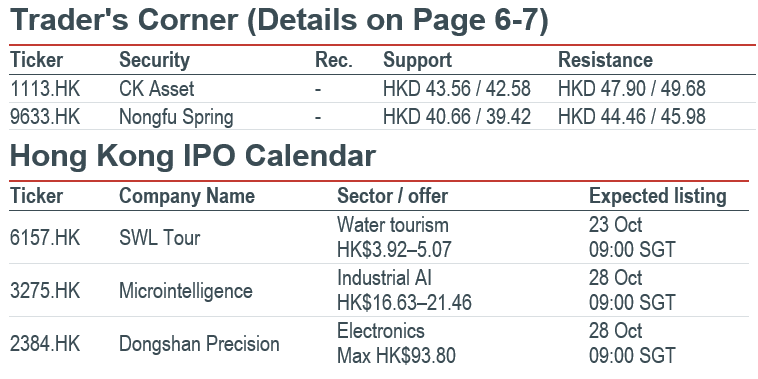
AI
• Nvidia (NVDA US) faces excess Chinese demand. Reuters reported that ByteDance, Alibaba (9988.HK) and Tencent (0700.HK) ordered over 3m RTX PRO 5500 cards, worth over US$35bn at sticker prices. Nvidia reportedly cannot guarantee fulfilment. The less-powerful, export-compliant workstation chips serve inference workloads, underscoring latent demand, although these reported orders should not be treated as secured revenue. (Reuters) Nvidia (NVDA US) is our Core Recommendation.
• SpaceX (SPCX US) combines AI growth with merger exploration. 3Q26 revenue rose 161% YoY to US$14.6bn, including AI revenue up 830% to US$7.6bn; US$19.6bn capex underscores funding demands. Musk said independent committees at SpaceX and Tesla (TSLA US) are exploring a merger. (SpaceX / Investing.com)
• OpenAI accelerates its reported funding push. Reuters reported that the private company is seeking investor commitments ahead of Anthropic’s expected IPO, with roughly US$30bn of financing potentially valuing it above US$1.4tn. Its investor pitch cites US$50bn in annualised revenue, rather than revenue already earned. (Reuters)
• Super Micro Computer (SMCI US) lifts preliminary sales. The server maker indicated 1QFY27 revenue of US$18.5–19.5bn, versus its previous US$14.5–15.5bn range, and gross margin of 12–12.5%, up from 10.4–10.8%, citing a favourable product mix. Shares rose 11.3% in after-hours trading. (Reuters)
Americas
• Apple (AAPL US) faces a shipment downgrade. Loop Capital cut its rating from Buy to Hold and its target from US$370 to US$330, citing checks suggesting 13m planned second-half iPhone shipments will not be recovered in 2027. This is a broker estimate, not company guidance. Shares fell 1.00%; supply constraints and launch timing complicate interpreting the cuts as weaker underlying demand. (Investing.com / AppleInsider / Market data)
• GE Aerospace (GE US) raises guidance but retreats. 3Q26 adjusted revenue increased 18% YoY to US$13.3bn and adjusted EPS rose 36% to US$2.25. FY26 EPS guidance increased to US$8.00–8.10 from US$7.65–7.85. Shares nevertheless fell 3.67% as the implied 4Q26 earnings outlook disappointed investors, showing that strong engine-services demand must also translate into sustained near-term profit delivery. (GE Aerospace / Reuters / Market data)
• 3M (MMM US) gains on earnings and data-centre exposure. Adjusted EPS rose 12% YoY to US$2.50 on rebased comparatives; FY26 guidance reached US$9.10–9.15. Shares gained 5.78%. Separately, 85% of a warrant issued to Amazon (AMZN US) would vest as cumulative purchases reach US$6bn. The arrangement expands data-centre exposure, but that purchasing threshold is not a committed sales forecast. (3M / Reuters / Market data) Amazon (AMZN US) is our Core Recommendation.
• Salesforce (CRM US) agrees to acquire Braze (BRZE US). The US$5.66bn enterprise-value transaction offers US$47.50 cash per share; Braze surged 51.70%. Its customer-engagement and AI decisioning capabilities would extend Salesforce’s marketing platform. Completion is expected in Salesforce’s FY28, subject to shareholder and regulatory approvals. The deal expands cross-selling opportunities, while integration and approval risks remain before those benefits can be realised. (Salesforce / Market data)
• Netflix (NFLX US) delivers profit growth with softer advertising. 3Q26 revenue increased 12% YoY to US$12.87bn and EPS reached US$0.87 versus US$0.59 a year earlier. However, its FY26 advertising-revenue outlook fell to about US$2.7bn from US$3bn because new advertising features are rolling out more slowly. The after-close release highlights strong underlying earnings alongside execution risk in a developing growth channel. (Netflix)
• RTX (RTX US) raises its earnings outlook. 3Q26 sales increased 11% YoY to US$25.0bn, while adjusted EPS rose 33% to US$2.26, including US$0.25 of tariff-related cost recovery. FY26 adjusted EPS guidance rose to US$7.65–7.75 from US$7.10–7.25. A record US$340bn backlog supports visibility across defence and commercial aerospace, although the recovery contribution tempers extrapolation of the quarter’s earnings growth. (RTX)
• General Motors (GM US) falls as costs cloud guidance. 3Q26 adjusted EBIT rose 22% YoY to US$4.1bn and the board approved a US$20bn buyback. However, the US$12.75–13.75 FY26 adjusted EPS range has a midpoint below the US$13.41 consensus. Shares fell 6.84%; higher commodity and logistics costs, plus fewer truck deliveries during model changes, constrain the near-term earnings outlook. (Reuters / Market data)
• Boeing (BA US) secures MAX 10 certification. The FAA approved the 737 MAX 10, clearing the aircraft for delivery and commercial service. Boeing reports 1,555 orders from more than 30 customers, representing over 30% of the MAX’s current order book. Certification removes a major programme hurdle; production capacity, customer acceptance and delivery execution will determine how quickly the backlog becomes cash. (FAA / Boeing)
• Equifax (EFX US) rallies despite mortgage pressure. 3Q26 revenue rose 10% YoY to US$1.693bn and adjusted EPS increased 11% to US$2.26. Shares gained 11.33%, although the FY26 adjusted EPS midpoint fell four cents to US$8.50. AI-driven cost efficiencies are expected to cushion weaker mortgage activity, making operating execution, rather than a housing recovery alone, central to the earnings outlook. (Equifax / Market data)
Greater China
• CATL (300750.SZ) profit growth undershoots expectations. CATL reported Q3 profit of RMB21.25bn, up 14.54% YoY, while revenue climbed 58.58% to RMB165.22bn. Reuters’ cited forecast implied 41.2% profit growth. The gap highlights battery-market competition despite expanding sales. A-shares closed 2.97% lower at RMB259.08 before the results, so that decline is not an earnings reaction. (HKEX / Reuters / Market data) CATL (300750.SZ) is our Core Recommendation.
• China Mobile (0941.HK) earnings weaken despite customer growth. Nine-month profit fell 7.9% YoY to RMB106.2bn and revenue declined 1.8% to RMB780.3bn, its 20 October release showed. Principal-business revenue dropped 3.7%, while EBITDA fell 6.7%. Mobile subscribers reached 1.014bn. The divergence puts monetisation and cost discipline in focus as the group expands computing and AI services. (HKEX / Market data) China Mobile (0941.HK) is our Core Recommendation.
• Hansoh Pharmaceutical (3692.HK) rallies on its first post-deal session. Shares gained 8.32% to HK$34.38 after Hong Kong’s holiday, following the 19 October Roche collaboration announcement. Terms comprise US$400m upfront, US$110m on the first anniversary and potentially over US$15bn in milestones. Those development, regulatory and commercial payments remain conditional; the agreement validates its antibody-drug-conjugate platform without guaranteeing the headline value. (Company / New TimeSpace)
• Lenovo (0992.HK) drops sharply while expanding its AI partnerships. Shares closed down 9.98% at HK$25.26. Separately, Rafay announced joint sales alignment with Lenovo across the Americas, EMEA and Asia-Pacific, offering software that manages GPU infrastructure and meters usage. The collaboration targets monetisation of installed capacity; it supplies no disclosed contract value to offset uncertainty over future commercial returns. (Company / MT Newswires)
Asia ex. China
• Sea (SE US) outlines a cloud business and possible Monee listing. In its employee letter, management said roughly 500 staff had rebuilt its platform over two years and would offer Sea Cloud externally. It also said financial-services arm Monee was approaching independence. Shares fell 9.09% to US$80.43. A possible IPO could fund expansion, but the letter set no transaction timetable. (Company / Fintech News / Market data)
• Keppel REIT (K71U.SI) proposes a 51% South Central acquisition. The proposal carries approximately S$610.9m consideration and 2.01% pro-forma distribution accretion, including income support and specified divestments. The sponsor guarantees S$2.23m monthly income for up to five years. Units fell 4.85% to S$0.785. Completion, expected in Q2 2027, requires unitholder approval; lease-up and financing remain central to returns. (Company / SGX / Market data)
EMEA and Others
• ABB (ABBN.SW) falls despite record orders and stronger earnings. Shares lost 5.01% to CHF70.96. Q3 orders rose 40% YoY to US$12.055bn and operational EBITA increased 24% to US$2.026bn; revenue grew 14%. Reuters linked selling to doubts about sustainable AI infrastructure spending. Strong equipment demand therefore remains exposed to customers’ financing capacity and confidence in eventual returns. (Company / Reuters / Market data)
• EssilorLuxottica (EL.PA) beats revenue forecasts as wearables growth slows. Its 20 October release showed Q3 sales of €7.486bn, up 9.0% YoY and 7.2% at constant currencies, above Reuters’ cited €7.36bn consensus. Wearables generated €486m, growing 20%, versus nearly 100% growth in Q2. This preserves evidence of demand while making underlying eyecare growth increasingly important to the investment case. (Reuters / Infinance / Market data)
• BBVA (BBVA.MC) receives a one-notch Morningstar DBRS upgrade. The bank’s regulatory filing confirmed its long-term senior issuer rating rose to AA (low) from A (high), with the outlook moving to stable from positive. Subordinated debt improved to A from A (low). The action supports credit standing, although actual funding costs will also depend on market spreads and rates. (Company / RNS / Market data)
• Deutsche Börse (DB1.DE) raises its revenue outlook again. Its 20 October results showed 3Q net revenue rising 13% YoY to €1.633bn and shareholder profit increasing 18% to €559m. Treasury income rose 7%, its first annual increase since 2024, while EBITDA grew 16%. Trading activity and asset-servicing flows support operating leverage; the analyst call is scheduled for 21 October at 20:00 SGT. (Company / Market data)
• Adidas (ADS.DE) lifts its profit outlook after a record quarter. Preliminary results showed 3Q revenue rising 9% YoY to €7.252bn and operating profit climbing 37% to €1.008bn. A roughly €200m US tariff refund helped margins. After planned reinvestment, 2026 operating-profit guidance increases to around €2.5bn from €2.3bn; the refund’s non-recurring benefit tempers extrapolation. (Company / Market data)
Traders' Corner
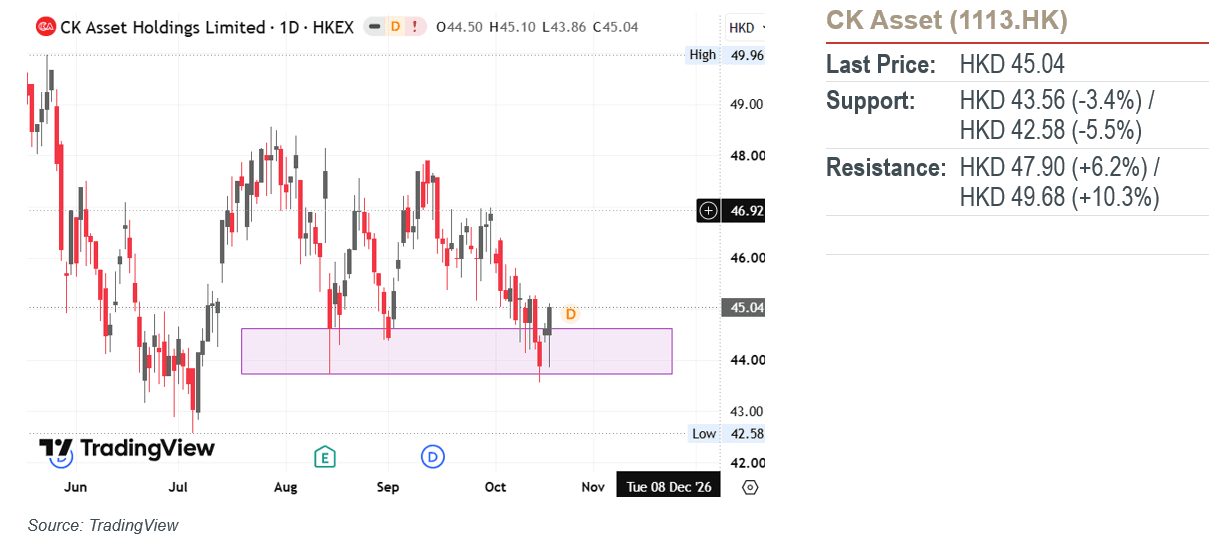
Our Technical View
Price rebounded off its previous horizontal support zone and preserving the integrity of the demand floor.
The RSI exhibits a sustained positive slope as it climbs toward its neutral 50-midline, signaling an influx of buy-side initiative.
As long as price holds above this defended support floor, we see continued bullish expansion targeting overhead resistance.
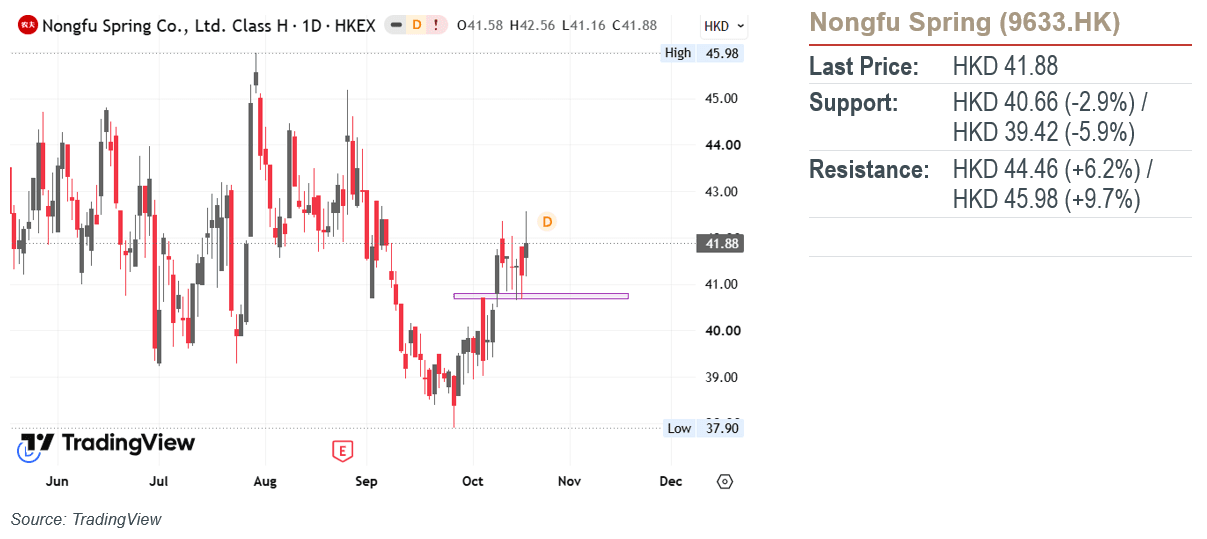
Our Technical View
Price executed a break-and-retest sequence at its resistance-turned-support zone.
The RSI remains in bullish territory and continues to slope upward with positive velocity, signaling expanding buy-side momentum.
As long as price holds above this newly converted support floor, we see continued upward expansion toward upper overhead resistance targets.
Market Movers: The S&P 500 gained 0.28%. Nvidia (NVDA US) slipped 0.29%, despite reported Chinese graphics-card orders worth over US$35bn at sticker prices; fulfilment is not guaranteed. ABB (ABBN SW) fell 5.01% in Switzerland despite third-quarter orders rising 40% YoY and operational EBITA increasing 24%, underscoring AI-spending concerns. CATL (300750.SZ) fell 2.97% in China before its evening results: quarterly profit grew 14.5% YoY to RMB21.2bn, below a 41.2% growth estimate. Strong demand therefore coexists with earnings-expectation and supply constraints. (Reuters / ABB / Reuters / Reuters / Market data / Market data / Market data / Market data) Nvidia (NVDA US) and CATL (300750.SZ) are our Core Recommendations.
Macro: US September housing starts fell 5.2% MoM and 7.4% YoY to 1.221m annualised, although both declines were statistically uncertain. Permits fell 3.0% YoY to 1.400m, adding evidence of construction weakness. China published one-year and five-year-plus loan prime rates of 3.00% and 3.50% as benchmarks for financing costs. (US Census / PBOC)
FICC: December Brent settled 0.69% lower at US$108.79/bbl. Expiring November WTI fell 1.80% to US$101.79, while December WTI closed at US$97.82. Expiry positioning and Russian-diesel sanctions relief tempered supply fears. The US 10-year par yield eased 3bps to 5.12% ; December silver rose 1.59% at the matched 17:00 New York indicative snapshot. (DTN / US Treasury / Market data)
AI
• Nvidia (NVDA US) faces excess Chinese demand. Reuters reported that ByteDance, Alibaba (9988.HK) and Tencent (0700.HK) ordered over 3m RTX PRO 5500 cards, worth over US$35bn at sticker prices. Nvidia reportedly cannot guarantee fulfilment. The less-powerful, export-compliant workstation chips serve inference workloads, underscoring latent demand, although these reported orders should not be treated as secured revenue. (Reuters) Nvidia (NVDA US) is our Core Recommendation.
• SpaceX (SPCX US) combines AI growth with merger exploration. 3Q26 revenue rose 161% YoY to US$14.6bn, including AI revenue up 830% to US$7.6bn; US$19.6bn capex underscores funding demands. Musk said independent committees at SpaceX and Tesla (TSLA US) are exploring a merger. (SpaceX / Investing.com)
• OpenAI accelerates its reported funding push. Reuters reported that the private company is seeking investor commitments ahead of Anthropic’s expected IPO, with roughly US$30bn of financing potentially valuing it above US$1.4tn. Its investor pitch cites US$50bn in annualised revenue, rather than revenue already earned. (Reuters)
• Super Micro Computer (SMCI US) lifts preliminary sales. The server maker indicated 1QFY27 revenue of US$18.5–19.5bn, versus its previous US$14.5–15.5bn range, and gross margin of 12–12.5%, up from 10.4–10.8%, citing a favourable product mix. Shares rose 11.3% in after-hours trading. (Reuters)
Americas
• Apple (AAPL US) faces a shipment downgrade. Loop Capital cut its rating from Buy to Hold and its target from US$370 to US$330, citing checks suggesting 13m planned second-half iPhone shipments will not be recovered in 2027. This is a broker estimate, not company guidance. Shares fell 1.00%; supply constraints and launch timing complicate interpreting the cuts as weaker underlying demand. (Investing.com / AppleInsider / Market data)
• GE Aerospace (GE US) raises guidance but retreats. 3Q26 adjusted revenue increased 18% YoY to US$13.3bn and adjusted EPS rose 36% to US$2.25. FY26 EPS guidance increased to US$8.00–8.10 from US$7.65–7.85. Shares nevertheless fell 3.67% as the implied 4Q26 earnings outlook disappointed investors, showing that strong engine-services demand must also translate into sustained near-term profit delivery. (GE Aerospace / Reuters / Market data)
• 3M (MMM US) gains on earnings and data-centre exposure. Adjusted EPS rose 12% YoY to US$2.50 on rebased comparatives; FY26 guidance reached US$9.10–9.15. Shares gained 5.78%. Separately, 85% of a warrant issued to Amazon (AMZN US) would vest as cumulative purchases reach US$6bn. The arrangement expands data-centre exposure, but that purchasing threshold is not a committed sales forecast. (3M / Reuters / Market data) Amazon (AMZN US) is our Core Recommendation.
• Salesforce (CRM US) agrees to acquire Braze (BRZE US). The US$5.66bn enterprise-value transaction offers US$47.50 cash per share; Braze surged 51.70%. Its customer-engagement and AI decisioning capabilities would extend Salesforce’s marketing platform. Completion is expected in Salesforce’s FY28, subject to shareholder and regulatory approvals. The deal expands cross-selling opportunities, while integration and approval risks remain before those benefits can be realised. (Salesforce / Market data)
• Netflix (NFLX US) delivers profit growth with softer advertising. 3Q26 revenue increased 12% YoY to US$12.87bn and EPS reached US$0.87 versus US$0.59 a year earlier. However, its FY26 advertising-revenue outlook fell to about US$2.7bn from US$3bn because new advertising features are rolling out more slowly. The after-close release highlights strong underlying earnings alongside execution risk in a developing growth channel. (Netflix)
• RTX (RTX US) raises its earnings outlook. 3Q26 sales increased 11% YoY to US$25.0bn, while adjusted EPS rose 33% to US$2.26, including US$0.25 of tariff-related cost recovery. FY26 adjusted EPS guidance rose to US$7.65–7.75 from US$7.10–7.25. A record US$340bn backlog supports visibility across defence and commercial aerospace, although the recovery contribution tempers extrapolation of the quarter’s earnings growth. (RTX)
• General Motors (GM US) falls as costs cloud guidance. 3Q26 adjusted EBIT rose 22% YoY to US$4.1bn and the board approved a US$20bn buyback. However, the US$12.75–13.75 FY26 adjusted EPS range has a midpoint below the US$13.41 consensus. Shares fell 6.84%; higher commodity and logistics costs, plus fewer truck deliveries during model changes, constrain the near-term earnings outlook. (Reuters / Market data)
• Boeing (BA US) secures MAX 10 certification. The FAA approved the 737 MAX 10, clearing the aircraft for delivery and commercial service. Boeing reports 1,555 orders from more than 30 customers, representing over 30% of the MAX’s current order book. Certification removes a major programme hurdle; production capacity, customer acceptance and delivery execution will determine how quickly the backlog becomes cash. (FAA / Boeing)
• Equifax (EFX US) rallies despite mortgage pressure. 3Q26 revenue rose 10% YoY to US$1.693bn and adjusted EPS increased 11% to US$2.26. Shares gained 11.33%, although the FY26 adjusted EPS midpoint fell four cents to US$8.50. AI-driven cost efficiencies are expected to cushion weaker mortgage activity, making operating execution, rather than a housing recovery alone, central to the earnings outlook. (Equifax / Market data)
Greater China
• CATL (300750.SZ) profit growth undershoots expectations. CATL reported Q3 profit of RMB21.25bn, up 14.54% YoY, while revenue climbed 58.58% to RMB165.22bn. Reuters’ cited forecast implied 41.2% profit growth. The gap highlights battery-market competition despite expanding sales. A-shares closed 2.97% lower at RMB259.08 before the results, so that decline is not an earnings reaction. (HKEX / Reuters / Market data) CATL (300750.SZ) is our Core Recommendation.
• China Mobile (0941.HK) earnings weaken despite customer growth. Nine-month profit fell 7.9% YoY to RMB106.2bn and revenue declined 1.8% to RMB780.3bn, its 20 October release showed. Principal-business revenue dropped 3.7%, while EBITDA fell 6.7%. Mobile subscribers reached 1.014bn. The divergence puts monetisation and cost discipline in focus as the group expands computing and AI services. (HKEX / Market data) China Mobile (0941.HK) is our Core Recommendation.
• Hansoh Pharmaceutical (3692.HK) rallies on its first post-deal session. Shares gained 8.32% to HK$34.38 after Hong Kong’s holiday, following the 19 October Roche collaboration announcement. Terms comprise US$400m upfront, US$110m on the first anniversary and potentially over US$15bn in milestones. Those development, regulatory and commercial payments remain conditional; the agreement validates its antibody-drug-conjugate platform without guaranteeing the headline value. (Company / New TimeSpace)
• Lenovo (0992.HK) drops sharply while expanding its AI partnerships. Shares closed down 9.98% at HK$25.26. Separately, Rafay announced joint sales alignment with Lenovo across the Americas, EMEA and Asia-Pacific, offering software that manages GPU infrastructure and meters usage. The collaboration targets monetisation of installed capacity; it supplies no disclosed contract value to offset uncertainty over future commercial returns. (Company / MT Newswires)
Asia ex. China
• Sea (SE US) outlines a cloud business and possible Monee listing. In its employee letter, management said roughly 500 staff had rebuilt its platform over two years and would offer Sea Cloud externally. It also said financial-services arm Monee was approaching independence. Shares fell 9.09% to US$80.43. A possible IPO could fund expansion, but the letter set no transaction timetable. (Company / Fintech News / Market data)
• Keppel REIT (K71U.SI) proposes a 51% South Central acquisition. The proposal carries approximately S$610.9m consideration and 2.01% pro-forma distribution accretion, including income support and specified divestments. The sponsor guarantees S$2.23m monthly income for up to five years. Units fell 4.85% to S$0.785. Completion, expected in Q2 2027, requires unitholder approval; lease-up and financing remain central to returns. (Company / SGX / Market data)
EMEA and Others
• ABB (ABBN.SW) falls despite record orders and stronger earnings. Shares lost 5.01% to CHF70.96. Q3 orders rose 40% YoY to US$12.055bn and operational EBITA increased 24% to US$2.026bn; revenue grew 14%. Reuters linked selling to doubts about sustainable AI infrastructure spending. Strong equipment demand therefore remains exposed to customers’ financing capacity and confidence in eventual returns. (Company / Reuters / Market data)
• EssilorLuxottica (EL.PA) beats revenue forecasts as wearables growth slows. Its 20 October release showed Q3 sales of €7.486bn, up 9.0% YoY and 7.2% at constant currencies, above Reuters’ cited €7.36bn consensus. Wearables generated €486m, growing 20%, versus nearly 100% growth in Q2. This preserves evidence of demand while making underlying eyecare growth increasingly important to the investment case. (Reuters / Infinance / Market data)
• BBVA (BBVA.MC) receives a one-notch Morningstar DBRS upgrade. The bank’s regulatory filing confirmed its long-term senior issuer rating rose to AA (low) from A (high), with the outlook moving to stable from positive. Subordinated debt improved to A from A (low). The action supports credit standing, although actual funding costs will also depend on market spreads and rates. (Company / RNS / Market data)
• Deutsche Börse (DB1.DE) raises its revenue outlook again. Its 20 October results showed 3Q net revenue rising 13% YoY to €1.633bn and shareholder profit increasing 18% to €559m. Treasury income rose 7%, its first annual increase since 2024, while EBITDA grew 16%. Trading activity and asset-servicing flows support operating leverage; the analyst call is scheduled for 21 October at 20:00 SGT. (Company / Market data)
• Adidas (ADS.DE) lifts its profit outlook after a record quarter. Preliminary results showed 3Q revenue rising 9% YoY to €7.252bn and operating profit climbing 37% to €1.008bn. A roughly €200m US tariff refund helped margins. After planned reinvestment, 2026 operating-profit guidance increases to around €2.5bn from €2.3bn; the refund’s non-recurring benefit tempers extrapolation. (Company / Market data)
Traders' Corner
Our Technical View
Price rebounded off its previous horizontal support zone and preserving the integrity of the demand floor.
The RSI exhibits a sustained positive slope as it climbs toward its neutral 50-midline, signaling an influx of buy-side initiative.
As long as price holds above this defended support floor, we see continued bullish expansion targeting overhead resistance.
Our Technical View
Price executed a break-and-retest sequence at its resistance-turned-support zone.
The RSI remains in bullish territory and continues to slope upward with positive velocity, signaling expanding buy-side momentum.
As long as price holds above this newly converted support floor, we see continued upward expansion toward upper overhead resistance targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


